What a Hardmoney Calculator Actually Does (And What It Doesn't)
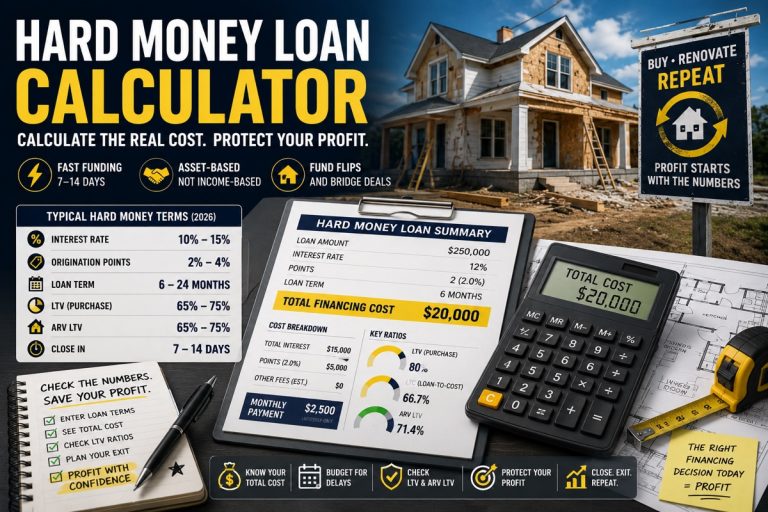
A hard money calculator is a tool that estimates the numbers on a hard money loan deal before you commit. You plug in the purchase price, the after repair value, the loan amount, the interest rate, and the points. It spits out your monthly payment, total closing costs, and often your projected profit if you're flipping. That is it. Nothing magical.
The reason these exist is simple. Hard money lenders charge way more than banks. Rates run from 10 to 15 percent. Points run from 2 to 5. And they want your money yesterday. You do not have time to manually square away the math while the seller waits on you.
Using a Hardmoney Calculator Step by Step
Most calculators follow the same basic layout. You enter the property address or just the numbers. Then you fill in the acquisition price. After that goes the ARV. Some calculators ask for renovation costs. Others skip that and just want the loan terms.
The critical fields are the interest rate and the points. A point equals 1 percent of the loan amount. So on a $200,000 loan at 3 points, you pay $6,000 upfront. Add a 12 percent annual rate and the monthly interest alone hits $2,000. That is money gone every month whether the project moves fast or slow.
You then enter the loan term. Hard money loans typically run 6 to 24 months. Some are balloon payments where you pay only interest monthly and the full principal comes due at the end. The calculator will show you both scenarios side by side.
After you hit calculate, you get a breakdown. Monthly payment. Total interest paid over the life of the loan. Total cost including points and fees. Some calculators also show the exit strategy cost if you plan to refinance into a conventional loan later.
I once worked a deal where the calculator showed a clean profit on paper. The numbers looked fine. The monthly payment was $3,200. Total interest came to about $19,000 over 9 months. But I forgot to add the lender's appraisal fee, the title insurance, and the servicing fee. That added another $4,500 to the table. The calculator did not include them because they are lender-specific. I learned to always add a 2 to 3 percent buffer on top of what the calculator outputs. It saved me from eating into the profit margin without realizing it.
The Numbers That Actually Matter
Here is the core formula behind most hard money calculators. It is not complicated.
Monthly payment equals the loan balance times the monthly interest rate. That is the loan amount multiplied by the annual rate divided by 12. If you are making principal and interest payments, it becomes an amortization calculation. Most hard money loans are interest only though, so the monthly payment is just the interest portion.
The total cost of the loan is the monthly payment times the number of months, plus the points, plus any origination fees. Origination fees typically run 1 to 2 percent of the loan amount. Some lenders roll them into the loan. Others want them paid at closing.
Your maximum loan amount depends on the lender's loan to value ratio. Hard money lenders usually lend 60 to 75 percent of the ARV or the purchase price, whichever is lower. The formula is simple. Take the ARV, multiply it by the LTV, and that is your max loan. Some lenders use the purchase price plus repairs instead. Always confirm which method they use before you run the calculator.
Why Hardmoney Calculator Results Can Mislead You
The biggest problem I see is that people treat the calculator output as final. It is not final. It is a starting point.
Lenders vary widely. One lender might charge 11 percent with 2 points and a 1 percent origination fee. Another charges 13 percent with 0 points but a 3 percent processing fee. The calculator might show the first deal costing $28,000 total and the second costing $31,000. But the second lender might be faster to fund, which means you close the deal sooner and reduce carrying costs. Speed has a dollar value that the calculator does not capture.
Another issue is the timeline assumption. Calculators assume you hold the loan for the full term. In reality, many investors pay off early. If you refinance at month 5 instead of month 9, your total interest drops significantly. A good calculator lets you adjust the payoff date. If yours does not, you need to do a quick manual adjustment. Multiply the monthly payment by the actual months held instead of the full term.
I also encountered a case where a calculator gave me a monthly payment of $2,500 but did not account for prepaid interest. Prepaid interest is the interest that accrues from the funding date to the first payment date. If you close on the 15th and your first payment is due on the 1st, you owe 16 days of interest upfront. On a $250,000 loan at 12 percent, that is roughly $1,300. It is a small line item but it adds up across multiple deals.
When a Hardmoney Calculator Fails Completely
There are scenarios where a standard calculator gives you garbage results.
If you are doing a fix and flip with no ARV yet, some calculators require an ARV input. If you estimate the ARV wrong by even 10 percent, your profit projection becomes unreliable. Run sensitivity analysis instead. Plug in a low, medium, and high ARV and see where your break even point lands.
Another failure case is when you have multiple draws. Construction loans under hard money sometimes release funds in phases. The calculator assumes a lump sum at closing. If your lender releases 40 percent at close, 30 percent at framing, and 30 percent at drywall, your interest cost changes because you are not paying interest on the full amount from day one. You need to calculate interest on each draw separately and add them together.
Also, some calculators do not handle interest reserves. An interest reserve means the lender sets aside a portion of the loan to cover your monthly payments. The loan balance grows over time because you are not paying cash monthly. The effective cost is higher than what the calculator shows. On a $300,000 loan with a 6 month interest reserve at 12 percent, the extra cost is about $18,000 in capitalized interest. That dramatically changes your exit math.
A Practical Workaround for Common Pitfalls
The best approach I found is to use the calculator as a first pass and then build a spreadsheet for the final numbers. The spreadsheet lets you adjust for anything the calculator misses.
Start by entering the base loan terms into the calculator. Export or copy the results. Then build a simple table with columns for each month. In each row, track the outstanding balance, the interest accrued, any draws received, and the cumulative cost. Add rows for fees that the calculator omitted. This usually takes about 20 minutes and gives you a number you can actually trust.
Another tactic is to call two or three hard money lenders and ask for their exact fee schedules. Put those into your spreadsheet alongside the calculator estimates. The difference between estimated cost and actual cost from real lenders is usually within 5 to 10 percent if you include every fee. If it is more than that, the lender is being opaque and you should look elsewhere.
Key Formulas to Memorize
Loan amount equals ARV times LTV. Or purchase price plus repairs times LTV, depending on the lender.
Monthly interest payment equals loan amount times annual rate divided by 12.
Total points cost equals loan amount times points divided by 100.
Total interest over the loan term equals monthly payment times number of months, assuming interest only.
Effective annual rate accounts for points and fees. Divide total fees by loan amount, divide by the loan term in years, and add it to the stated rate. This gives you a truer picture of what the loan actually costs.
On a $200,000 loan at 12 percent with 2 points and a 1 percent origination fee over 12 months, the stated rate is 12 percent but the effective rate is closer to 15.5 percent. That difference matters when you are comparing two lenders side by side.
Download and Access
There is no single official hard money calculator. The term refers to a category of tools. You can find them on real estate investing websites, lender portals, and financial calculator sites. Many lenders embed their own calculator on their website as a lead generation tool. These are useful but they are biased toward that lender's specific terms.
For a more general purpose tool, look for open source calculators or build your own spreadsheet. A well constructed spreadsheet costs nothing and adapts to any lender's terms. You can share it with your team. You can update it when market conditions change. And you are not locked into one lender's pricing structure.
If you prefer a ready made solution, I recommend searching for hard money loan calculator on sites like BiggerPockets, Google Sheets template galleries, or lender comparison sites. Download one, test it against a known deal, and verify the numbers match your manual calculation. If they do not, either the calculator has a bug or you entered something wrong. Either way, do not trust it until you verify it.
Bottom Line
A hard money calculator is a useful first step. It gets you in the ballpark quickly. But ball park numbers are not enough when you are putting real capital at risk. Run the calculator. Then verify. Then build a more detailed model. The extra 30 minutes of work protects you from overpaying on a loan, underestimating costs, or missing a lender fee that quietly eats into your profit.
Gallery Hardmoney Calculator
Free Hard Money Loan Calculator — Costs & Payments 2026 | RealCalc
Free Online Hard Money Loan Calculator [2026 Private Lender Cost]
hard money loan calculator
Hard Money Loan Calculator: Estimate Costs Quickly & Accurately
Hard Money Loan Calculator: Payments, Points & ROI | David Roa