What a Hecm Calculator Actually Does (and Doesn't Do)
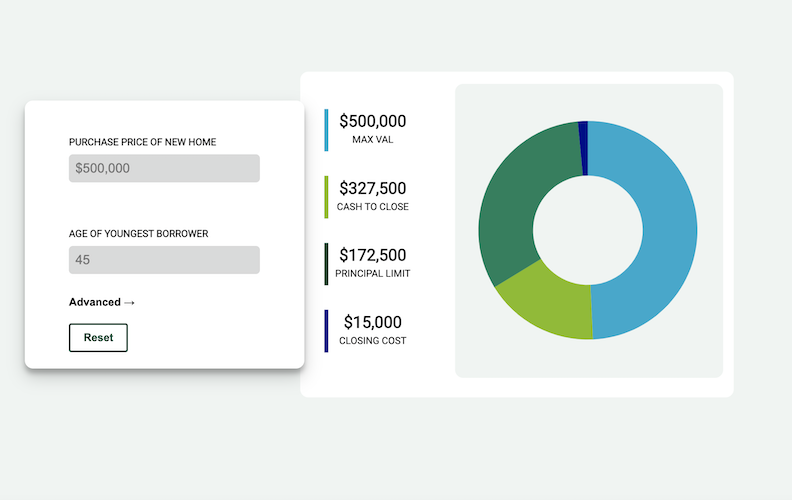
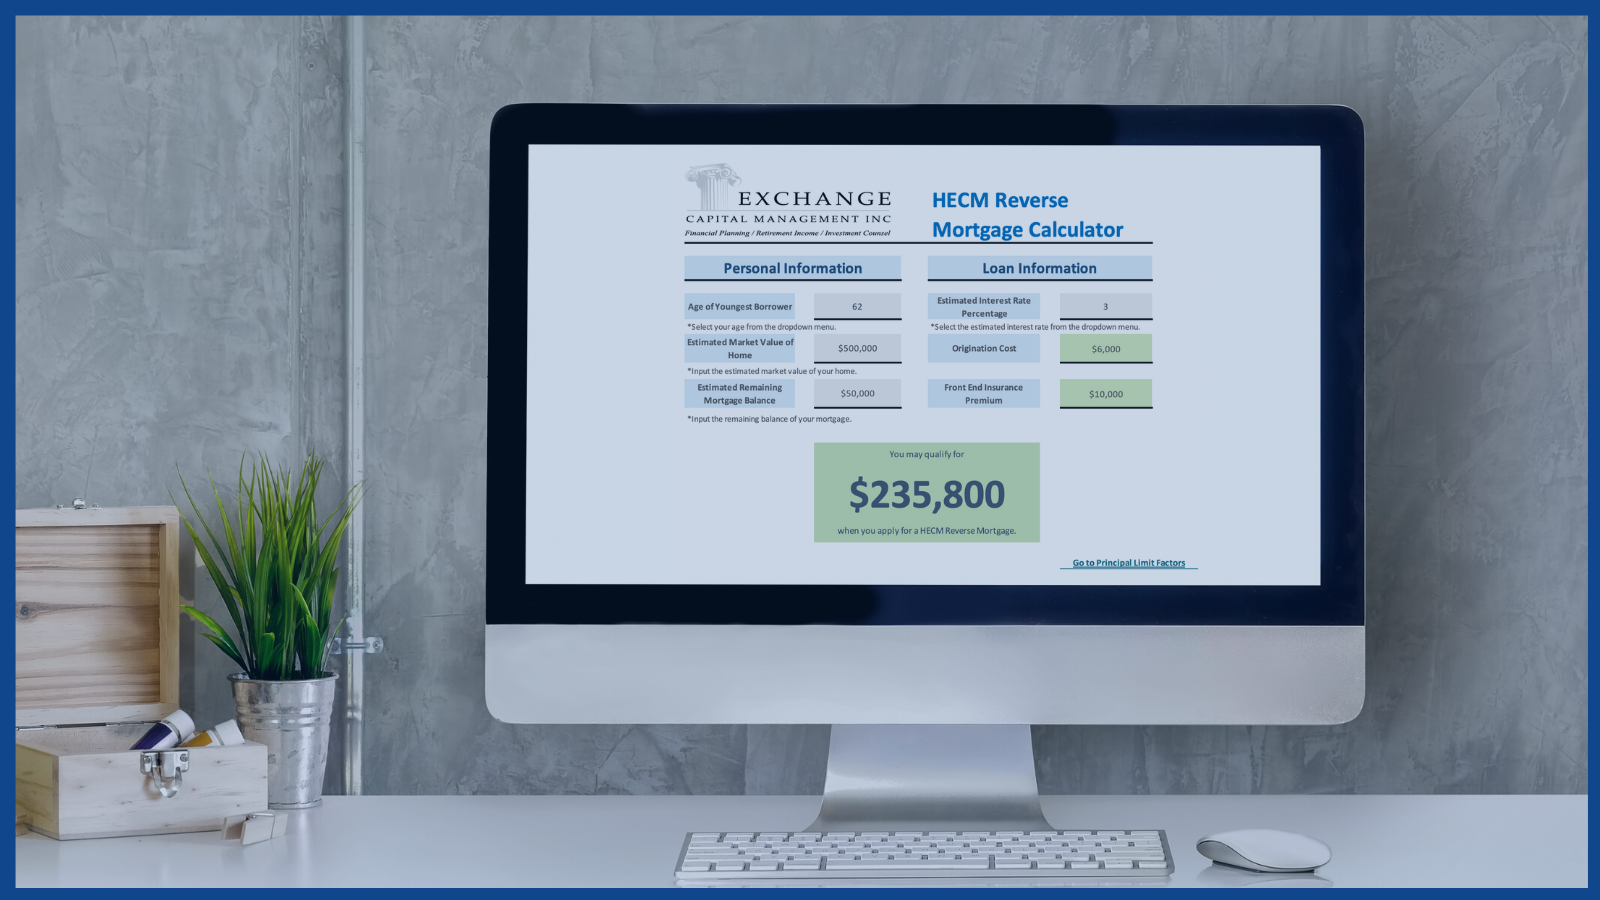
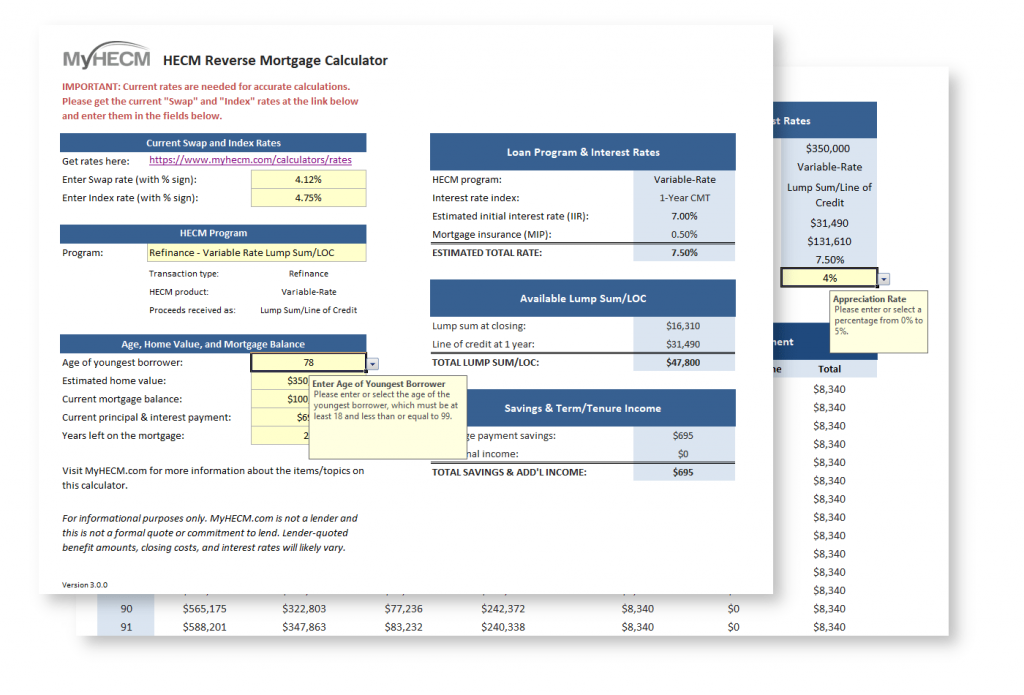
A reverse mortgage is a loan that lets homeowners age 62 and older convert home equity into cash without selling. The HECM, or Home Equity Conversion Mortgage, is the FHA-insured version and it makes up the vast majority of reverse mortgage originations. The calculator is just a numbers tool that estimates how much you could pull out based on your age, home value, and interest rates. That is the whole point of it. It does not decide if you qualify. It does not account for property taxes, insurance, HOA fees, or the fact that your home might need a roof next year. It spits out a rough number and hopes you look at the fine print. Pull up a reputable HECM calculator first. HUD's own Reverse Mortgage Calculator is free at hud.gov and it is accurate enough for initial planning. Most private lender sites have one too, but they are often slightly optimistic because they want your phone number. Enter your age, the current estimated value of your home, and any existing mortgage balance. The calculator will use the younger borrower's age as the determining factor even if you are married and your spouse is ten years younger. That detail matters a lot because age is the single biggest lever on your principal limit. The older you are, the more you can borrow, period. It is not a trick, it is just how the actuarial tables work. The result you get is called the Principal Limit. It is not a loan amount in the traditional sense because you are not being handed a lump sum and then paying it back with interest. You are accessing a line of credit that grows over time. The calculator shows you the maximum upfront amount, but the actual money you walk away with is lower after closing costs and the mortgage insurance premium are deducted. Expect to lose roughly 6 to 8 percent of your home value to those fees on a standard HECM. That is a hard number most calculators do not make obvious until page three of the disclosure documents.
I ran into this problem recently with a client whose home was worth $420,000 and who had no existing mortgage. The online Hecm Calculator showed her a potential draw of about $195,000. After closing costs, the upfront MIP, and the servicing fee, she walked away with roughly $161,000. The gap between the two numbers is where people get confused and sometimes sign paperwork thinking they know what they are getting. My workaround was simple: I ran the same numbers through HUD's calculator, then I pulled the Actual Cash Value column from the Closing Disclosure template and compared it to the advertised figure. The difference was never huge but it was always enough to shift the decision. If the numbers look too good, they usually are.
The Counter-Intuitive Stuff Nobody Tells You
First, the line of credit on a HECM grows at the same rate as the loan interest rate. This means if rates go up, your available credit goes up too, because the unused portion accumulates a gain. A lot of people think higher rates are bad for reverse mortgages across the board, but they actually increase the ceiling on future borrowing. That is a rare case where a rate hike helps the borrower. The catch is that your monthly payment obligation also increases because the accrued interest compounds faster. So it is a tradeoff, not a free lunch. Second, the age of your spouse matters enormously for estate planning. If you take out a HECM and your spouse is not on the loan, they have no legal right to stay in the home once you die. The loan becomes due. I have seen this cause real family disputes. The workaround is to have both spouses listed as non-borrowing spouses on the loan documents, which gives them occupancy rights even after the borrowing spouse passes. This does not change the numbers on the calculator at all, which is why it is easy to overlook. The Hecm Calculator will show you the same principal limit whether your spouse is listed or not, because the calculator does not track legal occupancy rights. It only tracks dollars. Another nuance is the hybrid HECM product. Some lenders offer a HECM with a fixed rate component and a variable line of credit. The fixed portion locks in a rate for the amount you draw upfront, while the variable portion floats. The calculator usually does not model hybrid structures well. You need to ask the lender to run a custom scenario if you are considering this option, because the standard output assumes a pure variable rate loan.
Get the Full Details
When a Hecm Calculator Is Not Useful
If your home is valued above the FHA lending limit for your county, the calculator will understate your borrowing power. The HECM program has a cap, and anything above that is handled through proprietary reverse mortgage products that use different formulas. A standard HECM calculator will not show you those numbers. You would need a separate tool or a lender who specializes in jumbo properties. Similarly, if you have significant outstanding debt beyond your primary mortgage, the calculator may not factor in the required set-asides for property charges. HUD requires lenders to reserve funds for taxes and insurance if the borrower's income is insufficient to cover them. This reduces your available proceeds, sometimes substantially, and most online calculators skip this entirely. If you are under 62, you cannot get a HECM at all. There is no workaround other than waiting or looking at other products like a HELOC or a cash-out refinance. No calculator will show you a HECM result for anyone under 62 because it is literally impossible. Don't bother inputting fake data hoping the system will adjust. It won't.
Where to Find a Working Hecm Calculator
The HUD Reverse Mortgage Calculator is free and does not require an email address. It runs in any browser and gives you a principal limit factor based on your age and the prevailing interest rate. The link is hud.gov/calculate. For a more detailed breakdown, NerdWallet and Bankrate both host Hecm Calculator tools that estimate monthly payments and total proceeds, though they add ads and contact forms you can ignore. If you want a downloadable spreadsheet for manual calculation, HUD publishes a Principal Limit Factor table on their site. It is not a calculator but it gives you every number you need to compute the loan yourself in about five minutes. The bottom line is that a Hecm Calculator is a starting point, not an answer. It gives you a ballpark figure. The real numbers come from the Closing Disclosure you receive after applying. Use the calculator to see if a reverse mortgage is even in the same neighborhood as what you need, then bring the results to a counselor or lender for the actual quote. HUD-approved counseling is free and required before you can close on a HECM, so use that session to validate whatever the calculator told you. Most people come out of it knowing exactly what they are signing, and that is the whole point.