What This Calculator Actually Does
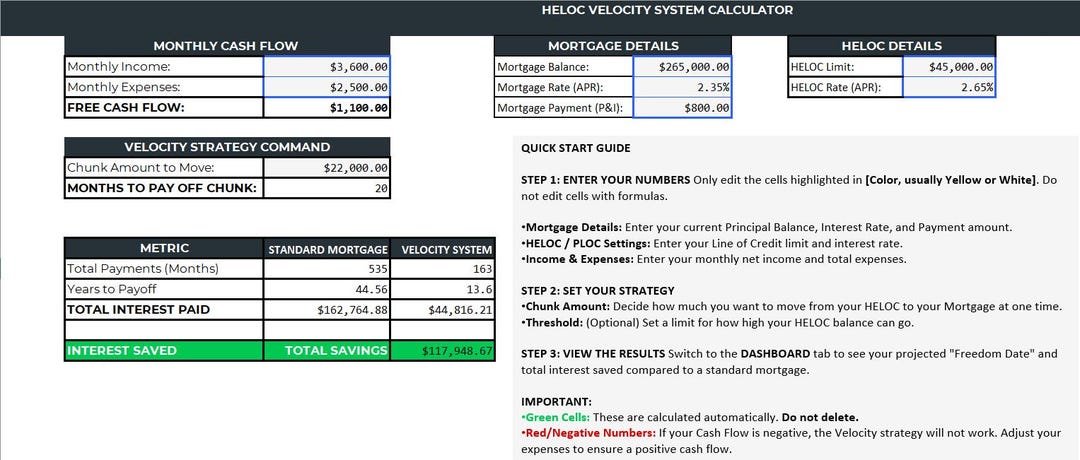
A Heloc Accelerated Mortgage Payoff Calculator is a tool that models what happens when you use a home equity line of credit to pay down your mortgage faster than the standard schedule allows. You plug in your mortgage balance, interest rate, remaining term, your HELOC rate and limit, and the tool runs projections showing how much time and interest you save, assuming you consistently funnel HELOC draws into mortgage principal payments. The process is straightforward, but most people get tripped up on the setup because they underestimate how much detail matters. Start by gathering your current mortgage statements. You need the original principal, current balance, interest rate, monthly payment amount, and remaining term in months. Then get your HELOC terms: approved credit limit, current draw balance, variable interest rate, and any minimum payment requirements. Enter these numbers into the calculator. Most tools ask for whether the HELOC rate is fixed or variable. If it's variable, you have two choices: enter the current rate and accept that the projection assumes it stays frozen, or attempt to model a rate scenario if the tool supports it. The payoff time and total interest savings will shift noticeably depending on which path you choose.
One thing I see constantly: people forget to factor in the draw period length. If your HELOC has a 10-year draw period and you're using it to make accelerated payments, the calculator needs to account for what happens after year 10 when the product converts to amortization mode and your monthly obligations change. A lot of free calculators completely ignore this. I built a workaround into my own spreadsheet where I extend the projection past the draw period and force-convert the remaining balance into a standard amortization schedule at the current HELOC rate. It adds about three minutes to the setup but saves you from making decisions on bad data.
The Mechanics Behind the Numbers
Here is how the math actually works under the hood. When you take money from your HELOC and apply it directly to your mortgage principal, you are reducing the outstanding balance on the first lien. This does two things simultaneously. First, it reduces the principal amount that accrues interest each month on your mortgage. Second, if your mortgage is structured with monthly compounding, a lower principal means less interest is generated in the very next billing cycle, creating a compounding effect in reverse. The calculator tracks this by running month-by-month simulations. It subtracts your extra principal payment from the mortgage balance, recalculates the interest portion of the regular monthly payment, and carries forward the reduced balance into the next month. Over time, the gap between your standard payoff date and your accelerated payoff date widens because each extra dollar paid early removes not just that dollar's worth of principal but every future interest charge that dollar would have generated. There is a nuance most people miss. The HELOC itself carries interest from the moment you draw. So you are comparing the interest rate on your mortgage against the interest rate on your HELOC plus the administrative friction of managing two payment streams. If your mortgage rate is 6.5 percent and your HELOC rate is 9.2 percent, the math only works in your favor if the accelerated payoff on the 6.5 percent debt generates enough interest savings to overcome the 9.2 percent cost of borrowing. That threshold calculation is what a proper calculator handles, but you need to understand what you are comparing before you trust the output.
Get the Full Details

When This Strategy Actually Works and When It Fails
The strategy works when your mortgage rate is meaningfully higher than your HELOC rate, and when you have consistent cash flow to keep feeding the HELOC. The gap between those two rates is your margin. A two percentage point gap is where most people see actual benefit. A half-point gap is not worth the hassle. Below that, you are paying more in HELOC interest than you save on mortgage interest, and the calculator will show negative returns if you run the numbers honestly. It also requires discipline. I had a client once who ran the projection and saw he could shave seven years off his mortgage. He drew aggressively from his HELOC, made accelerated payments for about fourteen months, and then stopped. The HELOC balance started climbing again while his mortgage balance barely moved because he was no longer funding it. The payoff timeline shifted backward. This is not unusual. The calculator shows a best-case scenario assuming consistent behavior, and consistent behavior is the hardest variable to control. Another scenario where this fails completely: when your HELOC has a balloon payment or renewal clause. Some HELOCs require the full balance to be paid at renewal even if you have been making interest-only payments. If you have been using the HELOC to accelerate mortgage payoff, you may wake up at renewal with a large lump sum due and no liquidity to cover it. I always advise checking the renewal terms before trusting any calculator output. The tool cannot account for contractual clauses you have not disclosed.
Key Variables That Change the Outcome
The size of the gap between your mortgage rate and HELOC rate matters, but the frequency and consistency of your draws matters more. A one-time $20,000 draw applied to principal produces a different result than $20,000 drawn incrementally over eighteen months. The calculator will reflect this difference, but only if you input the draw schedule accurately. Vague inputs produce vague outputs, and vague outputs are dangerous when real money is on the line. Tax treatment is another variable. Mortgage interest on a primary residence is sometimes deductible depending on your jurisdiction and loan structure. HELOC interest deductibility has become much more restricted in recent tax code changes. If your mortgage interest was previously deductible and your HELOC interest is not, the effective cost of the HELOC is higher than the stated rate. Adjust your comparison accordingly before running the numbers. A 7.8 percent HELOC rate with no tax benefit is roughly equivalent to a 6.5 percent mortgage rate with full deductibility for someone in a 24 percent marginal tax bracket. The calculator does not know your tax situation. You do.
A Practical Example
Take a borrower with a $320,000 mortgage at 6.75 percent remaining on a 30-year term. They have a HELOC with a $80,000 limit at 8.9 percent variable rate. They decide to draw $15,000 per quarter and apply it directly to the mortgage principal. The calculator projects a payoff date roughly 4.2 years earlier than the standard schedule, with total interest savings of approximately $41,000 over the life of the loan. However, those savings assume the HELOC rate stays at 8.9 percent. If rates climb to 10.5 percent during the payoff period, the interest cost on the HELOC side increases enough that the net savings drop to around $22,000, and the time savings shrink to about 2.8 years. This is why I always run at least two scenarios: one with the current HELOC rate held constant, and one with a rate increase of 1.5 to 2 percentage points. The second scenario is usually the more useful decision point because it reveals whether the strategy survives real-world conditions rather than just ideal ones.

Limitations You Need to Accept
No calculator can predict when your job income changes, when your HELOC is called, when your property value drops below the lender's threshold, or when prepayment penalties kick in. If your mortgage has a prepayment penalty clause, the calculator output is invalid until you factor that cost in. Some lenders charge penalties equal to three to six months of interest if you pay down principal above a certain threshold within the first few years of the loan. That can erase the entire projected saving in a single transaction. Another limitation is that calculators typically assume your regular mortgage payment continues unchanged during the acceleration phase. In reality, some servicers will recast the loan when they see a significantly lower balance, which changes your monthly payment amount and alters the amortization timeline. If your servicer does this, you need to adjust the calculator inputs manually to reflect the new payment, or the results will drift from reality. If you are looking for a standalone tool, you can search for the Heloc Accelerated Mortgage Payoff Calculator by name online, but I would strongly recommend building your own version in a spreadsheet. The freedom to layer in draw schedules, rate scenarios, tax adjustments, and prepayment penalty checks gives you far more control than any generic web tool. I keep a template I built years ago that I update whenever the rules change. It takes about ten minutes to set up a full scenario and maybe five minutes to run alternative rate assumptions. That investment pays for itself immediately.