How to Actually Use a HELOC Calculator Without Wasting Afternoon
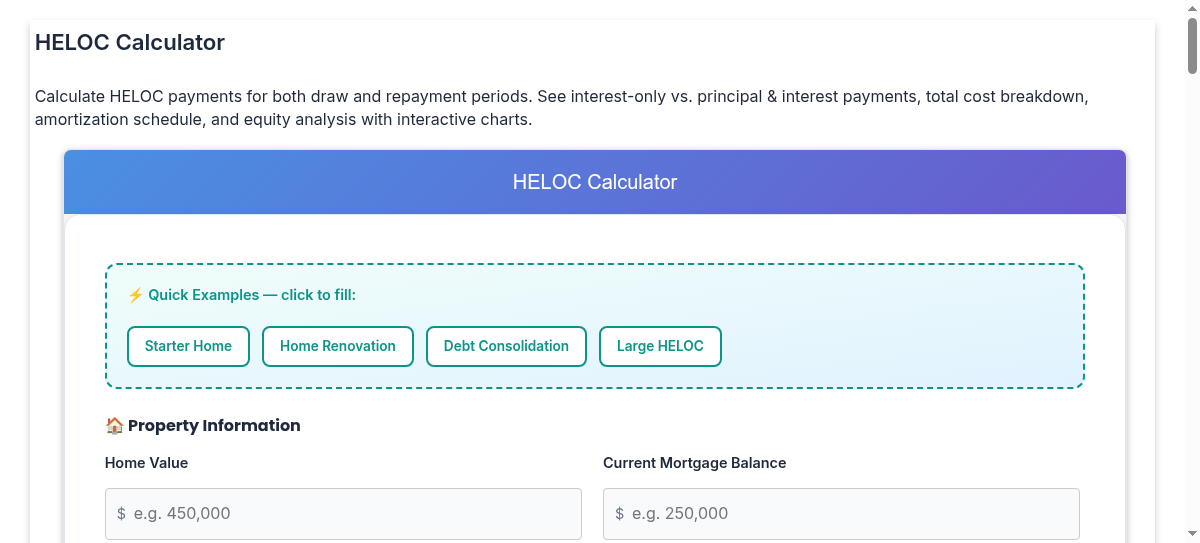
Most people pull up a HELOC calculator and punch in their home equity, monthly income, and debt payments. The results look clean. They are not. A calculator gives you numbers based on assumptions that rarely match your actual situation. I have spent years watching homeowners get tripped up by the gap between what a tool shows and what the bank actually approves. The core issue is that a HELOC calculator typically works with three inputs: your home's appraised value, your current mortgage balance, and your total monthly debt obligations. From there it applies a standard debt-to-income ratio formula. Most calculators assume lenders cap your DTI at 43 percent or 50 percent. Some go higher. The exact threshold depends on the lender, the loan program, and whether you have good credit. None of that nuance shows up in the output.
How a Heloc Calculator Actually Calculates Your Borrowing Power
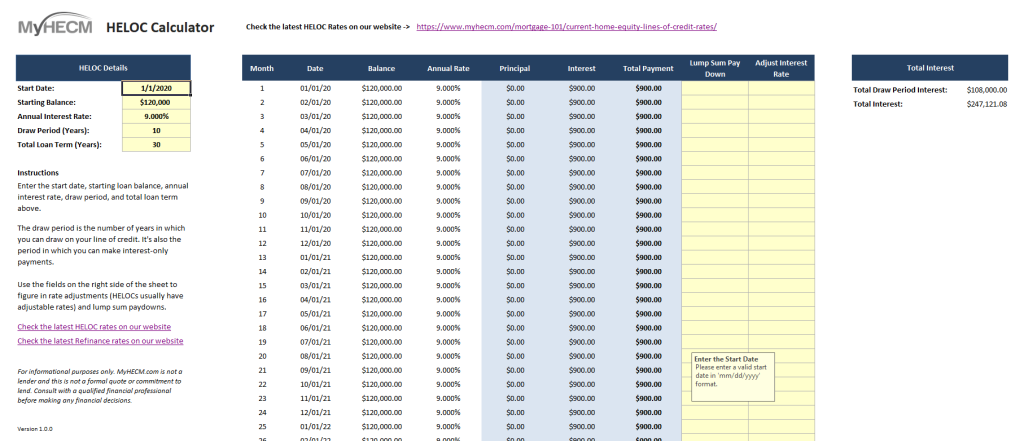
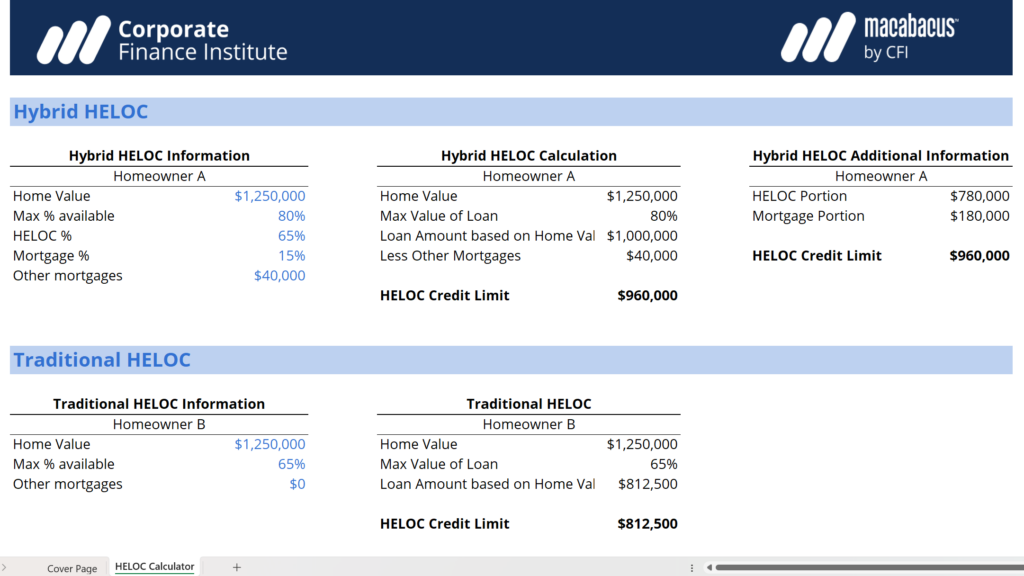
Here is what most calculators are doing under the hood. They take your home value, multiply it by the lender's maximum loan-to-value ratio, which usually sits between 80 and 90 percent for a HELOC, and then subtract your existing mortgage balance and any other qualifying debts. The remainder is your available credit line. Simple on paper. Messy in practice. The first thing most people miss is that the calculator does not account for the draw period versus the repayment period. Your monthly payment during the draw phase is interest only on whatever you borrow. Then it suddenly jumps when you enter repayment. A $30,000 HELOC at 8 percent over ten years of interest-only payments looks tiny monthly. The repayment phase on that same amount could nearly double your payment. The calculator will rarely show you that transition clearly unless you dig into the fine print. Another hidden variable is the pricing tier. Lenders often quote a prime-rate-based index plus a margin. Right now that spread might be prime plus 0.5 to 1.5 percent depending on your credit score. A calculator might use a single fixed rate for simplicity, which can throw off your payment estimate by several hundred dollars a month over the life of the loan.
I ran into this last year when a client was trying to compare two lenders. One calculator showed a lower rate but used a flat 7 percent assumption across the entire term. The other showed a variable rate that started slightly higher but had a much better margin structure. Over five years the second option saved him roughly $4,200 in interest because his balance stayed elevated longer than either estimate assumed. He would have picked the wrong product if he only looked at the upfront rate display. There is also the matter of the combined loan-to-value ratio and how second-lien positions affect approval odds. Some lenders will let you combine a first mortgage and a HELOC up to 90 percent of your home value. Others stick to 85 percent for the second lien. This changes your available borrowing capacity significantly and most basic calculators do not ask about it. If you want something more realistic, start by pulling your actual closing disclosure from your mortgage paperwork. Note the remaining principal, the interest rate, and your payment. Then run the numbers through a tool that lets you input variable rates and draw-period terms. The better calculators break the payment into two phases and let you adjust the LTV and DTI assumptions per lender guidelines. That kind of flexibility cuts the guesswork down from hours of back-and-forth with loan officers to maybe twenty minutes of your own research.
Get the Full Details
One final reality check. A HELOC calculator result is an estimate, not an approval. Underwriters review credit score, employment history, reserve requirements, and sometimes even the purpose of the funds. A calculator cannot factor in any of that. If the number looks great but your credit dropped forty points since you paid off that car, the actual approved amount could be substantially lower than the tool projected. Run the numbers, then call three lenders and ask for a pre-qualification rather than treating the output as gospel.