Understanding How HELOC Monthly Payments Actually Work
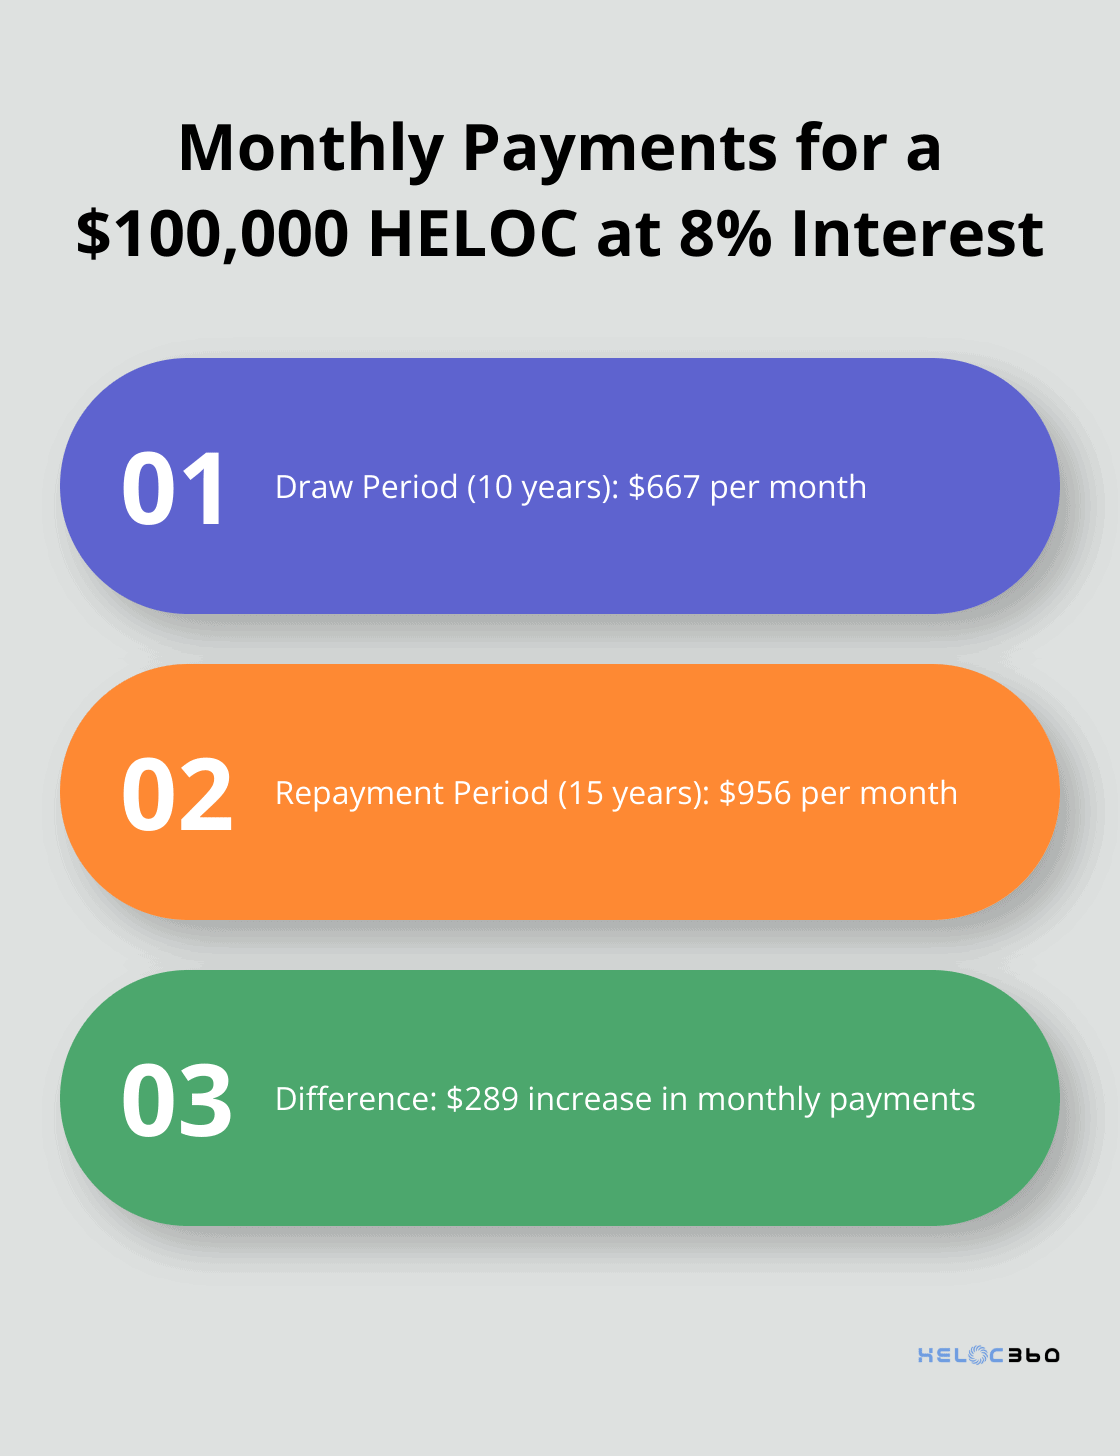
Most people opening a home equity line of credit assume their monthly payment will stay flat. It doesn't. The structure is split into two distinct phases, and your payment changes dramatically between them. During the draw period, which typically lasts 5 to 10 years, you are usually only required to pay interest on whatever balance you have actually pulled out. After that window closes, the repayment period begins and you are paying both principal and interest on the remaining balance over a set timeline, often another 10 to 20 years. A Heloc Calculator Monthly Payment tool attempts to bridge that gap by running the numbers for you, but the output is only as reliable as the inputs you feed into it. That sounds obvious until you realize most free online calculators default to a 7.5% interest rate and a $50,000 draw amount without telling you why. If your actual rate is 9% and your draw is $35,000, the payment estimate could be off by nearly 40%, which is the difference between budgeting comfortably and stretching thin.
Calculating Your Draw Period Payment
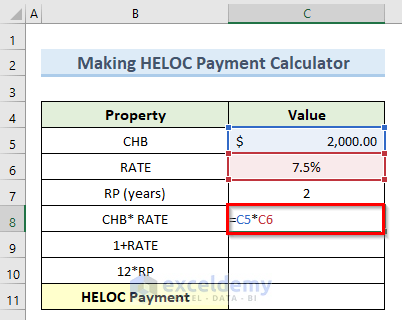
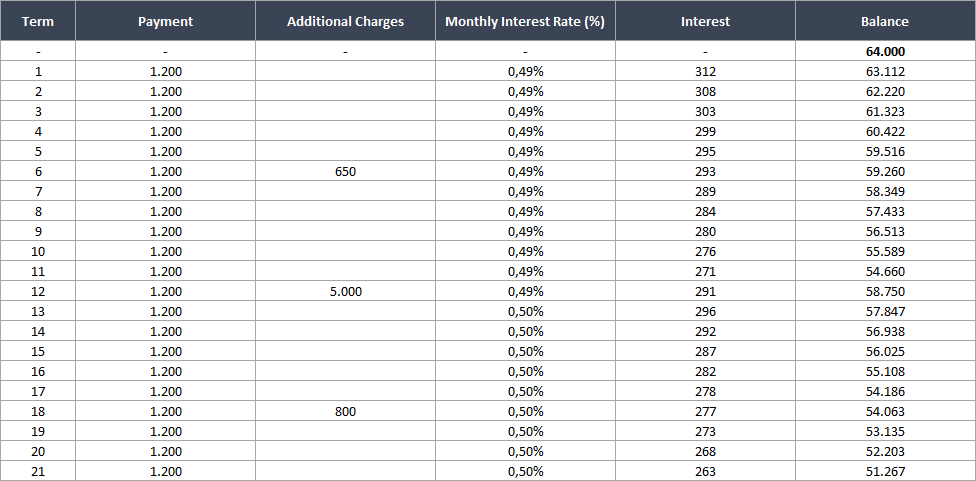
The draw period payment is straightforward if your lender is being transparent. You multiply your outstanding balance by your annual percentage rate, then divide by 12 to get the monthly figure. On a $40,000 balance at 8.25% annual rate, your interest-only payment comes to about $275 per month. Simple. The problem is that most HELOC agreements include a minimum monthly payment that is higher than the pure interest calculation. Some lenders require you to pay at least $50 or $100 per month regardless of how little you have drawn. Others structure the minimum around a percentage of your total available credit rather than your actual balance. I learned this the hard way when a client in Colorado refinanced out of a rental property using a HELOC and ran the numbers through a widely used free calculator. The tool showed a $290 monthly payment based on a $42,000 balance at 7.9%. When the first bill arrived, it was $415. The difference came from a clause in the closing documents that required a minimum payment of 1.5% of the outstanding balance, not just the interest. The calculator had no field for that variable because most lenders do not disclose it prominently on their application pages. I had to pull the original promissory note and find the minimum payment schedule buried in section four, paragraph two. The workaround was simple enough once I found it: I built a spreadsheet that mirrored the lender's exact terms, including the minimum payment floor, and ran my own Heloc Calculator Monthly Payment logic there instead of relying on the free tool. It took about twenty minutes to set up and saved us from a budget gap that would have caught us off guard by roughly $125 a month.
What Happens When the Repayment Period Starts
This is where people get caught. During the draw period you are paying interest only. Then the clock runs out and suddenly you are responsible for paying down the entire remaining balance over a shorter timeframe. Using the same $40,000 example at 8.25% over a standard 20-year repayment term, your new monthly payment jumps to approximately $341. That is not a gradual increase. It is a step function, and it happens with very little warning depending on how your lender structures the transition notice. Some lenders give you a 60-day grace period before the first principal-and-interest payment hits. Others start the amortization immediately. A few offer a conversion option where you lock in a fixed-rate home equity loan for the outstanding balance before the draw period ends, which stabilizes the payment but usually comes with a higher rate than your variable HELOC. I have seen borrowers miss this window because they assumed the payment would ease into the new structure. It does not. The first payment on the new schedule arrives and it is already fully amortized.
Get the Full Details
Common Pitfalls With HELOC Calculators
The biggest issue with most free Heloc Calculator Monthly Payment tools is that they treat interest rates as static. HELOC rates are variable, which means they adjust periodically based on an index like the prime rate plus a margin. If your margin is 3.75% and the prime rate moves from 8.5% to 9.25%, your effective rate goes from 12.25% to 13%. A calculator that gives you a single fixed rate will not show you what happens if rates tick up, and in a rising rate environment your payment can increase substantially without any change to your balance. Another pitfall is the assumption that your draw will happen all at once. Most calculators let you input a single lump sum. In practice, people tend to draw in stages, and each additional dollar adds to your interest accrual. A contractor pulling funds for a renovation project might take out $10,000 in month one, another $15,000 in month three, and $8,000 in month six. A calculator that assumes a flat $33,000 balance from day one will understate your actual payment during the earlier months because you did not have the full balance drawn yet. The cumulative effect on your total interest paid over the life of the line is significant. I track this by building a month-by-month schedule in Excel that records each draw date and recalculates the payment after every transaction. It is more work upfront, but it takes about ten minutes per project and prevents surprises later. There is also the issue of fees that calculators ignore entirely. Some HELOCs carry an annual maintenance fee, an origination charge, or a quarterly account service fee. These do not show up in the payment calculation but they affect your real cost of borrowing. A $75 annual fee on top of a $290 monthly payment is a 3.1% added cost that no standard calculator will flag.
When to Build Your Own Spreadsheet Instead
If your situation involves multiple draws, a variable rate, or a minimum payment structure that deviates from the standard formula, the free calculators will not give you accurate enough numbers for financial planning. I build a custom model for clients in those scenarios, and it typically takes about fifteen minutes once you have the template ready. You need the current outstanding balance, the annual rate, the number of months remaining in the draw period, the length of the repayment period, and the lender's minimum payment rule. With those inputs you can project both the draw-phase payment and the repayment-phase payment, factor in rate adjustments by using a range of possible prime rate movements, and see the total cost of the line over its full life. There is a reason professional advisors do not rely solely on online tools. The free calculators exist because they are easy to deploy and they generate traffic. They are not designed for precision. If you are using a HELOC as a short-term funding mechanism for a renovation or a debt consolidation play, a rough estimate might be acceptable. If you are carrying a six-figure balance on it for multiple years, the gaps in those calculators become expensive.
Key Variables That Actually Move Your Payment
Your drawn balance is the most obvious factor, but it is not the only one. Your rate margin matters. If two lenders offer the same teaser rate but one charges a 4% margin and the other charges a 3% margin, the one with the lower margin will cost you less over time as the index fluctuates. The draw schedule matters too, because each additional dollar you pull increases your interest accrual immediately. The length of the draw period affects your cash flow, since a longer draw period keeps your payments lower for longer but extends the time you spend paying interest without building equity. And the repayment term length is critical because a longer repayment period lowers your monthly obligation during that phase but increases your total interest cost significantly over the life of the loan. I recently worked with someone who had a $60,000 HELOC balance and was looking at a repayment period extension. The lender offered to move her from a 15-year repayment to a 20-year repayment. The monthly payment dropped from about $570 to $460. The total interest over the life of the loan increased by roughly $14,000. The decision was not trivial. It came down to whether she needed the monthly breathing room more than she cared about the additional interest cost. A standard calculator would show both numbers, but it would not tell you which tradeoff makes sense for your specific situation. That part requires understanding your cash flow constraints and your long-term plans for the property. The practical takeaway is that a Heloc Calculator Monthly Payment tool can give you a starting point, but it will not replace understanding the terms of your actual agreement. Read the promissory note. Check the minimum payment clause. Verify the rate adjustment schedule. Build a simple spreadsheet if the standard tools leave out variables that matter for your case. The fifteen minutes you spend setting that up will save you from making a financial decision based on numbers that look right but are not accurate enough for real life.