Understanding How a HELOC Calculator Actually Works for Utah Borrowers
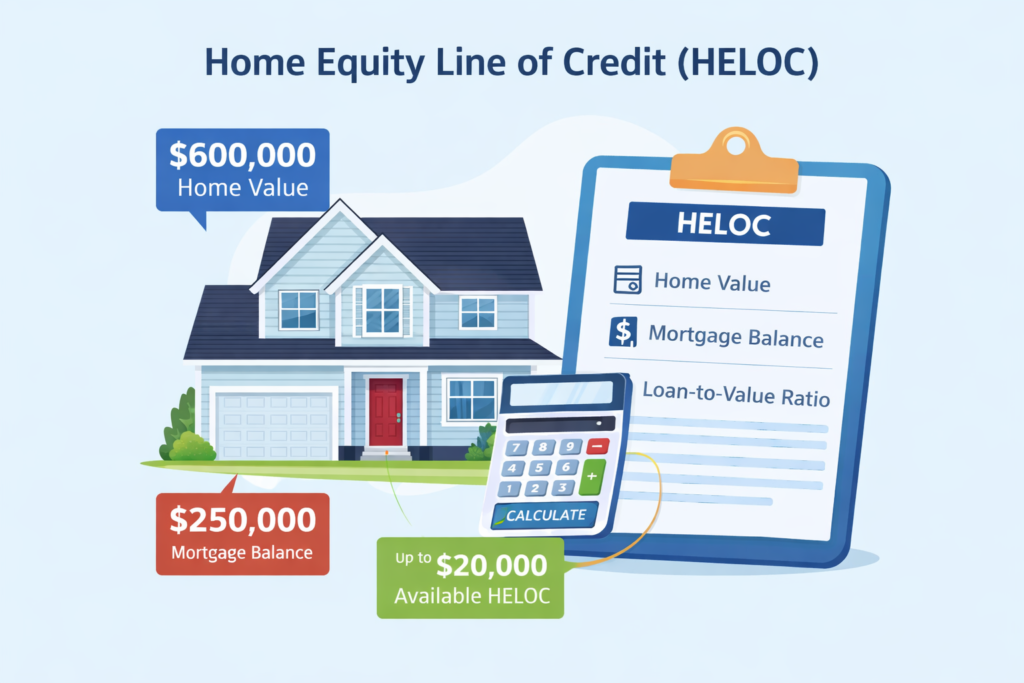
A HELOC calculator is a tool that estimates your monthly payments, available credit, and total interest costs for a home equity line of credit. Most online calculators give you rough numbers, but the ones tailored to Utah lenders account for state-specific closing cost ranges, lien tracking fees, and the rate environment that's been active here since 2023. That last part matters more than people realize. I ran into a specific problem last year when a borrower was trying to compare quotes from three Utah banks. The calculators they found online all showed nearly identical monthly payments, but the actual costs diverged by over $4,000 across the life of the loan. The issue was that none of those generic tools accounted for Utah's recording fees at the county recorder's office, which vary between Salt Lake County, Utah County, and Weber County. Some counties charge per page, some per instrument, and the differences add up quickly when you're looking at first-lien positions.
Heloc Calculator Utah: What to Look For and What to Avoid
When you use a Heloc Calculator Utah tool, the most important inputs are your current home value, existing mortgage balance, and the interest rate the lender is offering. But the inputs most people skip are the ones that change the math significantly. Take the draw period length. A lot of calculators default to a 10-year draw period with a 20-year repayment, but Utah lenders increasingly offer 15-year draw periods with shorter amortization schedules. The payment difference is substantial, and generic calculators won't show it unless you adjust those fields manually. Here's something most online calculators won't tell you: the initial teaser rate on a HELOC in Utah is almost never the rate you'll pay for long. The index plus margin structure means your rate floats. If you're using a calculator to compare offers, make sure it's showing you payments at a rate that's at least 1-2% above the advertised intro rate. I've seen people get surprised when their payment doubled after the first year because they only modeled the first six months of pricing. The calculator is only as good as the assumptions you put into it. Another thing that catches people off guard is the way Utah lenders handle partial draws. If you're planning to pull funds in stages rather than all at once, the calculator needs to reflect the declining available credit and the fact that interest accrues on what you actually draw, not on your total credit limit. A lot of basic calculators assume you draw the full amount immediately, which makes the numbers look worse than they would be if you were using it strategically over time. My workaround was to run two scenarios side by side: one with full draw and one with staggered draws at 25 percent increments each year. The difference in total interest paid over the life of the loan was enough to change which lender they chose.
Closing costs in Utah typically range from $2,000 to $3,500 for a HELOC, depending on the lender and county. Some lenders waive certain fees to compete, but you should verify what's actually included rather than taking the no-closing-cost label at face value. I had a client who thought they were getting a free HELOC, then discovered the rate was 0.75% higher to compensate. The calculator comparison looked favorable on the monthly payment, but the effective annual percentage rate told a different story. The other counter-intuitive thing is that a higher loan-to-value ratio doesn't always mean a worse rate on a HELOC in Utah. Because HELOCs are second-lien positions, some lenders price them competitively to fill out their home equity portfolios. You might find a lender offering a lower rate on an 85% combined LTV HELOC than another lender offers on a 75% LTV product, simply because one lender has more capital to deploy in the Utah market at that moment. Rate sheets here shift quarterly, so the calculator you use should ideally pull from current lender data rather than relying on national averages. There are also scenarios where a HELOC calculator simply won't give you useful numbers. If your credit score is below 620, if you have non-traditional income verification, or if the property is a manufactured home or condominium in an HOA with litigation issues, the calculator outputs are meaningless. The tool can't factor in manual underwriting adjustments, and Utah lenders do that more than the national average. In those cases, the best approach is to get a pre-qualification letter directly from a local lender rather than relying on any online estimate.
Get the Full Details
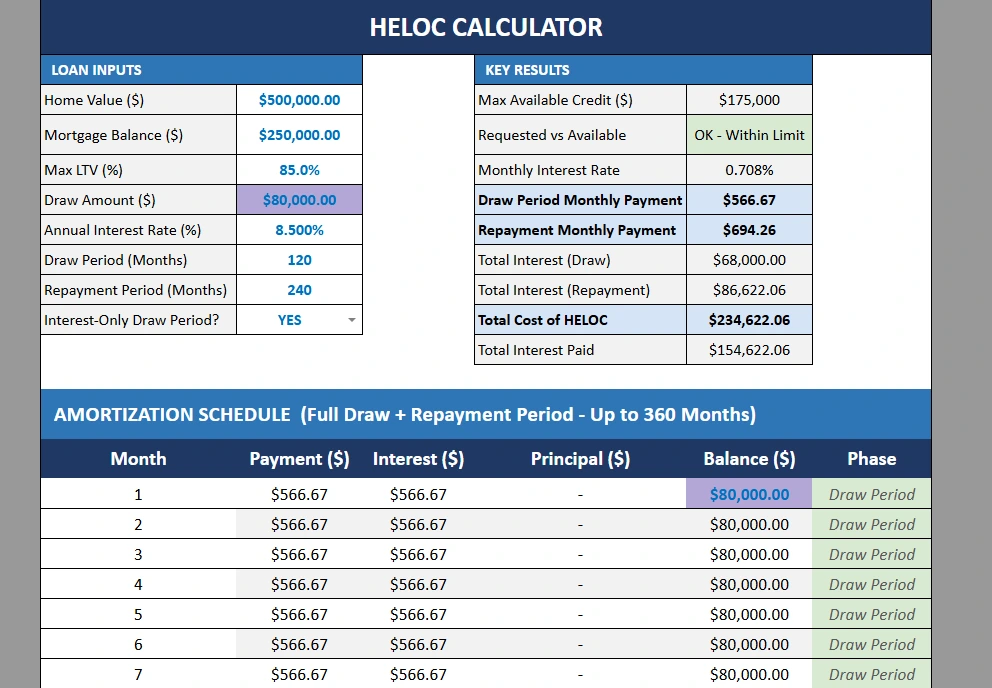
If you want a practical way to run these calculations yourself, the simplest method is to use a spreadsheet with the standard amortization formula built in. You can replicate most calculator functions with fewer assumptions baked in, and you can adjust the Utah-specific variables like recording fees and title insurance estimates without fighting a preset interface. The time investment is about 20 minutes to set up, and then you can run comparisons between any number of rate scenarios in seconds. I've been doing this for a while now, and I haven't found a commercial calculator that handles the Utah market nuances better than a well-configured spreadsheet. The bottom line is that a calculator is a starting point, not a decision tool. The numbers it produces are only as reliable as the input data, and the Utah lending environment has enough local variation that generic national calculators will mislead you more often than they help. Run the numbers, but verify them against actual lender disclosures before you commit to anything.