How HELOC Estimates Actually Work
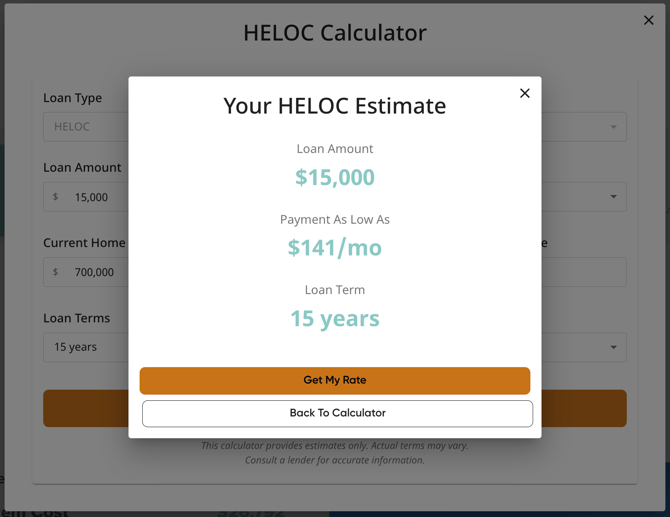
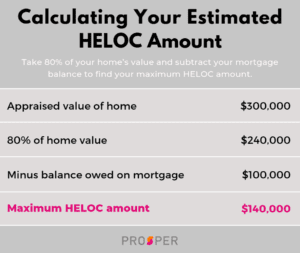
A Heloc Estimate is your rough calculation of how much borrowing capacity you have once a home equity line of account is factored in. Lenders look at your home value, existing mortgage balance, and the allowable loan-to-value ratio, then subtract your current debt from the maximum they'd lend to come up with a number. It is not the final approval amount, but it is the starting point for any conversation with a credit union or bank. The formula itself is straightforward enough that you can do it in a spreadsheet in about two minutes. Take your home's current market value, multiply it by the lender's maximum combined loan-to-value percentage, subtract your remaining mortgage principal and any other secured liens, and what remains is your approximate available credit. Different lenders cap that combined LTV somewhere between 80% and 95%, and the exact threshold matters more than most people realize because it directly determines whether you get a decent limit or a disappointingly small one.
Heloc Estimate Calculation Method
Here is the way I run this when a borrower brings me a property file. I grab a recent Comparative Market Analysis from the local MLS or pull an automated valuation from a service like ATTOM, then I take the median price range instead of any single listed listing because those are almost always inflated. I multiply that value by 85% as a conservative LTV ceiling, subtract the current payoff balance from the first mortgage, subtract any second mortgage or home equity loan already on the books, and arrive at the estimate. That number is typically within 5 to 10% of what the underwriter will ultimately approve, assuming the appraisal does not swing wildly in either direction. The tricky part is not the math. It is understanding what each input actually represents and how it behaves under stress. For example, if you own a condo in a market where prices have been volatile, an outdated automated valuation model can easily misprice the property by 8 to 12%, which makes your Heloc Estimate wildly inaccurate before anyone even pulls credit. I learned this the hard way when I worked a refinance on a property in suburban Phoenix where the AVM had the home valued at $420,000, but the actual appraised value came in at $387,000 six weeks later. My initial Heloc Estimate had been sitting at roughly $68,000 in available credit based on that inflated number, and once the appraisal landed, it dropped to about $31,000. I had to rework the entire payment schedule and explain to the borrower why his budget assumption was off by more than half. The workaround in that situation was to order a drive-by or exterior-only appraisal before presenting any numbers to the client. It costs around $150 to $200, but it prevents the kind of embarrassment where you commit a borrower to a spending plan based on a figure that has no basis in reality. Most people skip this step because they want an answer today, and I get that impulse. But a Heloc Estimate built on stale data is just an educated guess, and educated guesses cost more in the long run when they are wrong.
Another thing beginners consistently miss is the impact of existing HELOCs already open on the same property. If a borrower already has a $30,000 line of account with a $20,000 outstanding balance, some lenders treat the full committed line as an encumbrance rather than just the drawn balance. This can shrink your apparent available credit dramatically even though the monthly payment seems manageable. I have seen borrowers look at an estimate that showed $45,000 in room to borrow, only to discover during underwriting that the existing open line of account was counted at its full commitment amount, leaving them with only $8,000 or so in true headroom. The solution is to ask the lender upfront whether they use the committed amount or the outstanding balance when calculating combined loan-to-value ratios, and then recalculate accordingly before you ever submit an application. Rate environment also distorts these estimates in ways that are not immediately obvious. When rates spike, the debt-service-to-income calculation used during approval becomes tighter, and the approved credit limit may be lower than your Heloc Estimate suggested purely because the monthly carrying cost on the maximum available draw exceeds what the lender will allow your income to support. I ran into this last year with a borrower who qualified for a $120,000 line based on the property collateral alone, but his estimated monthly payment on that full amount at then-current rates would have exceeded his allowed DTI by nearly four percentage points. The lender reduced his approved limit to $62,000. The collateral supported the higher number. His income did not. If you want a more reliable ballpark without going through the full pre-approval process, the fastest route is still a manual calculation using your most recent closing statement, a current price estimate from a source you trust, and a lender's published maximum LTV table. You can usually find that table on the institution's website, though not all of them publish it clearly. Some will tell you the cap only during the application phase, which is frustrating if you are shopping around for the right product.
Get the Full Details
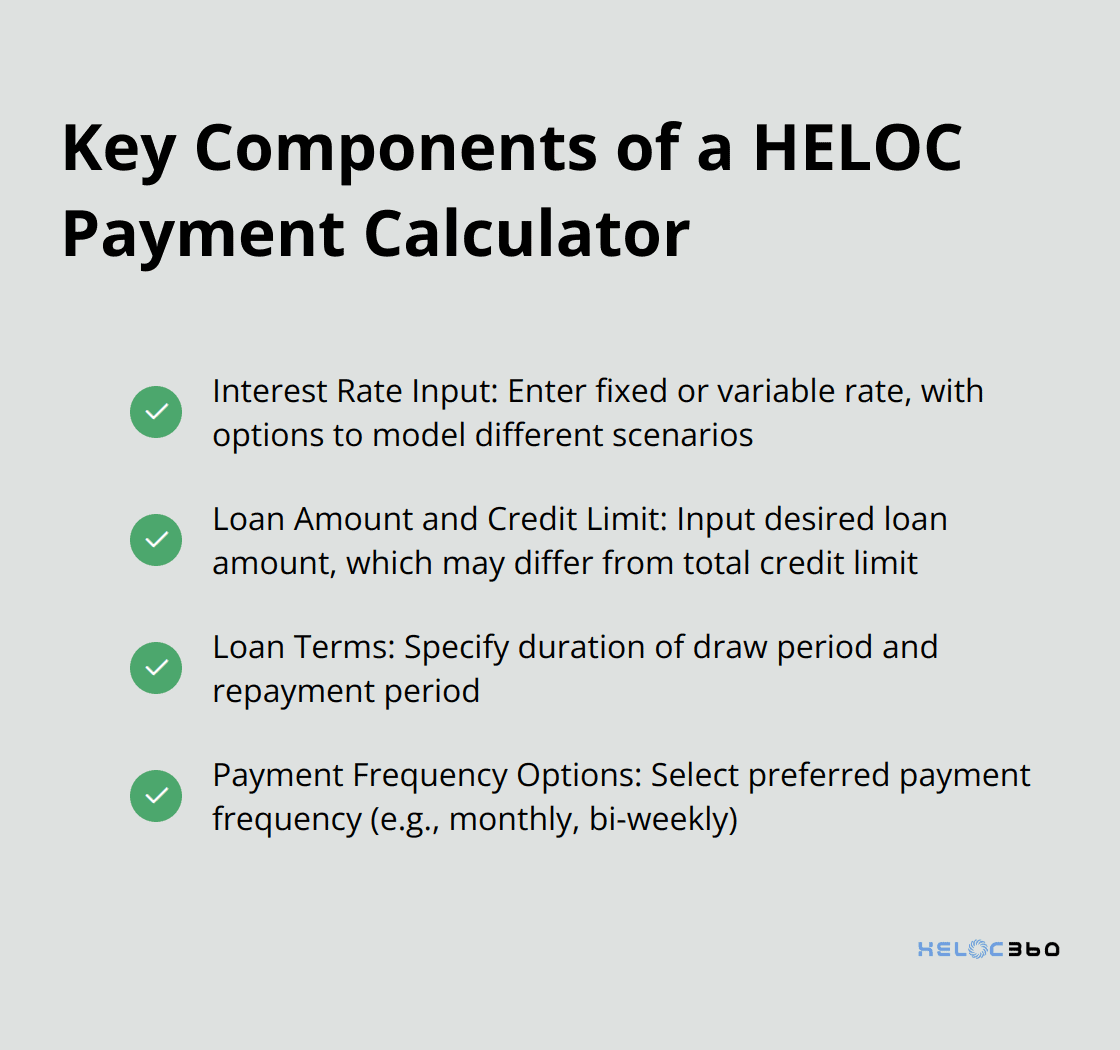
For a quick reference tool, I generally recommend running the numbers yourself rather than relying on online calculators, since many of those sites use default assumptions that do not match your actual lender terms. A simple Google Sheet or Excel workbook with cells for property value, mortgage balance, existing liens, and your target LTV will give you control over every variable and let you adjust each input without being forced into someone else's default parameters. I keep a copy saved with standard columns for each scenario I encounter, and it usually takes me less than three minutes to generate a rough Heloc Estimate for a new property.