HELOC Calculations Are Not as Simple as You Think
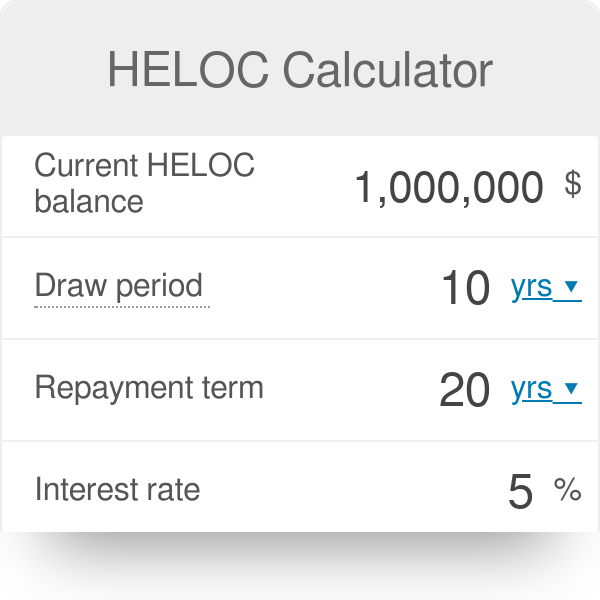
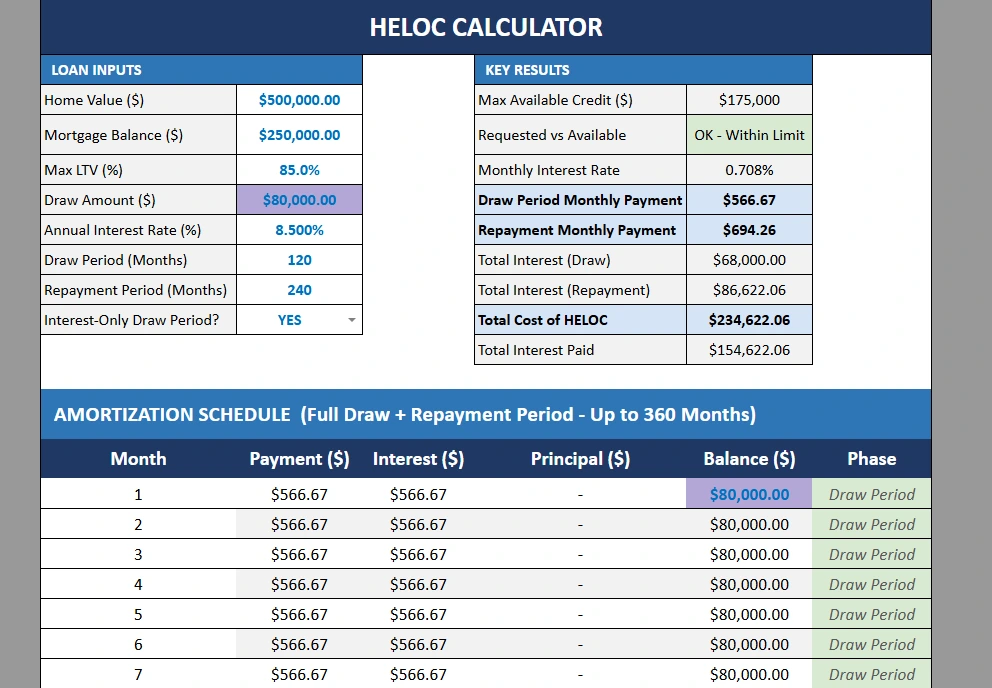
A HELOC estimator is a calculator that takes your home value, outstanding mortgage balance, and the lender's combined loan-to-value ratio to give you a rough number for how much credit you could access. That is the basic version. The real version involves understanding draw periods, interest-only phases, and the fact that most people who rely on the free online calculators end up surprised by the final approval number. Here is the straightforward process. You plug in your home's current market value, whatever you owe on your primary mortgage, any other liens like a second mortgage or home equity loan, and sometimes your credit score range. The tool applies the lender's maximum CLTV ratio, which is typically 85% to 90% for most jumbo lenders, and subtracts your existing debt. The difference is your estimated available credit line. For example, if your house is worth $400,000 and you owe $250,000 on your first mortgage, a lender with an 85% CLTV limit would allow total debt of $340,000. That means $90,000 in available HELOC capacity before you even factor in rates or fees. The math is simple. The execution is not.
The problem starts when you actually apply. I worked with a client last year who used a popular free estimator and got a number in the $85,000 range. He walked into the bank confident. They approved him for $62,000. The gap came from two things he had not accounted for. First, the bank appraised his home at $375,000 instead of the $400,000 he assumed, which was based on an old Zillow estimate and some rough comps he found online. Second, he had a recorded mechanic's lien from a kitchen renovation that never got properly released, which showed up on his title search and ate into his CLTV calculation. The estimator tool had no way to know about either of those.
Where Most People Mess This Up
The biggest mistake is treating the estimator output as a guarantee. It is not. It is a screen-level approximation based on the numbers you fed into it, and those numbers are usually optimistic. Zillow estimates run 5% to 10% high in many markets. Your "known" mortgage balance might be slightly different because of prepayment credits or escrow shortfalls the bank factors in differently. And your credit score at application time could be a few points lower than what you assumed when running the calculator. Another thing nobody tells you about these tools: they rarely account for the debt-to-income ratio impact. Some lenders will reduce your HELOC amount if your DTI is already high, even if you have plenty of equity. The estimator does not know your monthly debt payments unless you type them in, and most people skip that field because the calculator does not make it obviously required. There is also the matter of the draw period rate versus the repayment period rate. A HELOC estimator might show you the current promotional rate, which could be 0.5% to 1% below what your actual rate will be after the initial period. That changes your monthly payment estimate significantly, and most free tools either hide this or do not show it clearly enough.
Get the Full Details

What You Should Do Instead
Run the free estimator to get a ballpark. Then go get a pre-approval letter from one or two actual lenders. A pre-approval does not lock you in, but it gives you a real number based on your actual credit report, the bank's appraisal, and their current underwriting guidelines. This process usually takes 20 to 40 minutes and eliminates about 80% of the surprises that come later. If you are using a software-based HELOC estimator for your business, whether you are a loan officer or a financial planner, I would recommend building in a conservative buffer of 10% to 15% below whatever the tool shows. That accounts for appraisal variance, unreported liens, and the occasional lender who tightens their CLTV policy without updating their marketing materials. It also saves you from having that awkward conversation with a client three weeks into the process when the numbers no longer work. One more thing that matters and that most calculators ignore: property tax reassessment. If you live in a state that triggers a reassessment on refinance or home equity activity, your annual taxes could jump, which affects your PITI and therefore your qualification. In California and a few other states, this is a real issue that can shrink your usable equity by thousands of dollars. A good estimator accounts for it. Most free ones do not.
The bottom line is that a HELOC estimator is a starting point, not a destination. It gives you a direction. The actual number comes from the people who are going to lend you the money, and they will use their own data, their own appraisal standards, and their own risk models. The best approach is to run the tool, get a general sense of your position, and then validate it with real lender numbers before you plan anything around that estimate.