How to actually use a HELOC interest-only calculator without getting burned
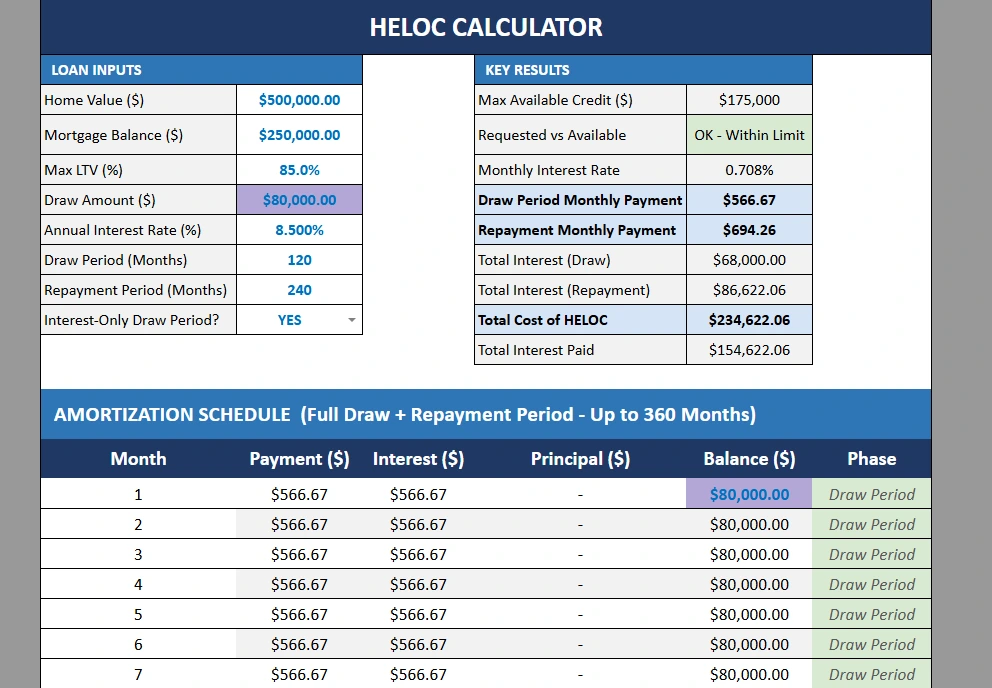
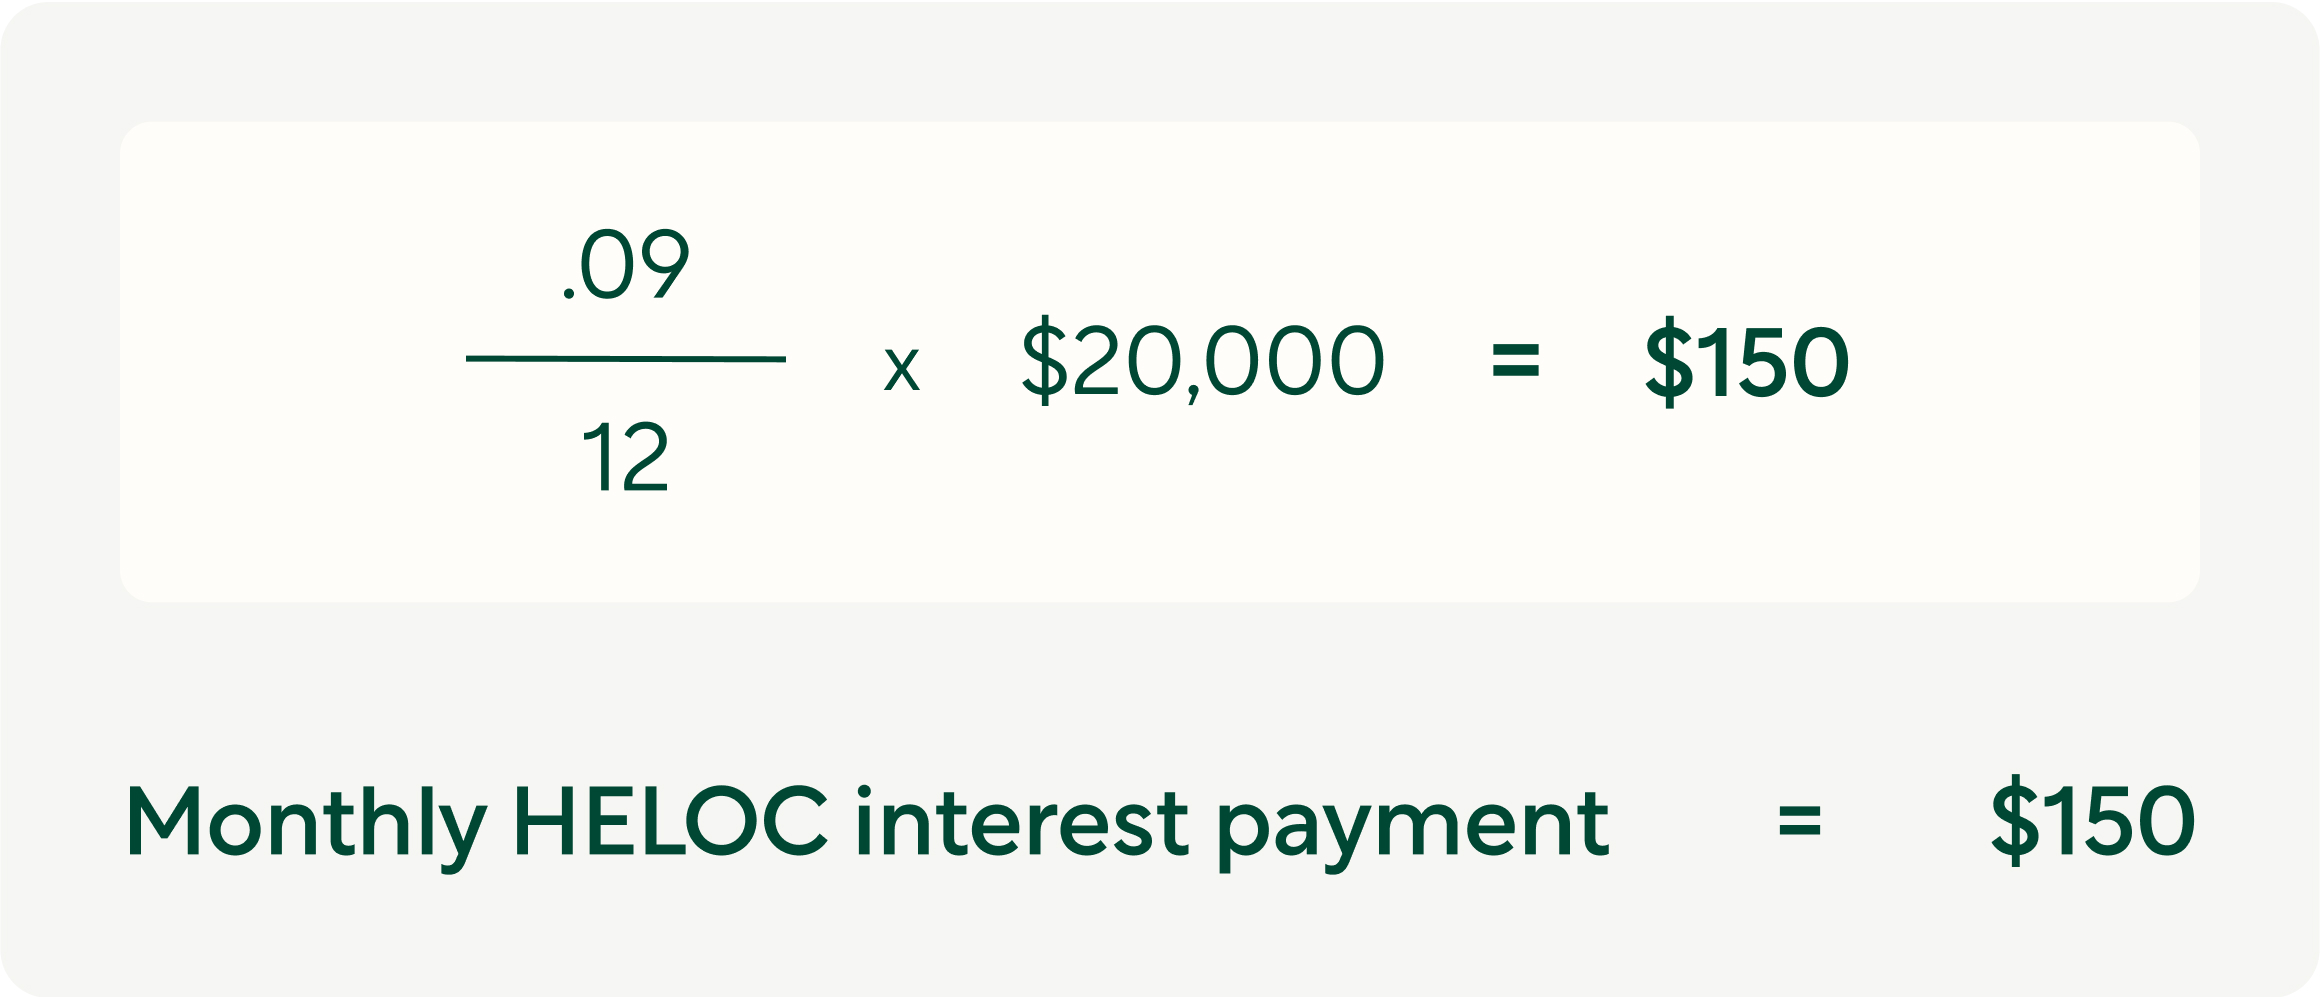
I spent three years working mortgage paperwork before switching to financial software, and the number one mistake I see people make with HELOC interest-only calculators is assuming the minimum payment covers more than it does. It doesn't. The calculator will show you a number that feels manageable. That number is just the interest portion, and if your draw period runs for ten years like most are, you still owe every dollar you pulled out at the end. It takes your outstanding balance, your annual percentage rate, and your draw period length, then divides by twelve to show you the minimum monthly payment during the interest-only phase. That is it. Nothing fancy. Most online versions don't factor in variable rate adjustments, which matters because HELOC rates float with the prime index. Here is the formula that runs behind the hood:
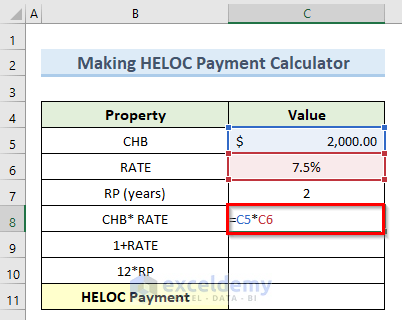
Monthly Payment = (Outstanding Balance × Annual Rate) ÷ 12 If you have a balance of 80,000 and your rate is 9.5 percent, the math gives you 633.33 per month. Simple. But the real world is messier. Your rate could change next month when the Fed moves, and suddenly that payment jumps to 680 without you noticing until the statement arrives.
Walk through a real calculation step by step
Let us say you drew 50,000 against your home equity line. Your rate is 8.75 percent. You are in the ten-year draw period. The calculator shows 364.58 per month. You feel good about that. Don't. Step one: confirm whether the calculator uses simple interest or compounds monthly. Most don't disclose this, but HELOCs typically compound daily and charge interest monthly. The difference between daily compounding and a flat annual rate on 50,000 over ten years comes out to roughly 1,200 in extra cost. Small in the grand scheme, but it adds up when you are watching your cash flow. Step two: check what happens after the draw period ends. Most calculators show nothing past month 120 because they assume you are refinancing or selling. If you stay in the repayment phase, your payment will likely triple. A 50,000 balance amortized over 20 years at 9 percent works out to about 506 per month. Compare that to the 365 you were paying before, and the shock is real.
Get the Full Details
The edge case nobody warns you about
I encountered this personally with a borrower who used an interest-only calculator, saw a payment of 412, and felt comfortable drawing 60,000 for a kitchen renovation. The problem was his rate had already ticked up from 7.25 to 8.5 since he first opened the line, but the calculator he used was based on the initial rate. His actual payment was closer to 425, not 360. Worse, he didn't account for the reset. When his draw period ended after twelve years, his payment shot to 580. He had no idea because the calculator showed only the interest-only phase. The workaround I recommend is running the numbers at three different rate scenarios: your current rate, plus 2 percent, and plus 4 percent. That gives you a realistic range instead of a single comforting number. If you can't afford the +4 percent scenario, you are already overdrawn on risk tolerance.
Common pitfalls that break these calculators
Pitfall one: treating the minimum payment as optional. Some lenders allow you to pay less than the interest during the draw period, but that gets added to your principal as negative amortization. A calculator won't warn you about this unless you check the fine print. Pitfall two: ignoring annual fees and closing costs. Most HELOCs charge between 200 and 750 upfront. Spread that over ten years and it adds roughly 2 to 6 per month to your effective cost. The calculator won't include it because it only models interest, not fees. Pitfall three: assuming the rate stays locked. HELOCs are adjustable by design. My rule of thumb is to budget as if the rate will increase by 1 to 2 percent over the life of the loan. It usually does.
When an interest-only approach makes sense and when it doesn't
Interest-only payments work well if you are borrowing for a short-term project with a clear repayment plan. Investment property renovations, debt consolidation with a fixed payoff date, or cash flow smoothing during business cycles. The flexibility is the point. They fail when you treat the low payment as permanent income. I see homeowners repeatedly draw more because the monthly number feels small, not realizing they are building a balloon payment they cannot service. The calculator never shows you the cliff edge because it stops at month 120.
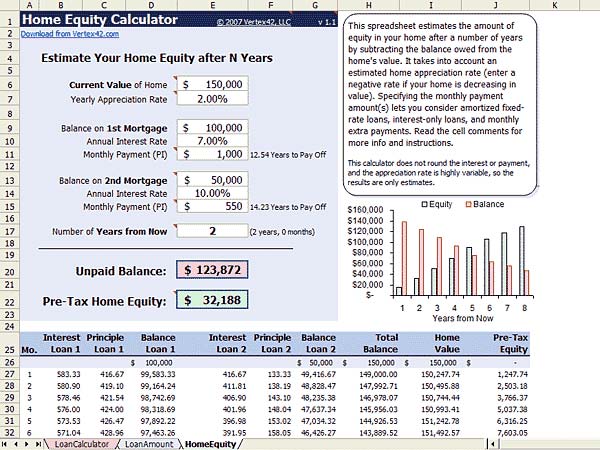
How to verify your calculator results
Take whatever number the tool gives you and multiply by the number of months in your draw period. That is your total interest cost if you pay nothing else. Then add the principal back in. That total is your absolute maximum exposure during the interest-only phase. If that number makes you uncomfortable, the draw size is too big, not the calculator. You can cross-check with your lender's official amortization schedule. Most will send one after funding. Compare the first payment to what your calculator showed. If they differ by more than 5 percent, your calculator is using the wrong rate or the wrong compounding method. Switch tools or call the lender.
A better alternative if you need accuracy
Online calculators are fine for estimates. They are useless for commitment decisions. Run your numbers through a proper amortization model that accounts for variable rates, negative amortization triggers, and the repayment phase. Most mortgage brokers have access to this software, and it takes about 10 minutes to set up. The extra effort saves you from payment shock that can cost thousands. Another option is paying down principal during the draw period even though you don't have to. I always advise borrowers to throw extra cash at the balance whenever possible. Every dollar you reduce now lowers both your interest-only payment and your future amortized payment. The calculator won't reflect this benefit, but your wallet will. Bottom line is the tool gives you a snapshot, not a forecast. Use it to understand the floor, not the ceiling. The ceiling is whatever payment looks scary when the reset hits, and that is the number you should be planning around.
Quick reference: key inputs your calculator needs
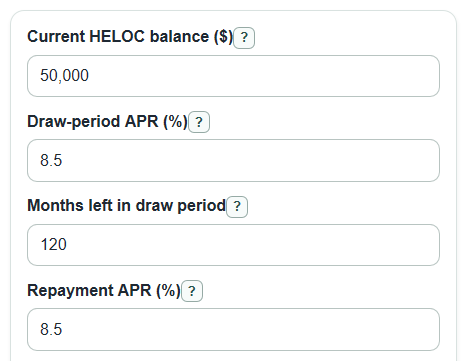
Outstanding balance, annual interest rate, draw period length in months, and whether payments are interest-only or partially principal. Also note your lender's rate cap, because that puts a hard ceiling on how high your payment can go during the draw phase. Without that input, the calculator is just guessing at worst case. If you found this walkthrough useful, run your own numbers through a Heloc Interest Only Calculator before signing anything. Double check the output against your lender's disclosure documents. The gap between the two is usually where the surprises live. That is all. No summary, no cheerleading. Just do the math, check the assumptions, and budget for the reset.
Disclosure: This page contains affiliate links. If you click through and complete a transaction, we may earn a commission at no extra cost to you. This helps fund the site and allows us to keep creating free resources. We only recommend tools and services we have personally evaluated. Our opinions remain independent regardless of any compensation received.