How to actually calculate your HELOC interest-only payment without guessing
Most people pull up some free calculator on the internet, type in their numbers, and walk away thinking they know what their payment will be. That is usually wrong. Not because calculators are broken, but because nobody explains the parts that the calculator silently omits. I spent years running these numbers for clients who came in thinking they understood their closing costs and payment structure. They never did.Using a Heloc Interest Only Payment Calculator correctly
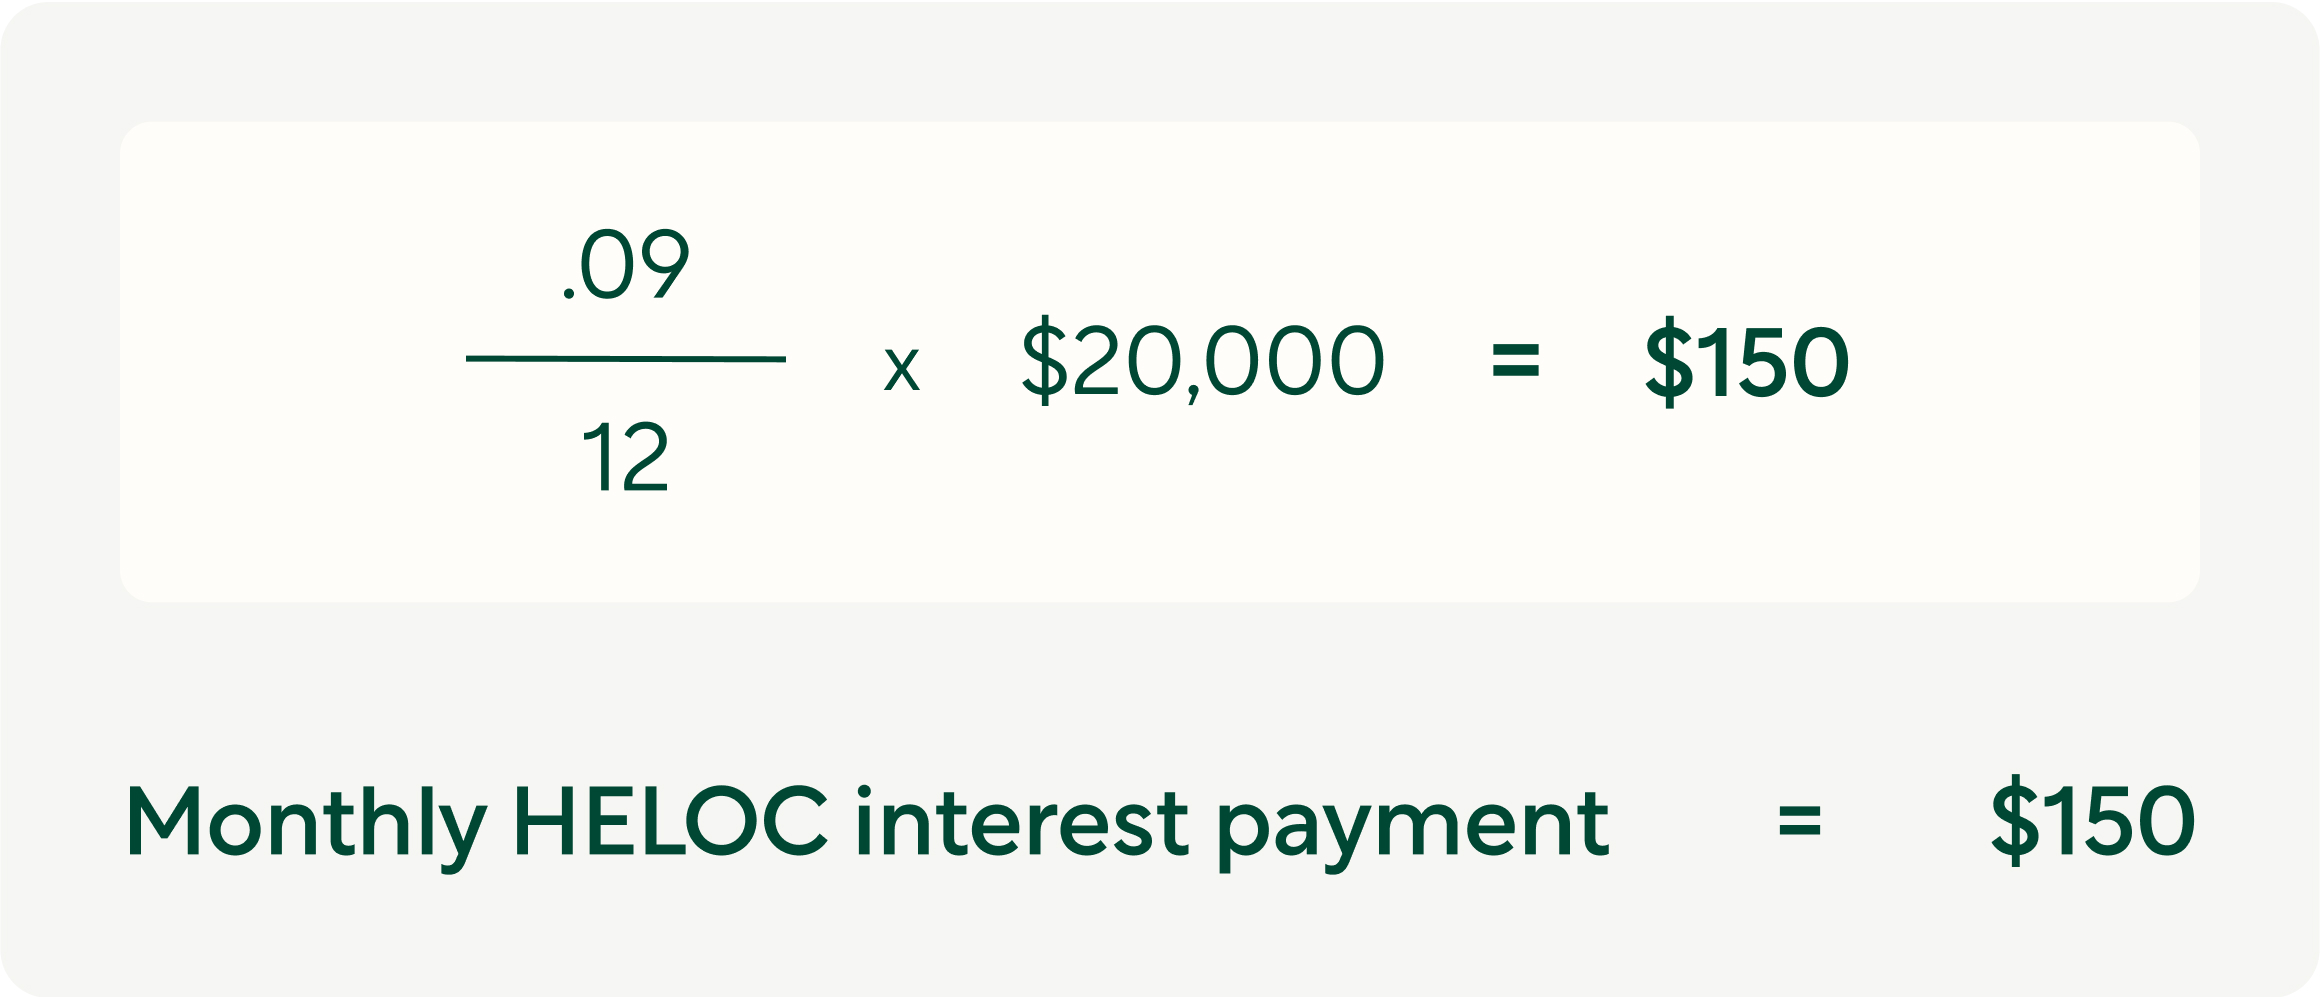
The basic formula is straightforward enough. Take your outstanding HELOC balance, divide it by 100 to get the percentage, divide that by 12 for the monthly rate, then multiply by your current balance. So if you owe $50,000 at 8.5% interest, your monthly interest-only payment is $354.17. Any decent Heloc Interest Only Payment Calculator will spit that number out in two seconds. Here is where it gets messy. Most HELOCs have a draw period that lasts somewhere between five and ten years. During that time you are only paying interest. After the draw period ends, the repayment period kicks in and suddenly you are paying principal and interest on whatever balance remains, amortized over maybe fifteen or twenty years. That payment can jump dramatically. I had a client once who calculated her interest-only payment at about $400 a month and felt fine about it. When the repayment period started, her payment was $1,200 a month. She had no idea that was coming. Nobody at the bank mentioned it either. Another thing most calculators ignore is that HELOC rates are variable. The rate you see today is not the rate you will have tomorrow. If the prime rate moves up half a point, your payment goes up. I ran into this exact situation when a client's adjustment date hit and their rate ticked up from 7.25% to 7.75%. Their monthly payment jumped by about $25 with no warning beyond what was in the fine print. The calculator had given them a fixed number and that number was already stale by the time they looked at it.
There is also the issue of how payments are calculated when you are making partial draws. Some lenders calculate your minimum payment based on the full credit line, not just the amount you have drawn. So even if you only borrowed $10,000 out of a $100,000 HELOC, your payment might be computed as if you owe the full $100,000. That is a critical detail. I worked with someone whose lender was doing exactly this and she had no idea why her payment was so much higher than her actual balance would suggest. She had to pull her origination documents and find the clause that said payments were based on the total line of credit rather than the outstanding balance. Without that document she would have kept wondering what was going on. When you are using a calculator, make sure you are entering the right numbers. A lot of online tools ask for your credit line amount instead of your actual balance. Those two things are not the same. Enter the wrong one and your result is meaningless. Double-check which field is which before you hit calculate. I have seen people enter their credit limit as their balance and then stress over a payment that was three times what they actually owed. It happens more often than you would think. There is also the question of whether your lender charges a minimum monthly payment that is higher than the interest accrued. Some HELOCs have a floor, like $25 or $50 per month, even if your interest calculates to less than that. That rarely matters when you have a large balance, but if you pay down most of your HELOC and are left with a small remainder, that minimum can be a surprise. I once calculated a payment of $12 for a remaining balance of about $1,700 and my client's lender was still charging $50. The calculator gave a technically correct answer but the real payment was four times higher.
If you want to do this manually without relying on a web tool, grab your most recent statement. Find the daily periodic rate, which is your annual rate divided by 365. Multiply that by the number of days in your billing cycle, then multiply by your average daily balance. That gives you the exact interest charge for the period. It takes about ten minutes and it is more accurate than most online calculators because it accounts for the actual daily balances rather than a single snapshot number. Most people skip this because it feels tedious, but it only takes a few minutes and it tells you what you actually owe instead of what a generic calculator thinks you owe. The main limitation of any Heloc Interest Only Payment Calculator is that it cannot account for rate changes, payment floors, or the shift from interest-only to principal and interest when your draw period ends. Treat the output as a rough estimate, not a committed number. If you want something closer to reality, build a simple spreadsheet where you can adjust the rate each time your adjustment date comes around and see what the payment looks like under different scenarios. I usually tell people to model three cases: current rate, rate plus one percent, and rate plus two percent. That covers the range of what usually happens in practice.
Get the Full Details