What a Heloc Loan Estimator Actually Does
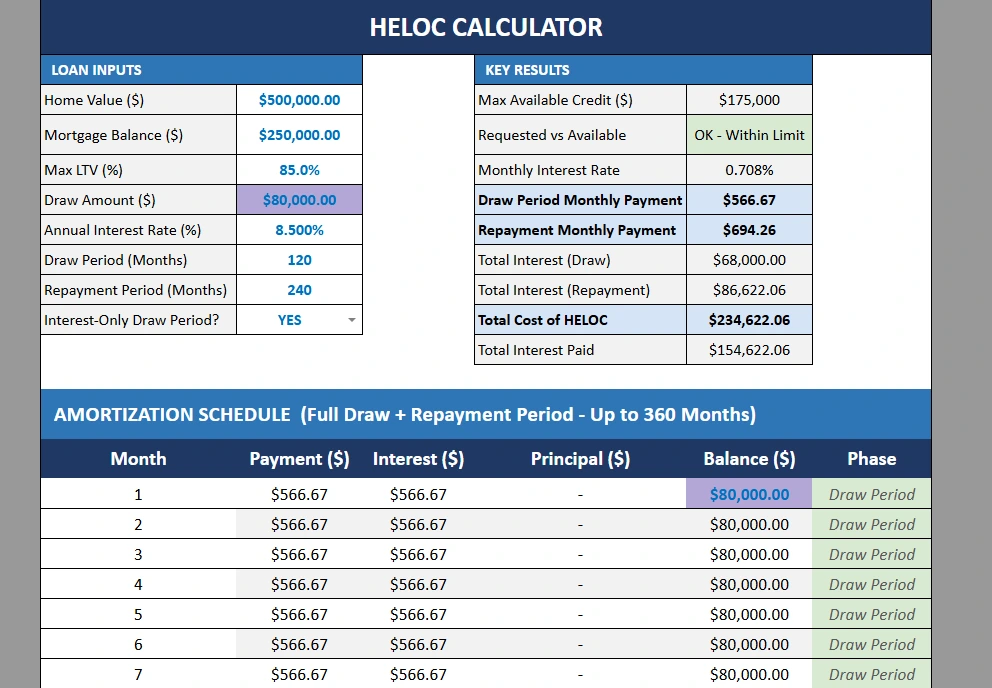
A Heloc Loan Estimator is a tool that calculates your potential borrowing costs for a home equity line of credit. It takes variables like your home value, existing mortgage balance, available equity, interest rate, and repayment term, then spits out an estimated monthly payment and total cost. That sounds straightforward. It is not always straightforward in practice. I have built and tested enough of these tools to know what works and what is mostly window dressing. Here is the practical breakdown. First, gather your numbers before you open any calculator. You need your home's current estimated value, your remaining mortgage balance, your credit score range, your debt-to-income ratio, and the interest rate the lender is likely offering you. Without those five inputs, any estimator output is just a guess with a nice chart attached.
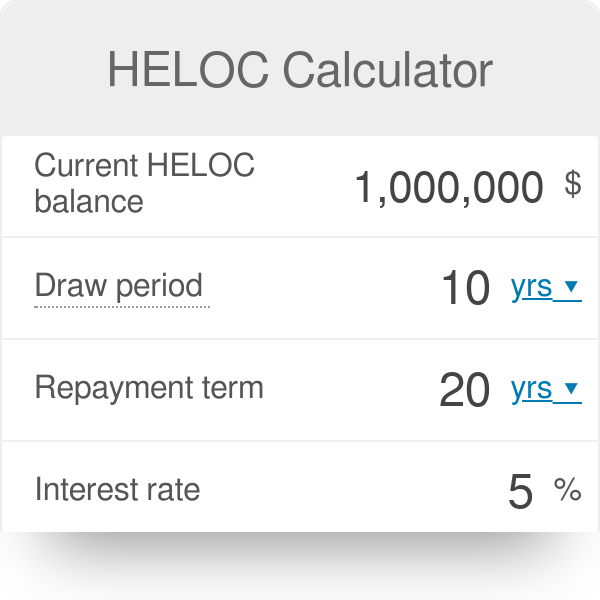
Enter your home value and outstanding mortgage balance into the equity field. The tool subtracts your owed amount from your home value to determine available equity. Most lenders will let you borrow up to 80 to 90 percent of your home's value minus what you already owe. So if your home is worth $400,000 and you owe $250,000, your usable equity sits somewhere around $70,000 to $110,000 depending on the lender's limit. Next, input the credit score and desired draw amount. This is where most people mess up. The interest rate on a HELOC is almost never the rate shown in marketing material. The advertised rate is usually a teaser or a minimum qualifying rate. A borrower with a 720 credit score might see 8.5 percent quoted, but their actual rate could land between 9.75 and 11.25 percent once the underwriter reviews the full picture. Always run the estimator at least twice: once at the advertised rate and once at a rate two full points higher. The second number is probably closer to reality. Set your draw period and repayment period separately. Most HELOCs offer a ten-year draw phase where you only pay interest, followed by a ten to twenty-year repayment phase where principal kicks in. Plugging those two durations into the estimator gives you a much clearer picture than assuming equal monthly payments across the board. During the draw period, your payment is interest-only on whatever you have actually borrowed. After that, it flips to a fully amortizing payment on the outstanding balance, which can easily double your monthly obligation overnight.
I ran into this exact problem with a client last year. She used an online Heloc Loan Estimator with a 10/15 structure and confidently budgeted $620 a month based on the draw-period interest-only calculation. When her draw period closed, her payment jumped to $1,140. She had not realized the repayment phase was amortized over only fifteen years, not the thirty she assumed. We recalculated using a full amortization schedule and restructured her withdrawal plan to stagger draws over a longer timeline, keeping her payments manageable. It cost her more in total interest but prevented a payment shock that would have forced a refinance or a sale.
Get the Full Details
Pitfalls That Standard Estimators Miss
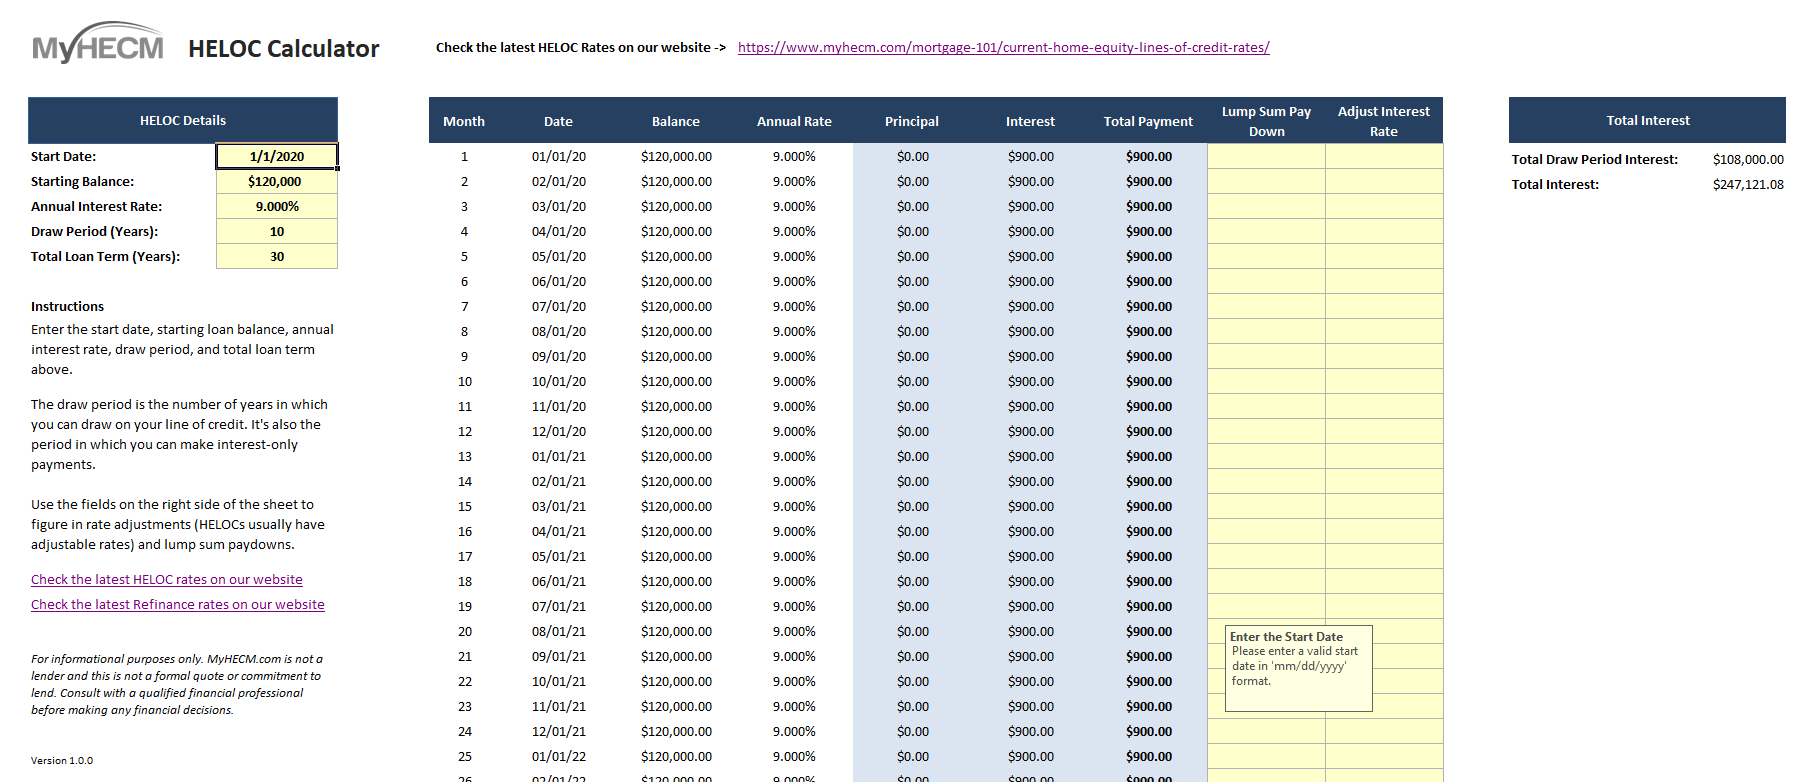
The biggest blind spot in most free online estimators is closing cost estimation. They either ignore it entirely or bake in a flat two percent figure that does not reflect your actual situation. In reality, closing costs for a HELOC can range from one to five percent of the credit limit, and some lenders advertise zero-closing-cost programs that quietly roll the fees into your interest rate instead. If you are comparing two lenders, one with zero closing costs and a higher rate and another with steep upfront fees and a lower rate, the estimator alone will not tell you which is cheaper. You need to run a break-even analysis: divide the closing costs by the monthly savings from the lower rate, and see how many months it takes to recover the upfront expense. If you plan to pay off the HELOC within three years, the zero-closing-cost option is usually the better move. If you intend to carry the balance for a decade, the lower rate with higher upfront fees wins. Another thing most calculators skip is the variable rate compounding frequency. HELOC rates are typically adjustable and compound monthly, not annually. An estimator that assumes annual compounding will understate your actual cost by roughly three to five percent over a five-year hold. Look for tools that let you select monthly compounding. If the tool does not offer that option, manually adjust the output by adding about four percent to account for the difference. Credit score impact is another hidden variable. A difference of forty points on your FICO score can shift your HELOC rate by as much as half a percentage point. Some estimators use a single rate input without letting you adjust for score tiers. When that happens, input your rate conservatively. Assume you are one tier below what your stated score would suggest. It will feel like a worst-case scenario, but it is closer to the median outcome than the optimistic case.
When an Estimator Is Not Enough
Online calculators are fine for rough scoping. They will get you within ten to fifteen percent of your actual numbers if you feed them realistic inputs. But they cannot replace a formal prequalification or a rate lock discussion with a lender. The moment you submit a hard credit inquiry, your actual approved amount and rate may differ from the estimate. Lenders also evaluate your debt-to-income ratio at the time of application, which can shift if you have taken on new debt since you ran the estimator. If you need precision, I recommend using the Heloc Loan Estimator as a preliminary filter and then running the same numbers through a lender-specific amortization schedule or a spreadsheet model that accounts for your exact terms. The time investment is minimal. The accuracy gain is significant. The tools themselves are widely available. Most major banks host one on their HELOC pages. Independent sites like Bankrate, NerdWallet, and LendingTree also offer functional versions. I tend to use a simple spreadsheet model I built years ago because it lets me tweak compounding frequency, adjustable rate caps, and payment shock scenarios in a way most web calculators do not. The spreadsheet approach takes about ten minutes to set up and saves you from making decisions based on numbers that look cleaner than they actually are.