The Real Problem With HELOC Payments
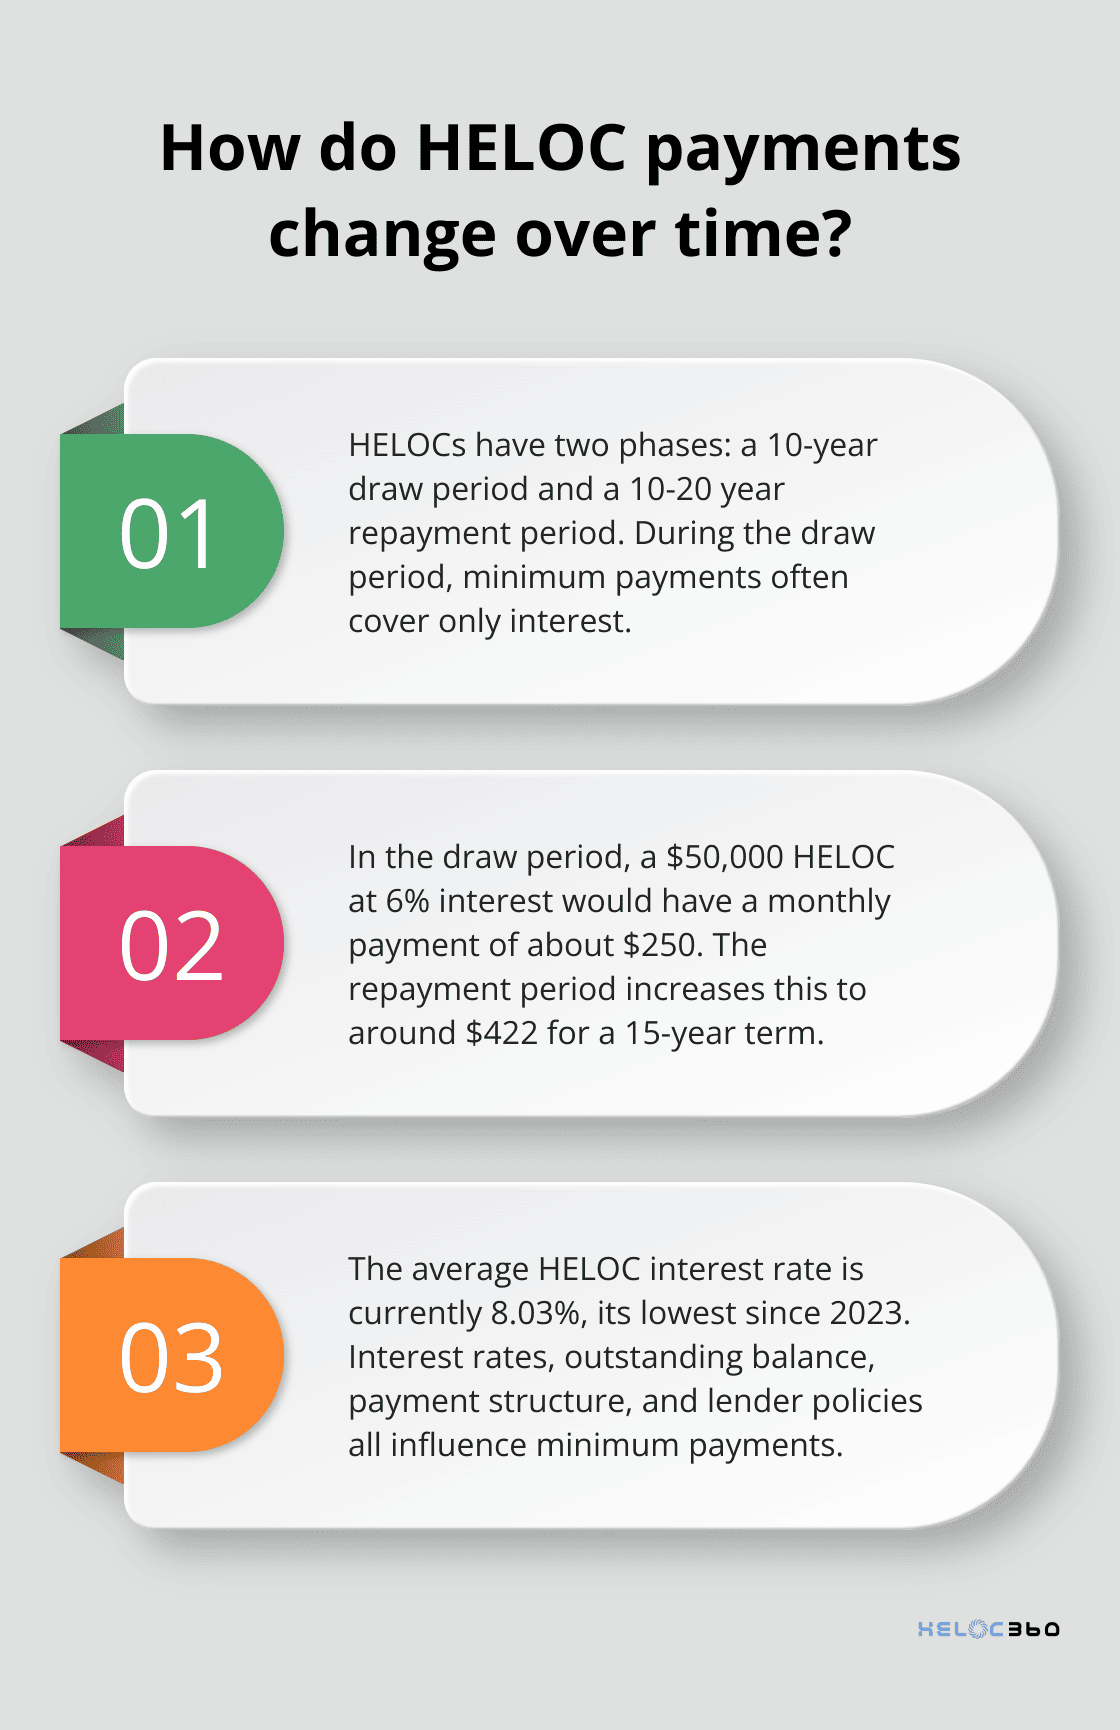
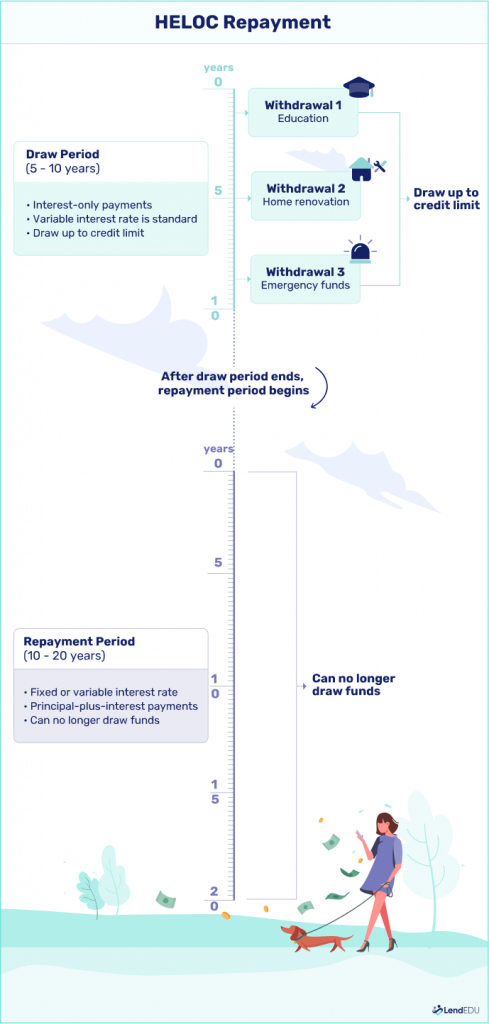
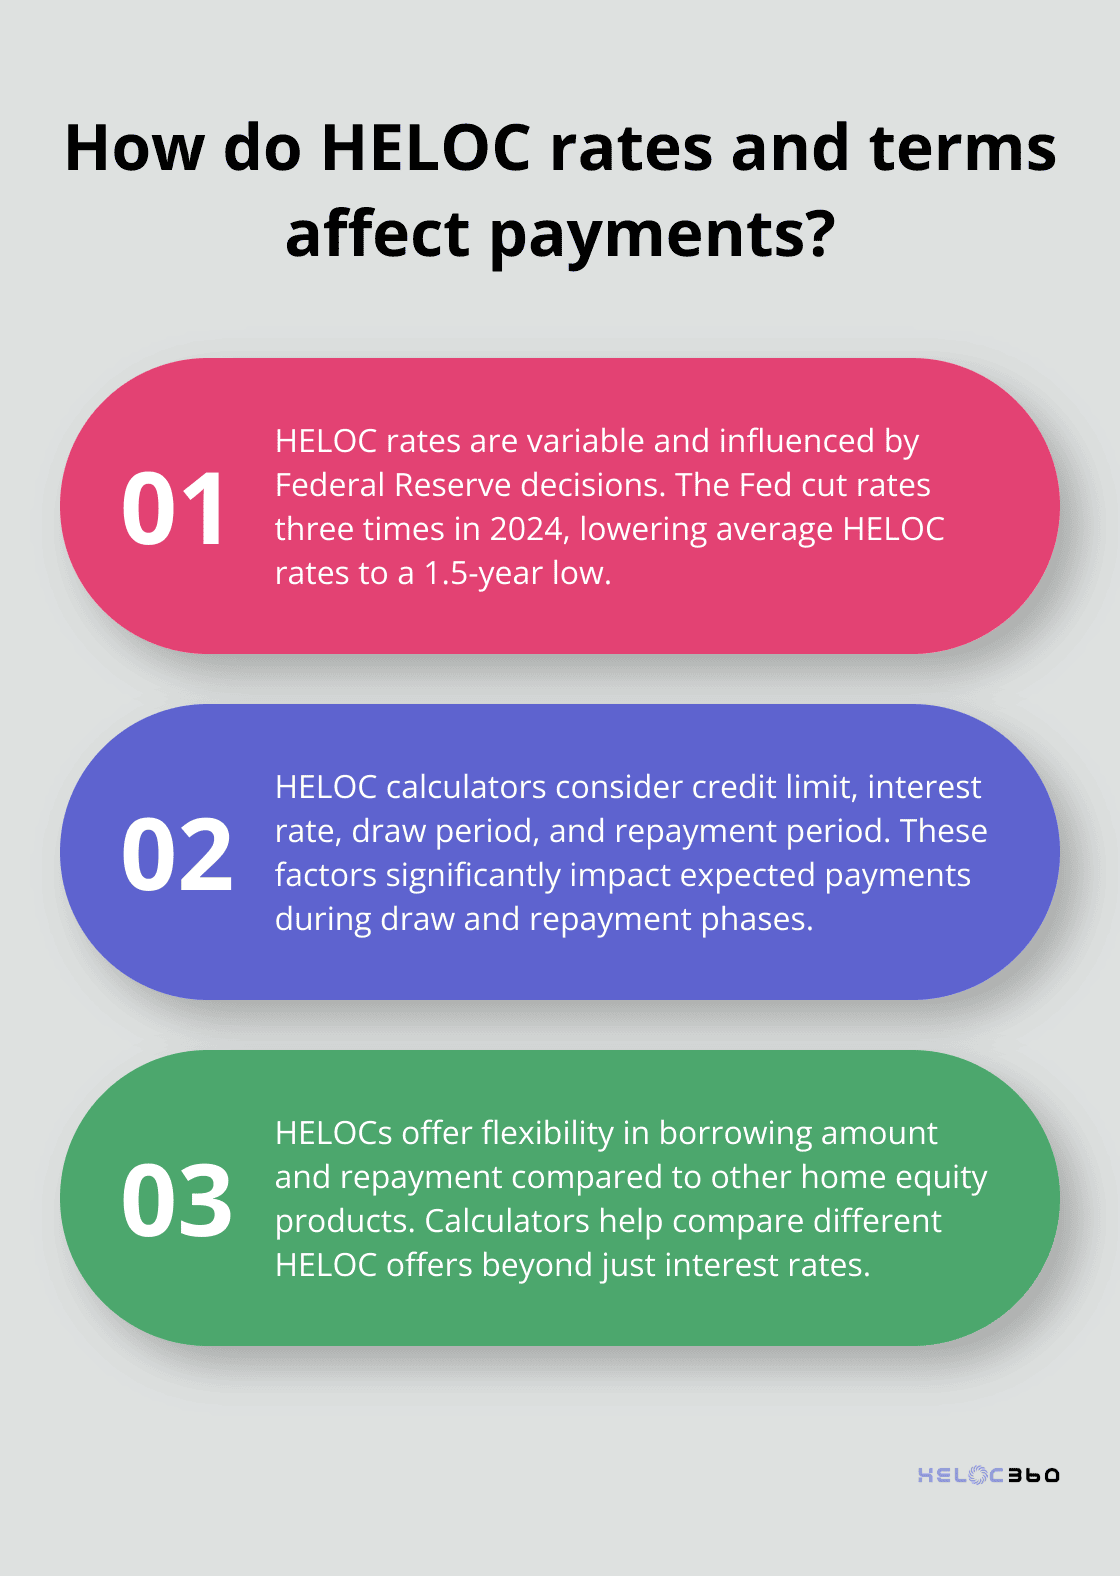
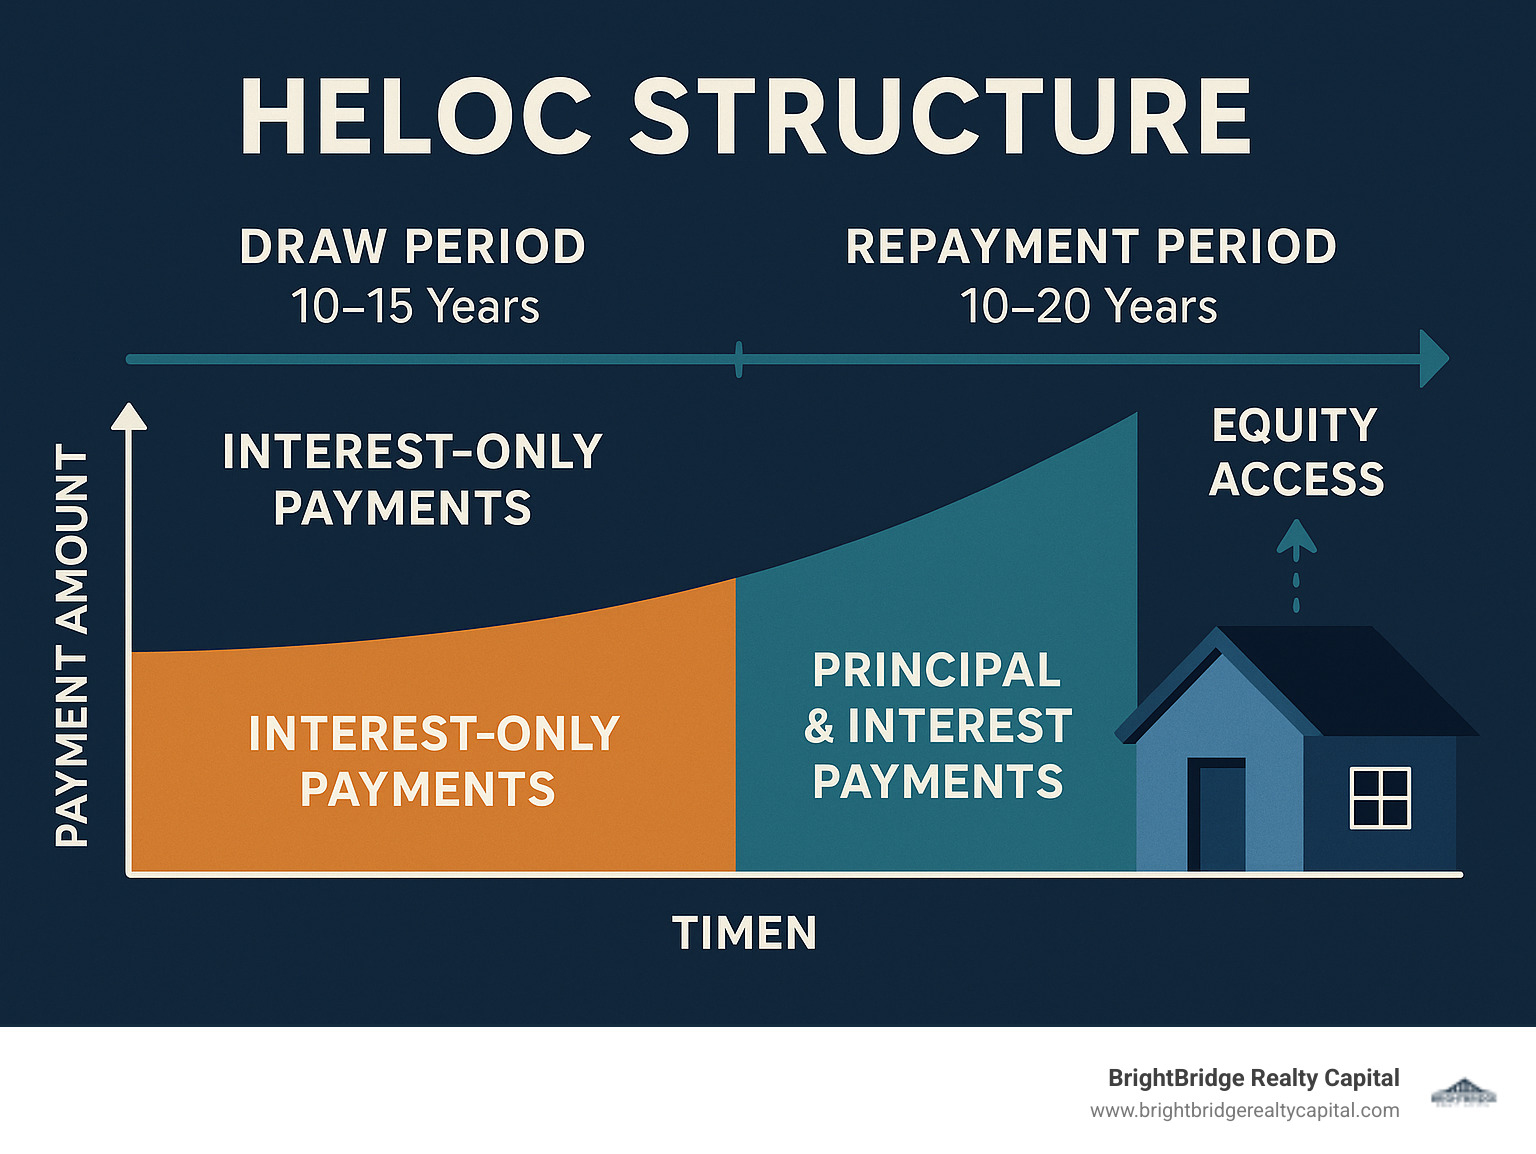
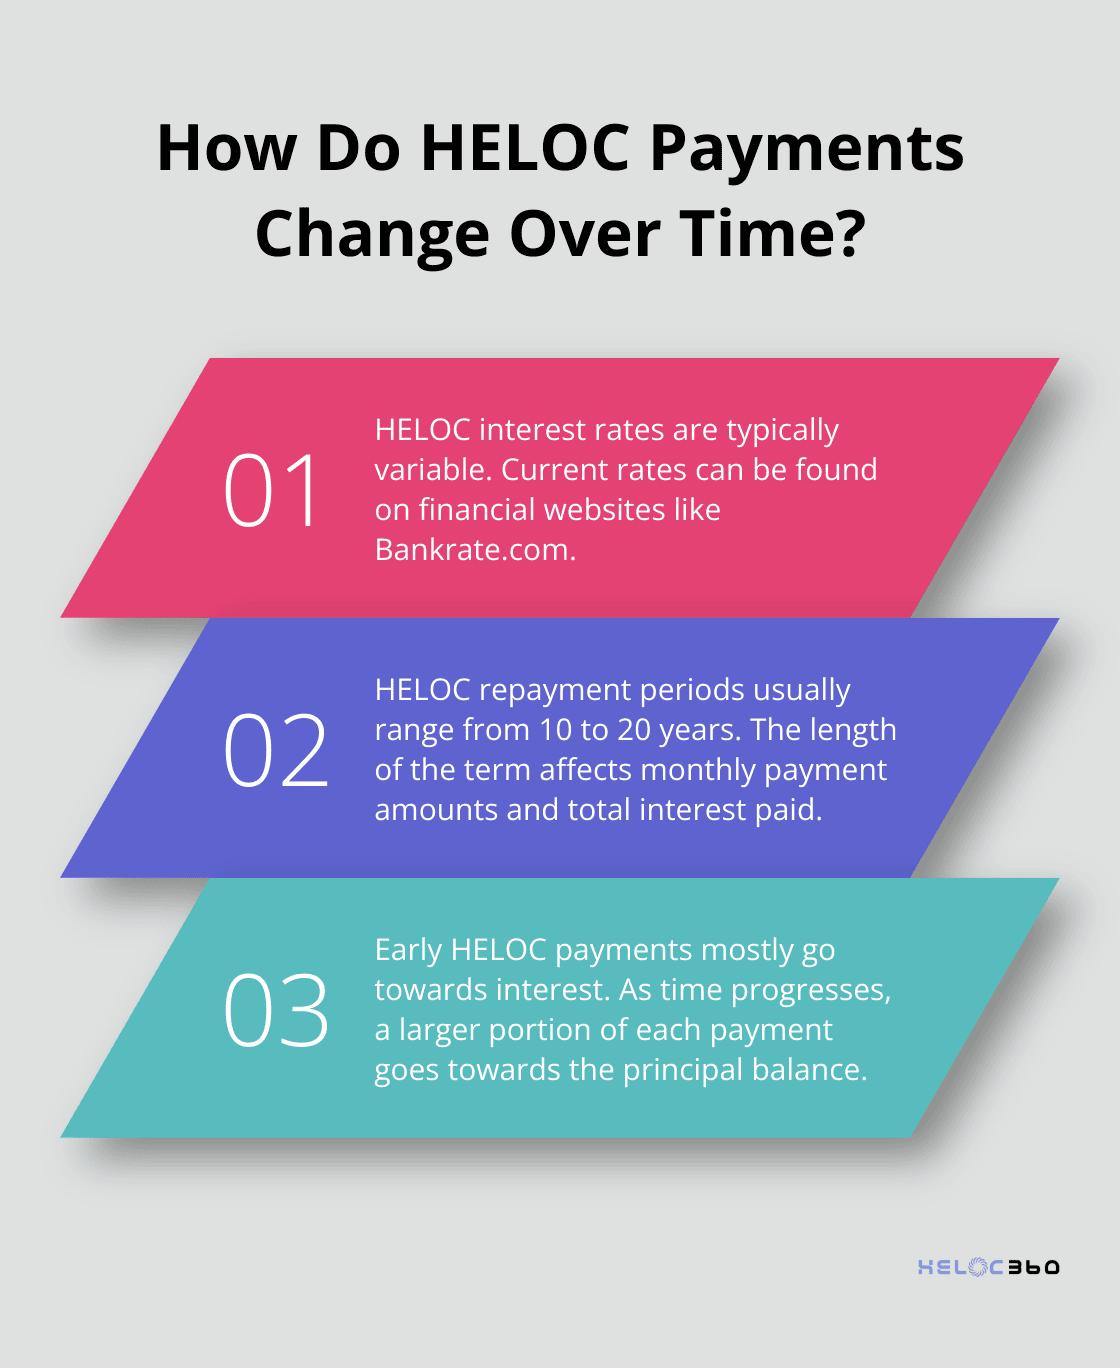
Most people get confused about HELOC loan payments because they never actually read their disclosure documents, not because the math is hard. I went through this with a client in 2019 who had pulled out $47,000 during the 10-year draw period on a home equity line. She was making minimum payments for eight years straight without giving it another thought. When the repayment period kicked in, her monthly payment jumped from about $480 to roughly $610 and stayed there for 20 years. She had no idea this was coming. A HELOC has two distinct phases. During the draw period, which typically runs 5 to 10 years, you only pay interest on whatever you've actually borrowed. That means if you have a $100,000 line but only used $30,000, your minimum payment is calculated against $30,000, not the full $100,000. After the draw period closes, the repayment period begins and you start paying both principal and interest until the balance reaches zero. This transition is where most payment shock happens. The interest rate on a HELOC is variable, tied to the prime rate plus a margin set by your lender. The current prime rate sits around 8.50%, and most HELOCs add a margin between 0.75% and 3.50%. So your rate could be anywhere from roughly 9.25% to 12% depending on when you opened the line and what your lender charged. When the Fed moves rates, your payment moves with it automatically. There is no negotiation on this after closing.
Here is the straightforward way to calculate your minimum payment during the draw period. Take your outstanding balance, divide it by 12 to get the annual interest, then divide that by 12 again to get the monthly interest charge. If you owe $40,000 at an 10% rate, your minimum payment is $333.33 per month. That is pure interest. Zero principal reduction. Every dollar goes toward keeping the lender happy while the full $40,000 remains owed. During the repayment period, the calculation changes completely. You now have an amortizing loan with a fixed number of remaining payments. Using the same $40,000 balance at 10% over 20 years, your payment becomes approximately $429 per month. Over the life of that loan, you will pay about $6,320 in interest on top of the $40,000 principal. The payment is higher every month because you are finally chipping away at the actual debt. I ran into a specific edge case that nobody warns you about. A borrower I worked with in 2021 had a HELOC with a 15-year draw period and a 25-year repayment period. He had paid down his balance to $12,000 during the draw period by making occasional extra payments. When the repayment period started, his servicer miscalculated and set his payment based on the original $60,000 peak balance instead of the current $12,000. He was overpaying by about $85 a month for the entire first year before he noticed. The fix required calling the servicer, providing a written dispute with a current payoff quote, and following up twice. It took roughly three weeks and two phone calls to get it corrected.
This is why you should request an annual statement that shows your current outstanding balance separately from your available credit. Most online portals display this clearly, but not all servicers do. If yours does not, call them and ask for it in writing. Having a paper trail makes disputes significantly easier to resolve. Another thing that catches people off guard is the prepayment structure. Some HELOCs charge a prepayment penalty if you pay off the balance early during the draw period, usually 1% to 3% of the amount being paid early. Others do not. Check your original promissory note for this clause. It is usually buried in the fine print near the end of the document, sometimes on a page you would not normally read. I found this clause on a HELOC in 2020 that a borrower had been carrying for six years without knowing about it. She paid off $35,000 one afternoon and got hit with a $700 penalty. She had never made a large extra payment before and the servicer had never notified her. If your HELOC has a prepayment penalty, time your payoff strategically. Most penalties only apply within the first three to five years of the line. Once that window closes, you can pay down the balance freely. Make sure you track the exact date the penalty period expires. Write it down somewhere permanent. The servicer will not remind you.
Get the Full Details
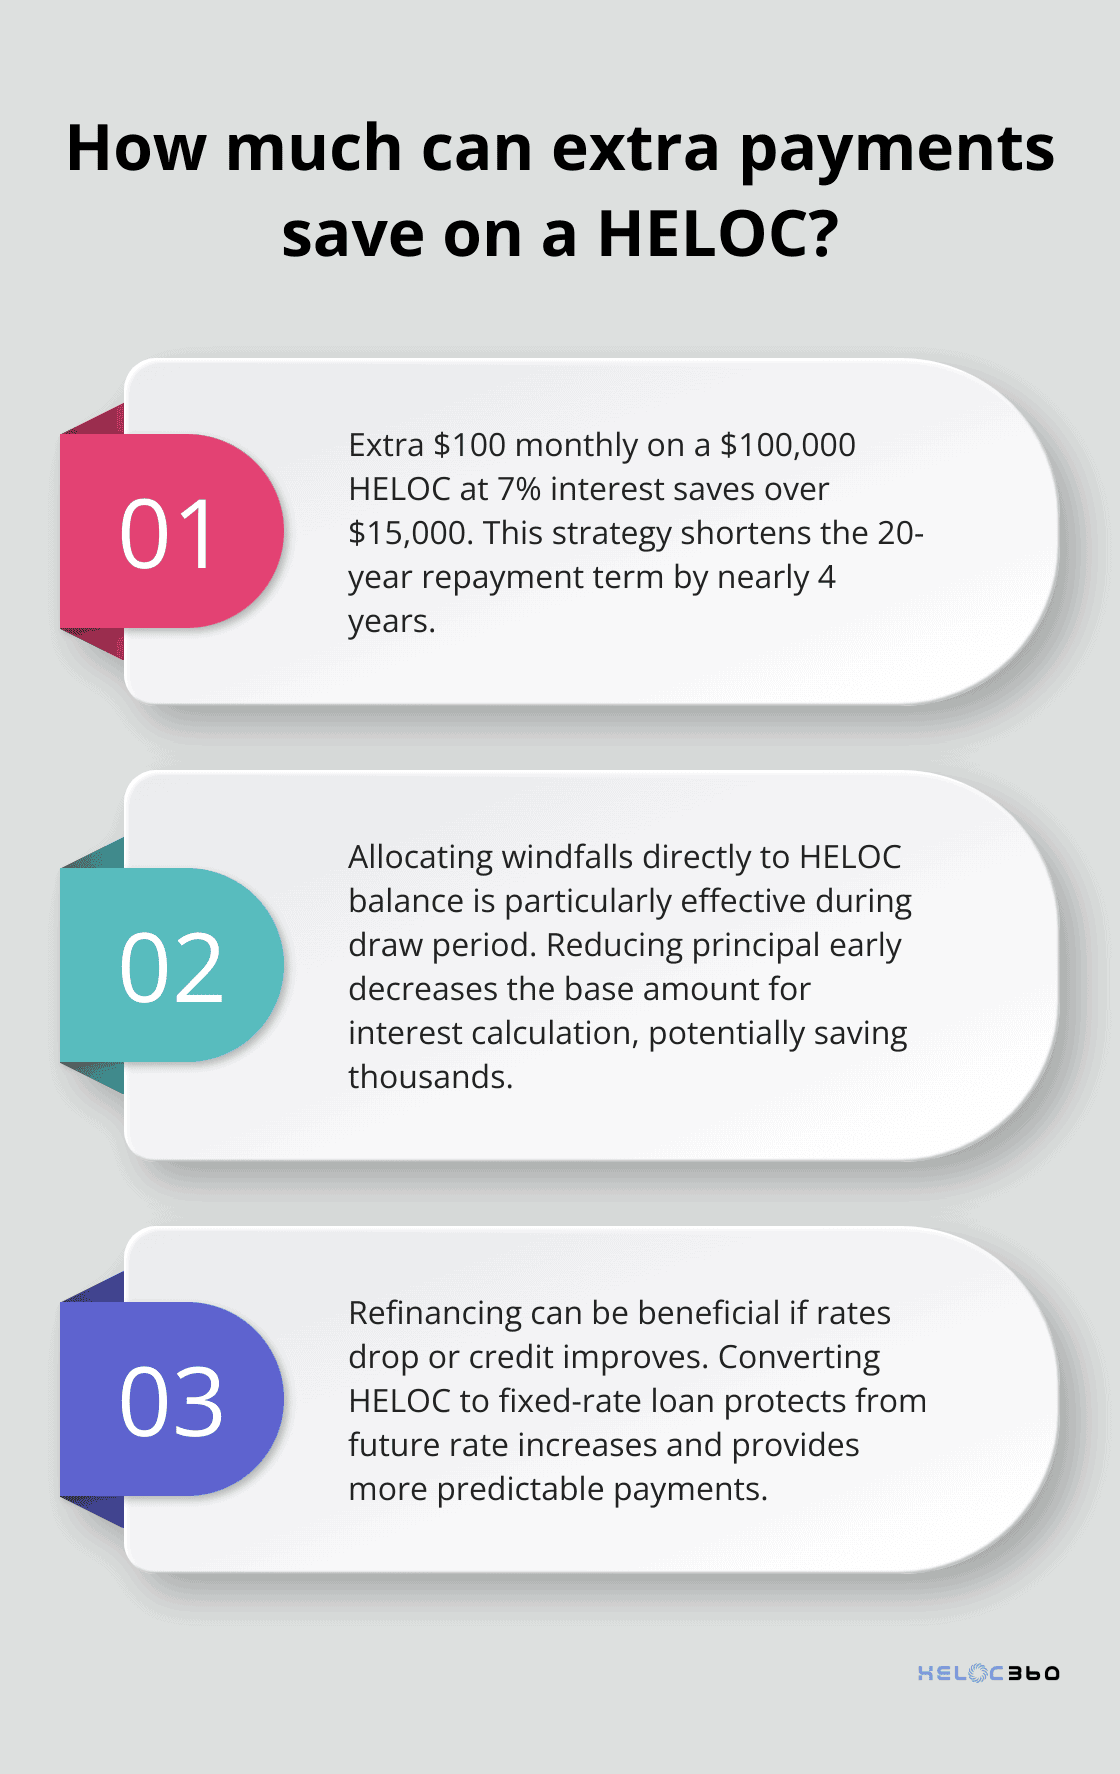
There is also the matter of payment frequency. Some servicers require payments on a specific date each month, while others allow more flexibility. A few will let you set up autopay with a small discount on your interest rate, usually 0.25%. That discount sounds small but adds up to roughly $100 per year on a $40,000 balance at 10%. It is free money if you can reliably keep enough funds in your checking account to cover the payment every month. One more thing that people routinely miss: your minimum payment does not include taxes and insurance. If your HELOC is structured as a first-lien loan, your lender may escrow those items, but most HELOCs are second liens and do not. You are responsible for paying your property taxes and homeowner's insurance directly. When those bills come due and you were budgeting only for the HELOC payment, it creates a sudden gap. Plan for this annually. The bottom line is that HELOC loan payments are simple in structure but dangerous in practice because the payment amount can change dramatically without warning. The draw period lulls you into a low payment habit, and then the repayment period hits all at once. The best approach is to treat the minimum payment as optional and pay down the balance as aggressively as possible during the draw period. Even small extra payments compound significantly over time because they reduce the principal that will later be amortized at a higher payment level.