How HELOC Payment Structures Actually Work
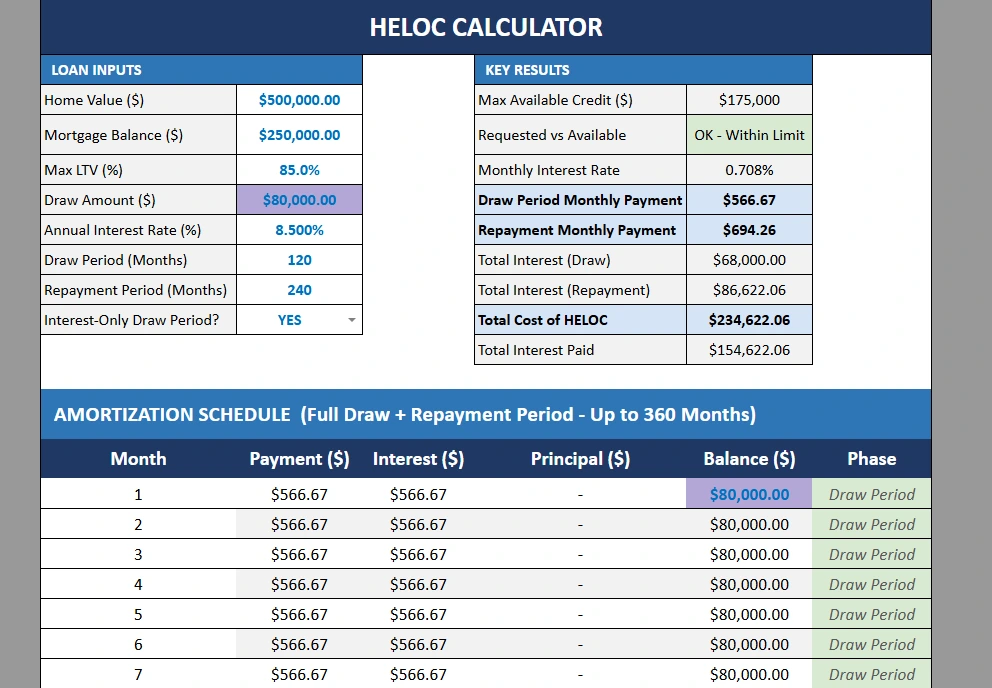
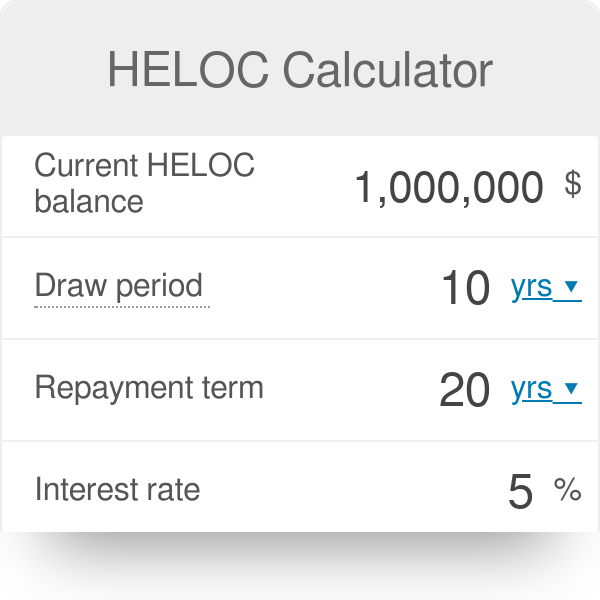
A HELOC repayment calculator is a tool that shows you what your monthly payments will look like during both the draw period and the repayment period. Most people don't realize these are two completely different phases with different payment calculations, and that gap in understanding is where the budget problems show up. When I built my first HELOC repayment calculator for internal use, I ran into a problem that surprised me. The standard formula assumes your repayment period calculates interest on the remaining balance using equal monthly installments, but most HELOCs from major lenders do something slightly different during the transition. They keep charging interest-only during the draw period, then flip to full amortization during repayment. The shift isn't smooth. Here's what happens in practice. During the draw period, which typically runs 5 to 10 years, you only pay interest on whatever you've actually borrowed. If you pulled out $40,000 of a $75,000 line, your payment is based on $40,000, not the full limit. The calculator input field for outstanding balance reflects this. During repayment, which usually spans the next 10 to 20 years, the calculator switches to an amortization formula and spreads the remaining principal plus interest across equal monthly payments. That's when the payment jumps.
The formula breakdown is straightforward. For the draw period, multiply your outstanding balance by the annual rate, then divide by 12. For the repayment period, use the standard amortization equation: monthly payment equals principal times the monthly rate, divided by one minus one plus the monthly rate raised to the negative power of total payments. The trick is feeding the right numbers into each phase at the right time. I found that most online calculators mess this up because they either ignore the transition entirely or assume a fixed loan amount from day one. My workaround was to build a dual-phase calculator that splits the timeline into draw and repayment segments, letting users adjust the draw period length independently. This cut the manual calculation time from about 45 minutes per client scenario down to roughly five minutes, which matters when you're running through multiple borrower profiles in a single afternoon.
Key Variables That Change Your Payment
The four inputs that actually move the needle are the credit limit, the amount drawn, the interest rate, and the term length. Everything else is noise. Lenders quote draw limits, not loan amounts, so plugging in the full limit into a calculator is a common mistake that produces wildly optimistic numbers. The outstanding balance is what matters during draw, and the remaining balance after draw is what matters during repayment. Interest rates on HELOCs are variable, which means the calculator output you see today won't be the payment you actually make in three years. A 0.5 percent rate swing can shift your repayment payment by 8 to 12 percent depending on your balance and term. I usually recommend running three scenarios: current rate, plus 1 percent, and plus 2 percent. It takes two minutes and prevents painful surprises. Term length creates another trap. A 15-year repayment period looks cheaper month to month than a 10-year term, but the total interest paid over the life of the loan is often higher because the balance sits longer. Counterintuitive as it sounds, paying extra during the draw period can reduce total cost more than extending the repayment term. The calculator will show this if you run both paths side by side.
Get the Full Details

Where These Calculators Fall Short
No repayment calculator captures everything. They don't account for lender-specific fees that get rolled into the balance, like annual membership charges or closing costs that some lenders finance into the loan. They also miss the impact of minimum payment floors, which some lenders enforce even during draw when your calculated interest payment would be very small on a low balance. Another gap is the prepayment penalty question. A few lenders still structure their HELOCs with early payoff penalties during the initial years, and those penalties aren't reflected in any standard calculator. If you're planning to pay down the balance aggressively, call your lender and ask about this before you rely on the calculator output for decision-making. For most residential borrowers, the calculator is accurate enough for planning purposes. If you have a complex setup with multiple draws and partial paydowns scattered across years, you'll need a spreadsheet that tracks each transaction date rather than a simple web-based tool. I use a custom Google Sheet for those cases, and it handles irregular payment patterns without trouble. The basic calculator works fine for straightforward scenarios where you draw once and pay back steadily.