How a Heloc Ltv Calculator Actually Works
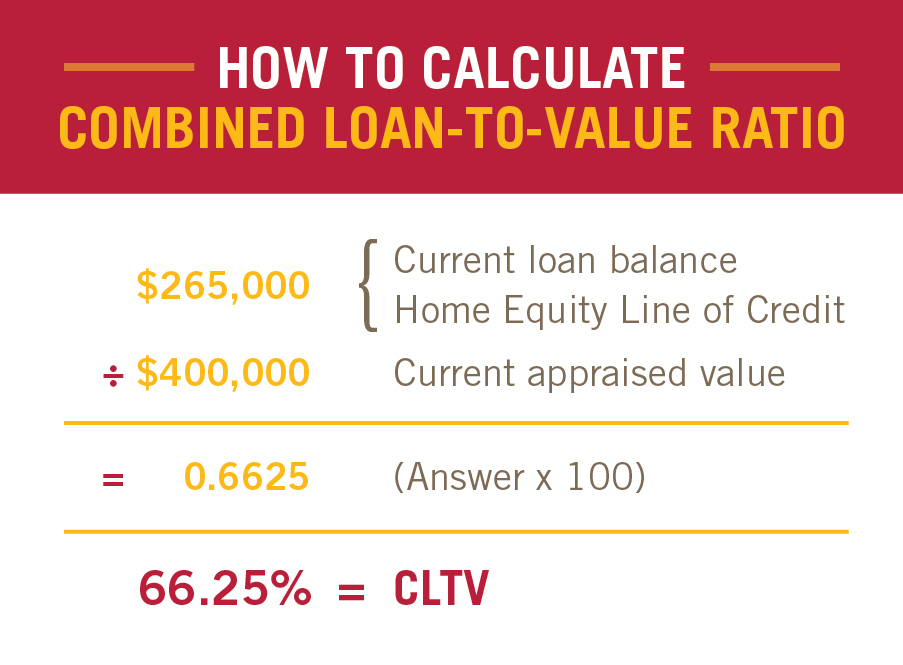
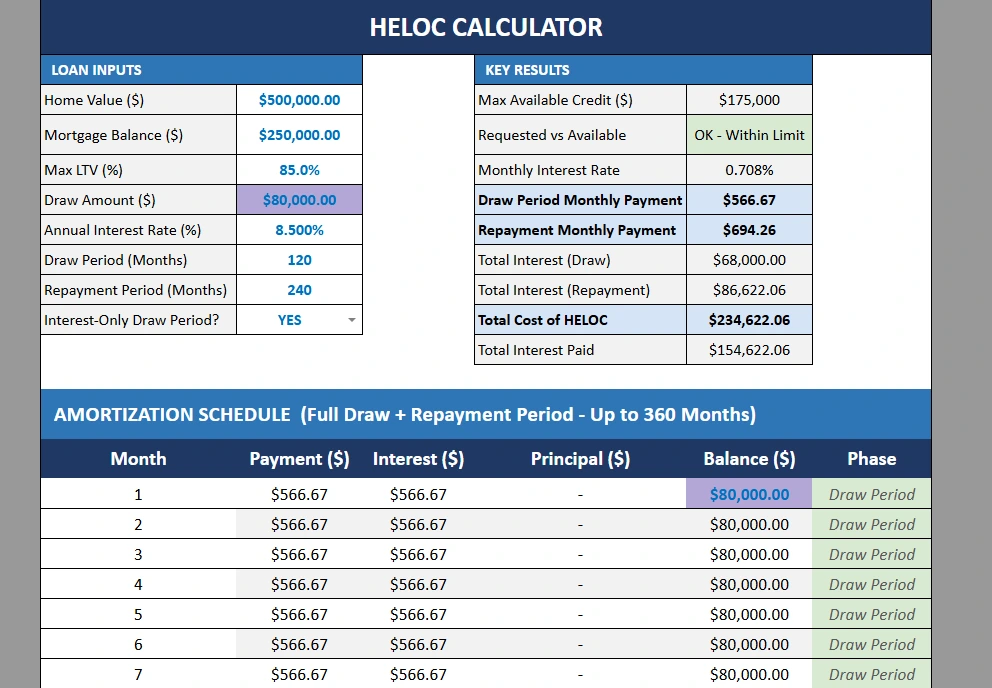
A HELOC LTV calculator figures out how much you can borrow against your home using a straightforward math formula, but the details matter more than people realize. You take your home's current market value, multiply it by the lender's maximum loan-to-value percentage, and subtract whatever you already owe on your primary mortgage. The remainder is your available HELOC credit line. Most lenders cap HELOC LTV at 80 to 90 percent combined. So if your house is worth $400,000 and you owe $250,000 on your mortgage, a lender with an 85 percent max LTV would allow a total borrowing of $340,000 against the property. That leaves $90,000 in available HELOC space after subtracting your existing mortgage balance. Simple enough on paper.
Using a Heloc Ltv Calculator Step by Step
The calculator itself is usually free online and takes about three minutes to run through once you know what numbers to plug in. Here is the typical flow. First, you need a reliable estimate of your home's current value. Zillow or Redfin estimates are decent starting points, but they lag behind reality by a few months in most markets. If you recently renovated your kitchen or replaced the roof, those sites won't reflect that yet. Call your county assessor or pull a Comparative Market Analysis from a local agent instead. It takes twenty minutes and is usually more accurate. Next, enter your exact mortgage balance. Check your most recent statement or log into your servicer's website. Do not round that number. If you owe $187,432, enter $187,432. Rounding to $187,000 shifts your available credit by over four hundred dollars, which sounds small until you are sitting across from a loan officer who has the exact figure in front of them.
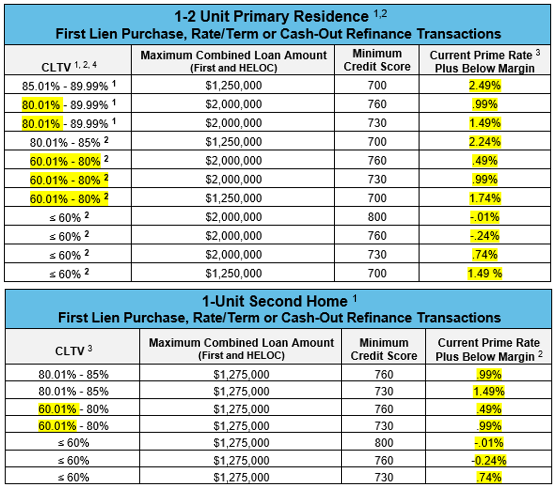
Then pick the maximum LTV percentage your lender offers. Most mainstream banks sit at 80 to 85 percent for HELOCs. Some credit unions go up to 90 percent if you have excellent credit and a low debt-to-income ratio. A few online lenders push to 95 percent but charge significantly higher rates. Your Heloc Ltv Calculator should let you adjust this slider so you can compare scenarios side by side before committing to any lender. Subtract your mortgage balance from the maximum allowed loan amount. The result is your estimated HELOC availability. Double-check the math because calculators do not always handle trailing zeros correctly, and I have seen two or three produce wildly wrong outputs when the home value was entered with commas in certain formats. Finally, factor in closing costs and annual fees. A HELOC from a big bank usually runs $300 to $700 in closing costs, while credit unions often waive them entirely. Annual fees range from zero to $75. These details rarely appear in a basic calculator, so you will need to look them up separately on the lender's fee schedule.
Get the Full Details
The Hard Part: When Calculators Miss the Mark
I ran into a real problem last year with a client who had a secondary mortgage from a hard money lender. The Heloc Ltv Calculator showed her roughly $60,000 in available credit based on her property value and primary mortgage balance. Her actual available credit came back zero. The reason was that the calculator only asked for one mortgage balance, and the hard money loan was never entered. She ended up walking away with nothing despite thinking she had six figures in room. Always include every lien against the property in the calculator input. Home equity loans, second mortgages, mechanic's liens, even unpaid property tax liens in some cases. One missed lien can erase your entire available line. This is the single most common error I see, and it happens because most free calculators only have one field for mortgage balance. Another thing nobody warns you about is the draw period interest rate structure. Most HELOCs use a variable rate tied to the prime index. When rates move, your payment moves. A Heloc Ltv Calculator will show you the maximum amount you can pull, but it will not tell you what your monthly payment looks like at the current prime rate plus the lender's margin, which typically adds 2.75 to 4.25 percentage points. Before you apply, run a payment projection using today's prime rate, not the promotional rate the lender mentions in their ad.
When a Heloc Ltv Calculator Should Not Be Your Only Tool
Online calculators assume your home is the only collateral and that the lender will accept the maximum LTV. Neither assumption holds up in practice. If you have a thin credit file or recent late payments, the lender may offer you a lower LTV tier regardless of what the calculator suggests. Some underwriters also adjust the property value downward by 5 to 10 percent compared to automated valuations, which can shrink your available credit substantially. If you are carrying significant consumer debt or student loans, your debt-to-income ratio may disqualify you before the LTV calculation even comes into play. The calculator does not account for this. Pre-qualification with a lender takes fifteen minutes and gives you a realistic sense of what you will actually get approved for, which is more useful than any free calculator result. There is also the appraisals issue. In markets where home values have shifted sharply in the past twelve months, lenders will require a full appraisal rather than relying on automated valuation models. That adds $400 to $700 to your process and introduces the risk that the appraisal comes in below your expected value. I had a borrower in Boise last spring whose online estimate was $520,000. The appraisal came back at $475,000. His HELOC availability dropped by nearly $15,000 because the lender used the lower appraised value in the LTV calculation.
What to Do After You Get Your Heloc Ltv Calculator Result
Use the estimate as a planning number, not a guarantee. Shop at least three lenders and request formal pre-approvals so you can compare actual offered rates and fees. Bring your recent mortgage statement, a property tax record, and a list of any second liens to every meeting. Lenders will verify these independently, and having the paperwork ready speeds up the underwriting process significantly. If the calculator shows you have very little available credit, do not apply blindly. Request a revised property valuation from your lender if you believe the estimate is outdated, or consider paying down your primary mortgage balance first to free up HELOC capacity. Even a few thousand dollars in extra principal payment can shift your LTV enough to unlock a meaningful amount of additional credit.