How HELOC Minimum Payments Actually Work (And Why Your Calculator Might Lie to You)
Most people pick up a HELOC minimum payment calculator, punch in their balance and interest rate, and hit enter. The number that comes out is not what they owe. Not even close. The standard formula is straightforward enough — multiply your outstanding balance by the annual percentage rate, divide by 12 — but that is only the starting point, and stopping there will cost you money in ways you probably do not expect. I spent years working in mortgage servicer operations before moving to consumer lending. I ran into a case last year where a borrower was using a free online Heloc Minimum Payment Calculator that ignored the draw period amortization rules. The tool spat out a $430 monthly payment. The actual minimum came to $682 because the servicer's spreadsheet included both interest and a small principal component tied to the original line structure. The borrower had been underpaying for 18 months straight without noticing, and by the time it came up on a routine audit, they were already behind on the principal portion that was quietly accumulating. The fix was manual, took three business days, and required pulling the original note language because the standard calculator templates do not account for hybrid amortization schedules that some lenders still use.Using a Heloc Minimum Payment Calculator Correctly
To get a useful number from any calculator, you need the right inputs. Your outstanding balance is not always the same as your current available credit. Some calculators ask for "total credit line" which is completely wrong for this purpose. You need the current draw balance, which you can find on your most recent statement under the current period's unpaid principal. The annual percentage rate matters, but you should verify whether your lender charges a variable or fixed rate on the HELOC. Most are variable, tied to the prime rate minus or plus a margin. If your rate has changed recently, do not plug in last year's rate. Pull the current APR from your monthly statement or call the servicer. A one-point difference on a $50,000 balance changes the monthly interest by roughly $42, which compounds fast over a full draw period. Here is the basic math that most good calculators use internally:
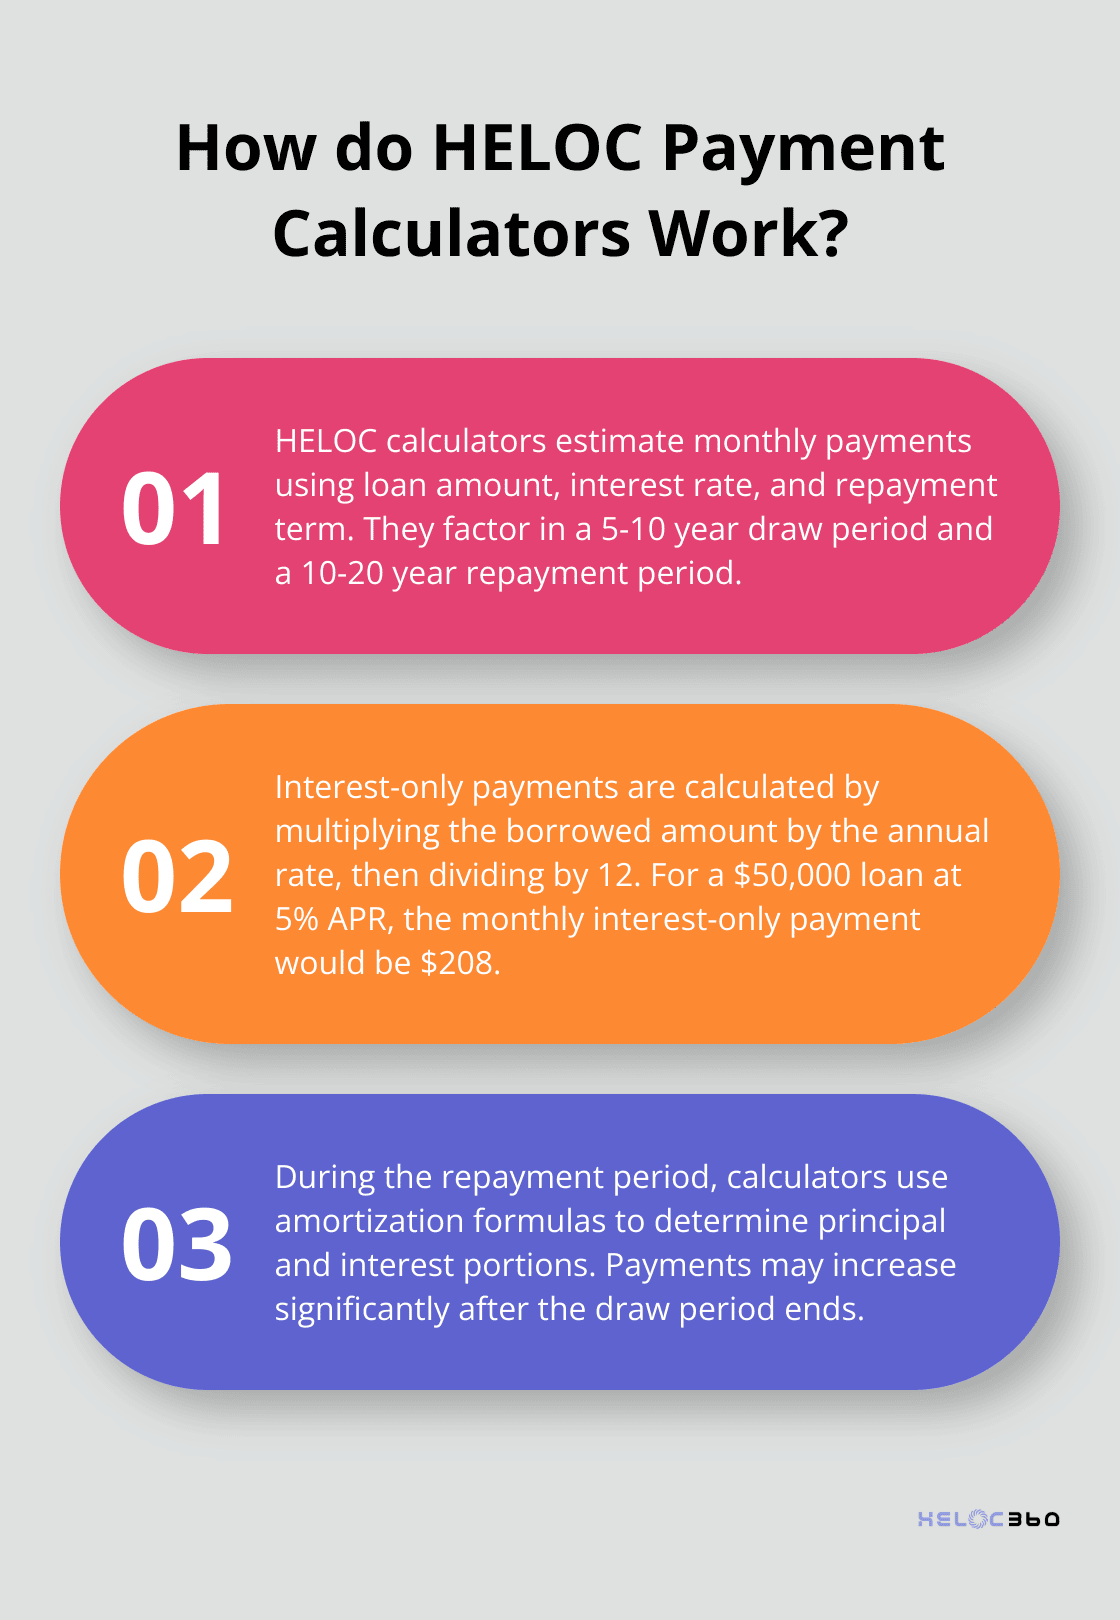
Monthly interest payment = (Outstanding balance × Annual percentage rate) ÷ 12 Some lenders add a small principal component. Others do not during the draw period. That distinction changes the output significantly. A $60,000 balance at 8.5% APR gives you $425 in monthly interest alone. If your lender requires a 1% principal payment on top, you are looking at $600+ per month, not $425.
What the Calculators Leave Out
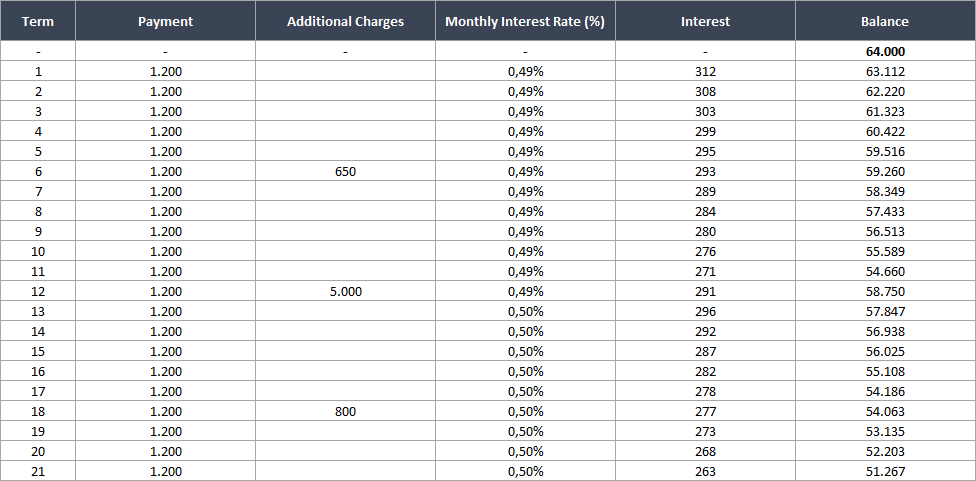
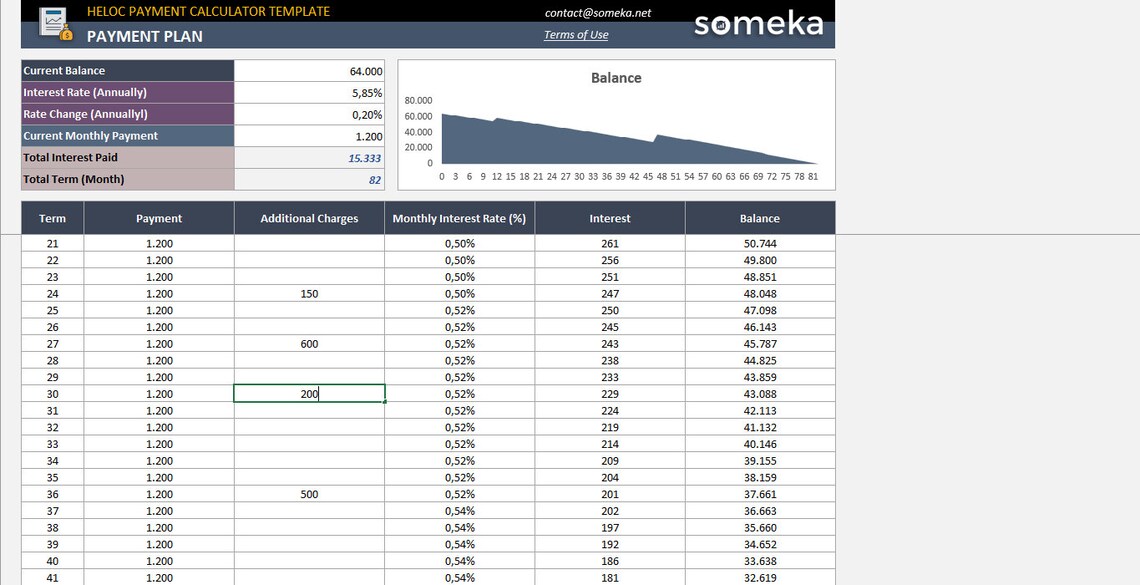
This is where the real world gets messy. Most free online tools ignore several factors that directly affect your actual minimum payment obligation. Interest-only vs. full amortization periods. During the draw period, which typically lasts 5 to 10 years, many HELOCs require only interest payments. But some lenders structure the minimum to include a small principal component even during draw. After the draw period ends and the repayment period begins, the payment jumps dramatically because the entire remaining balance must be paid off over the remaining term. A calculator that assumes interest-only for the full life of the loan will give you a number that could be 40% too low once repayment starts. Annual adjustments. Your rate can change once per year on most HELOCs. A calculator that uses today's rate will be inaccurate next year if the prime rate moves. I recommend building a simple spreadsheet that tracks the projected rate adjustment and recalculates your minimum monthly each time the rate changes. It takes about five minutes per adjustment and prevents the surprise of being short on payment by a couple hundred dollars.
Get the Full Details
Payment frequency quirks. Some servicers calculate minimums based on a 360-day year while others use 365. The difference is small on individual payments but noticeable over a year. On a $75,000 balance at 9% APR, the gap between 360-day and 365-day calculation is roughly $15 per month, or about $180 annually. It matters if you are budgeting tightly.
When a Calculator Fails You Entirely
There are scenarios where no online Heloc Minimum Payment Calculator will give you a reliable answer. The most common is when your lender uses a proprietary formula that blends interest, a minimum floor payment, and a principal component in a way that does not match standard textbook calculations. I encountered this with a regional bank in Ohio where the minimum payment was defined as the greater of either the calculated interest or $50, whichever was higher. That $50 floor meant that even on a $5,000 balance, your minimum was $50, not the $37.50 the formula would suggest. A standard calculator would have understated the obligation by 33%. Another edge case is when you have taken a lump-sum draw during the period. Some lenders apply different terms to new draws versus old ones. Your statement should break these out, but the calculator you found online almost certainly does not. The most practical workaround I have found is to request your servicer's payment calculation worksheet directly. Most larger servicers have an internal document that shows exactly how they derive the minimum. It is not glamorous, but it eliminates guesswork. If you cannot get the worksheet, call the servicer and ask for the exact formula used to compute the minimum payment. They are required to disclose this under Regulation Z.
What I Actually Do Now
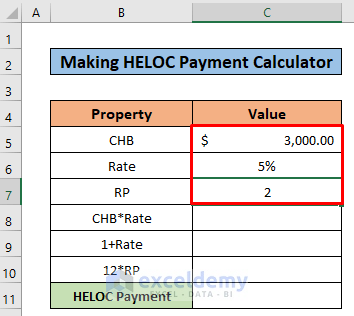
I stopped relying on calculators entirely a few years ago. I built a simple Excel model that pulls my current balance and rate, applies the interest calculation with my servicer's actual day-count convention, adds the principal component if applicable, and then cross-checks the result against what my statement shows each month. If the numbers match, I know the model is accurate. If they do not, I flag it and contact the servicer to resolve the discrepancy before it becomes a payment shortfall. The model takes about two minutes to update each month and has saved me from three separate payment surprises in the past two years. The biggest one was a $210 shortfall that went unnoticed for six months because the online calculator I was using had not been updated after a rate change. The servicer eventually caught it, but the interest and fees on the underpayment added up to nearly $400 in penalties. If you want a quick answer, use a calculator. If you want to know what you actually owe each month without getting burned, verify the number against your statement or your servicer's documentation. The extra ten minutes of work prevents the much larger headache of a payment deficiency that compounds over time.