Understanding How Your HELOC Payment Actually Works
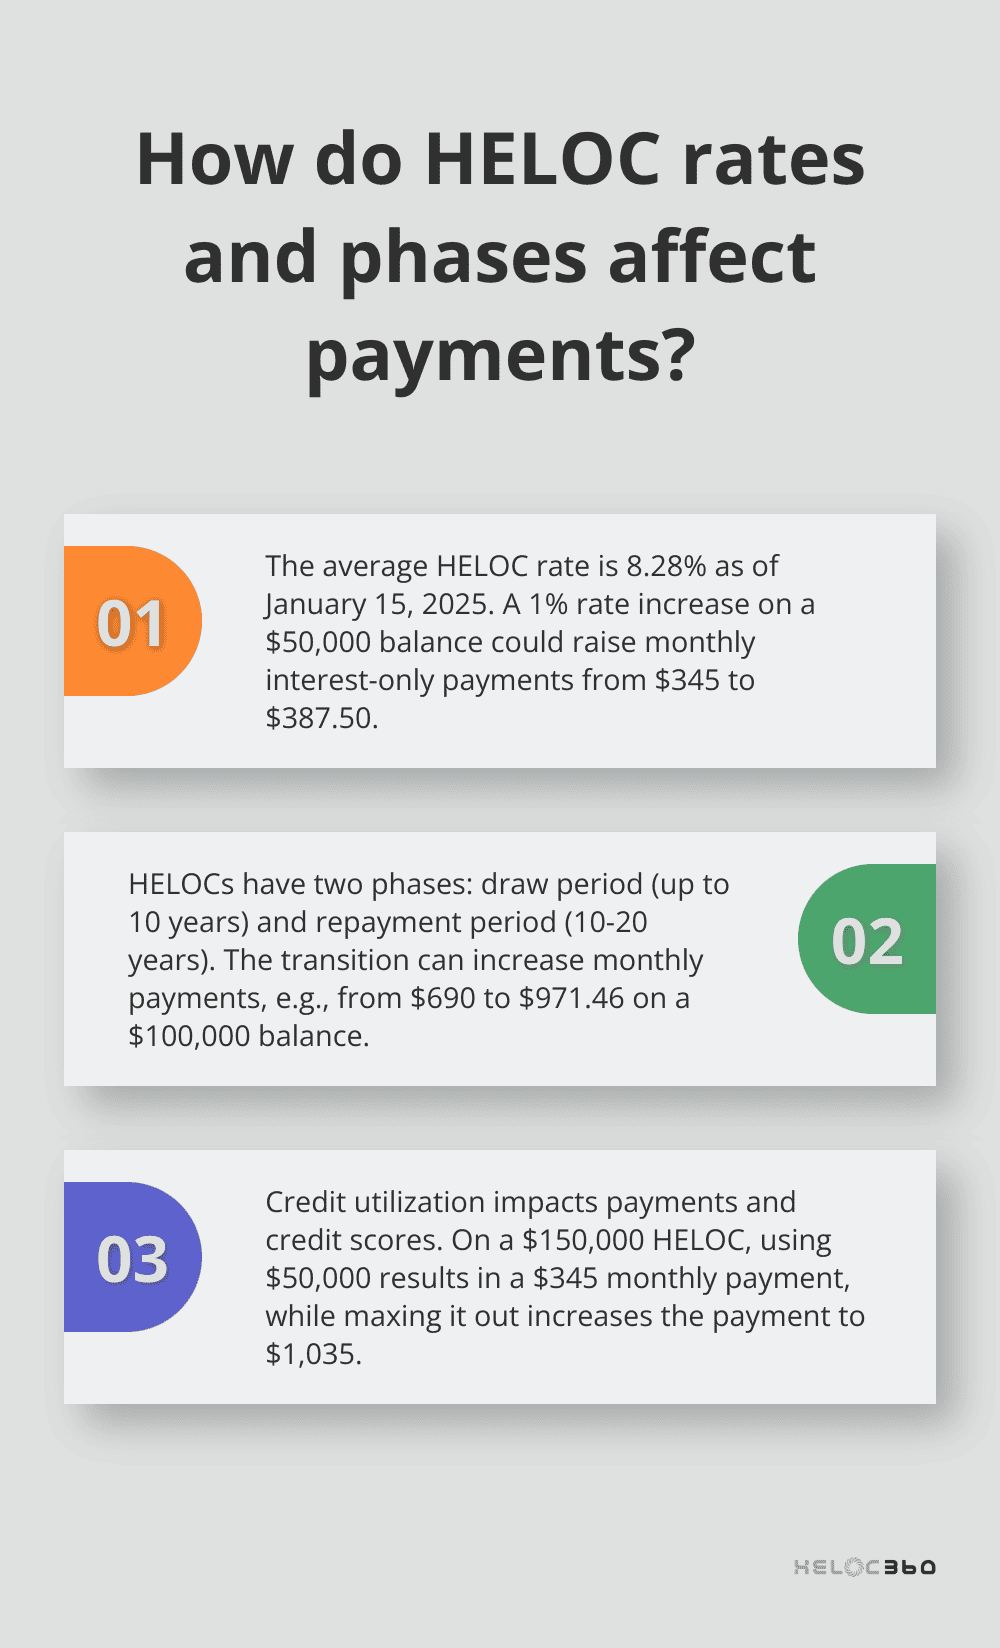
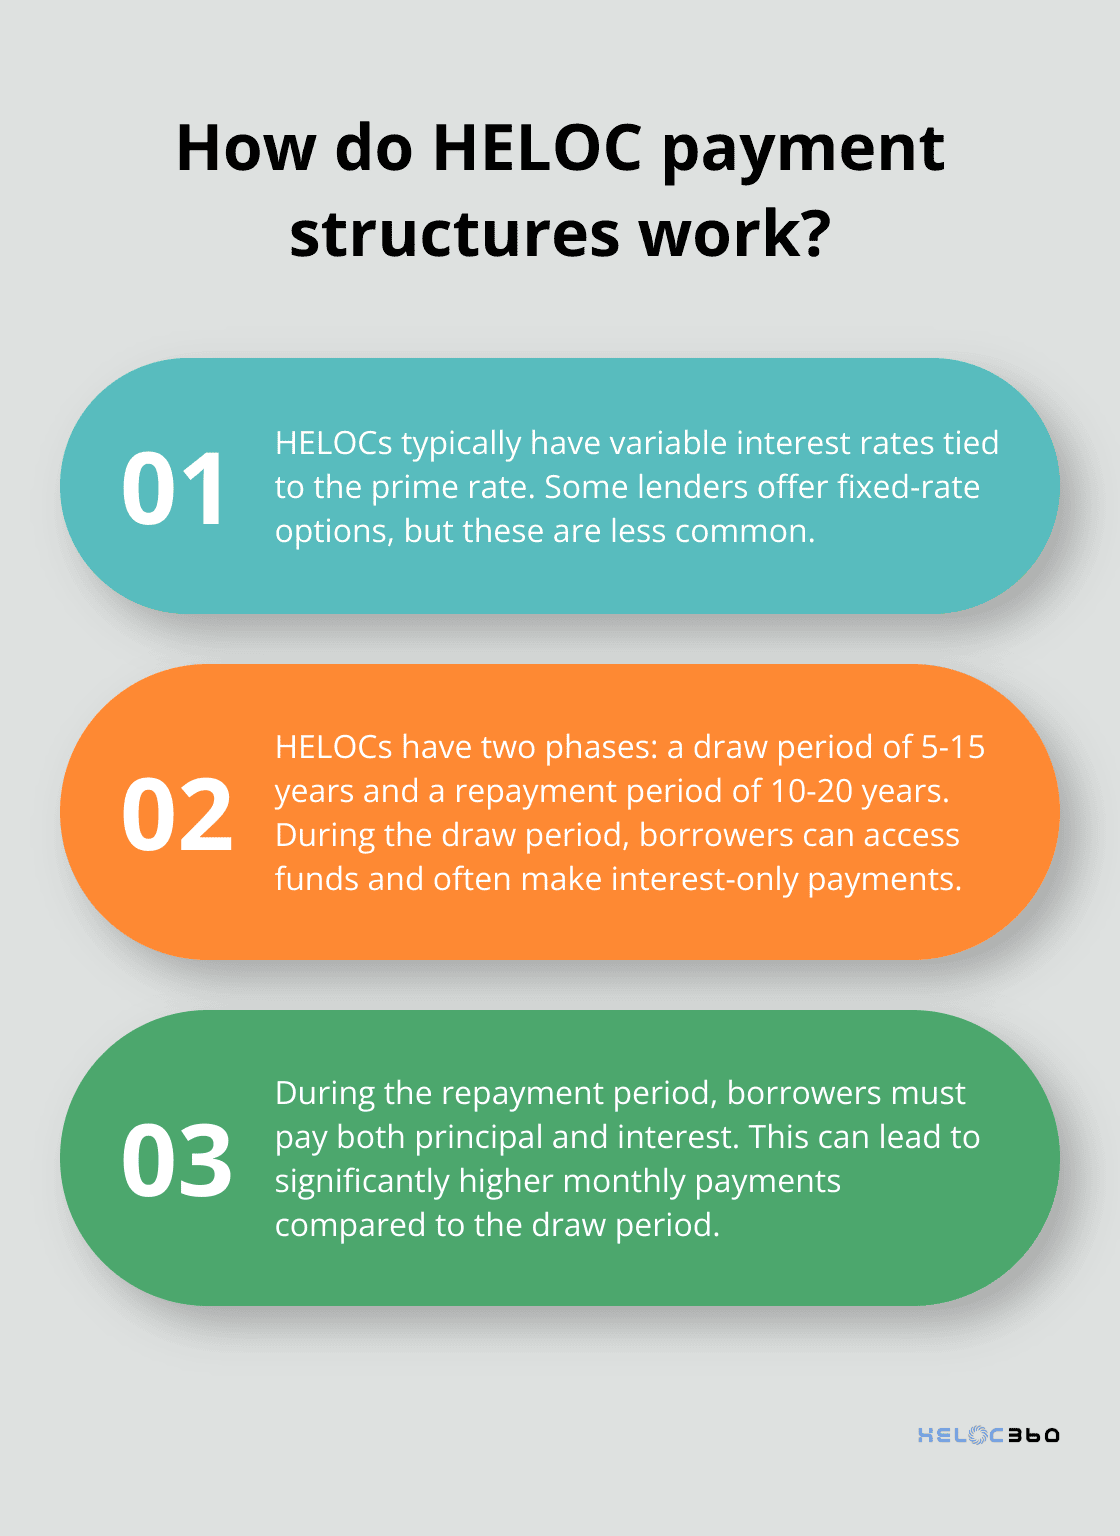
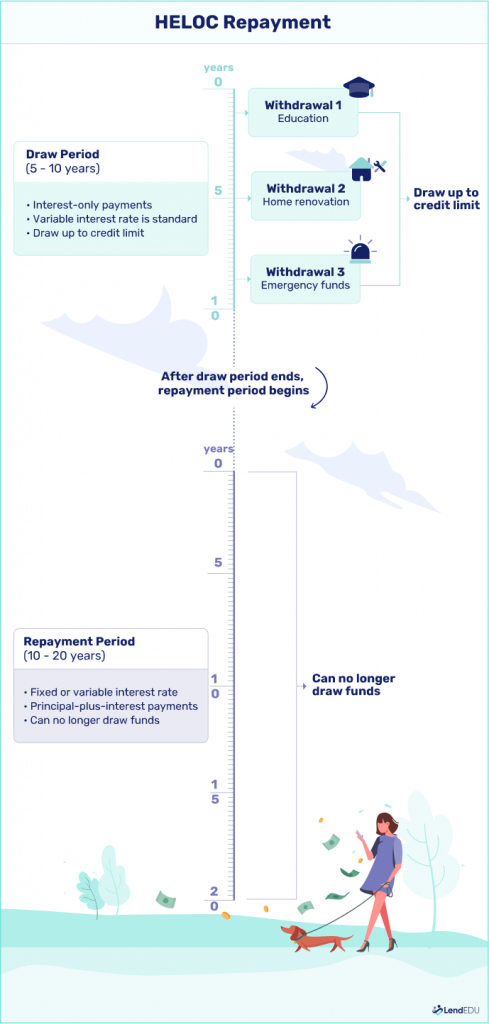
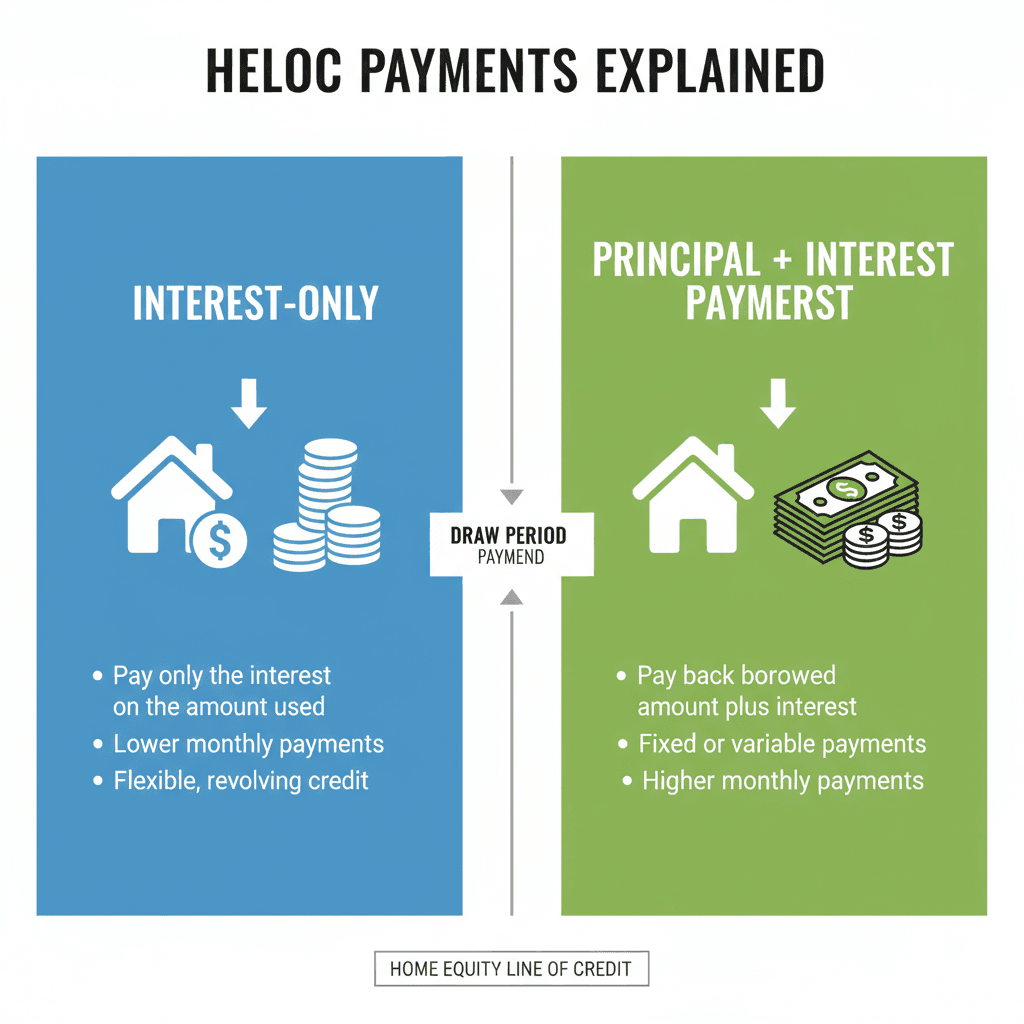
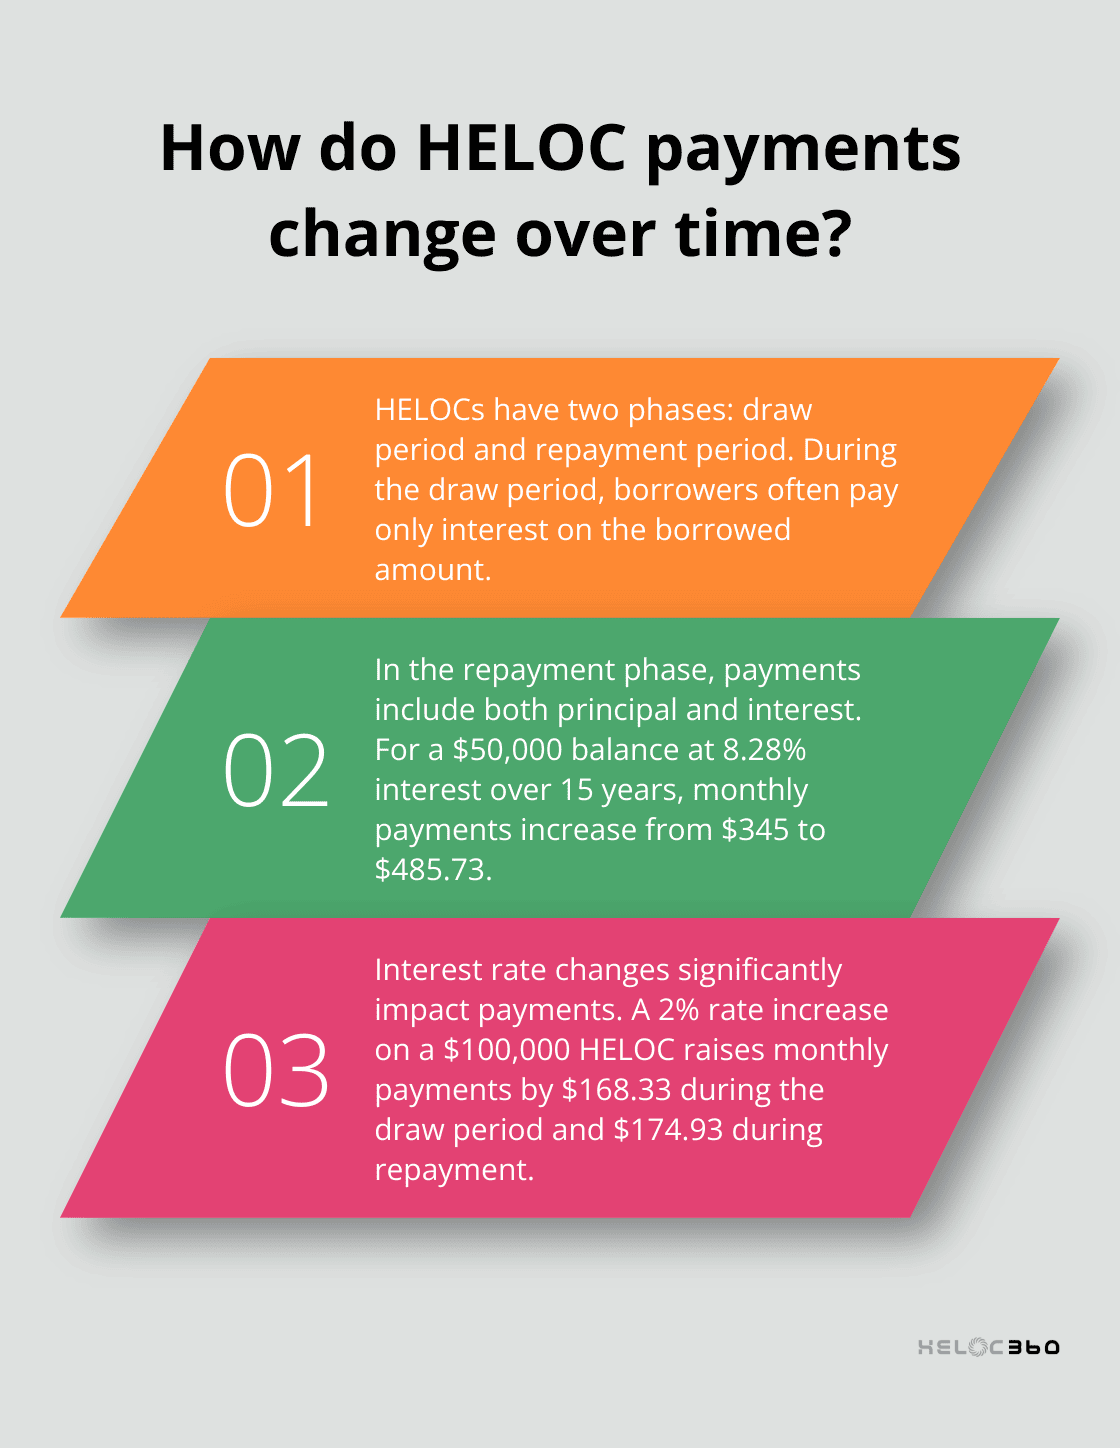
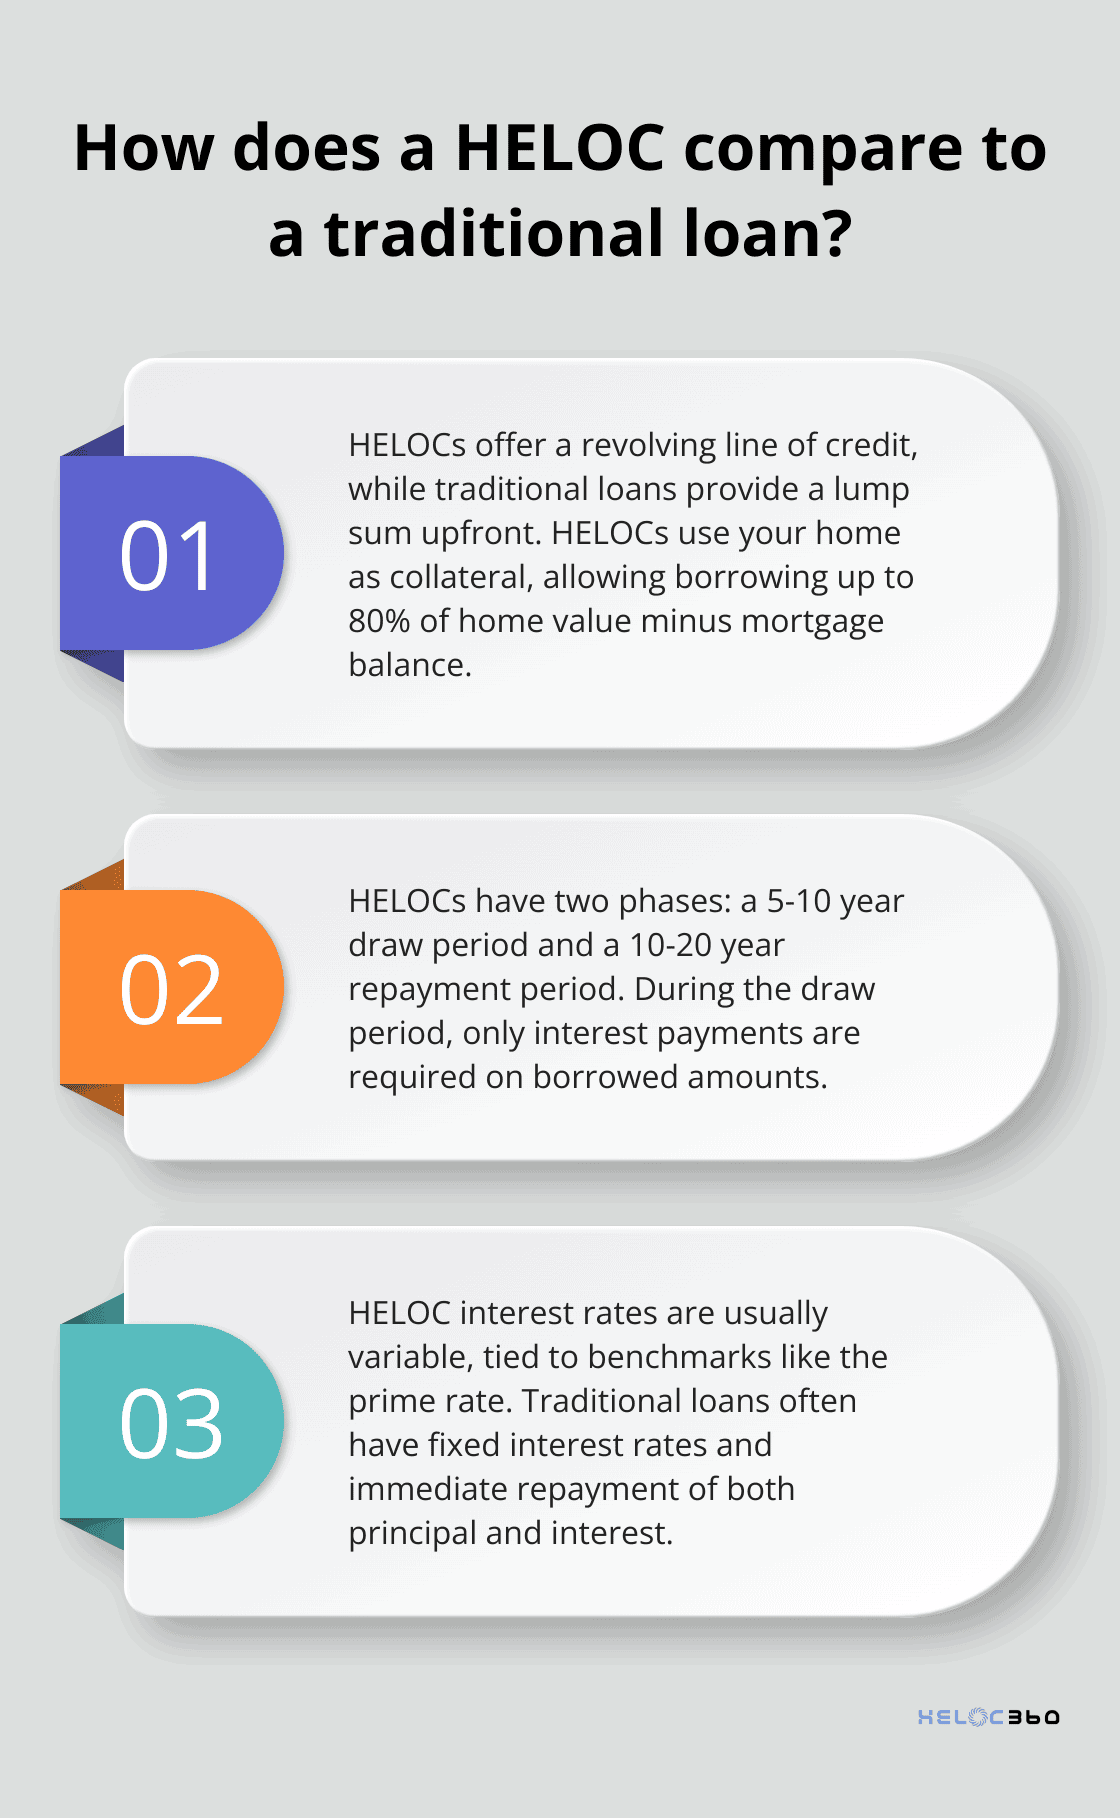
A HELOC, or Home Equity Line of Credit, is a revolving loan backed by your home's equity. The payment structure is fundamentally different from a standard mortgage, and that difference is where most people get tripped up. I have dealt with this from both sides — advising clients and managing my own — so I will explain exactly how it functions and where the traps are. The core distinction between a HELOC payment and a traditional mortgage payment is the two-phase structure. During the draw period, which typically lasts 5 to 10 years, you are only required to make minimum payments based on the amount you have actually borrowed, not the full credit line. Most lenders calculate this as interest-only. After the draw period ends, the repayment period begins, usually spanning 10 to 20 years, and your payment recalculates to include both principal and interest on the remaining balance. This is the moment where people experience what the industry calls payment shock. Here is the mechanism: Your lender sets a maximum credit limit, say $80,000, based on your home's appraised value minus any existing mortgage balance. You draw from that line as needed — maybe $30,000 for a renovation. Your monthly Heloc Payment during the draw period is calculated on the $30,000 outstanding balance at your variable rate. If you draw another $15,000 later, your payment jumps accordingly. If you pay down $20,000, your next payment drops. It behaves like a credit card secured by real estate, which is not a metaphor — it is functionally how the product operates.
Interest is typically computed daily and charged monthly using an average daily balance method. Your statement will show the daily balance throughout the month, the interest rate applied, and the minimum payment due. Most lenders require a minimum payment of either $50 or 1% of the outstanding balance, whichever is greater, during the draw phase. This means even if you only drew $10,000 at a 9% rate, your minimum payment would be roughly $75 per month. That figure becomes critical when you transition into the repayment phase.
How to Calculate Your Actual Monthly Obligation
The most common mistake I see is assuming your payment stays constant. It does not. I had a client last year who drew $60,000 during her 8-year draw period, made only interest payments, and then faced a repayment-period payment of approximately $720 per month on the remaining $55,000 balance — up from her $450 monthly interest-only payment. She had budgeted for the lower amount and was nearly 90 days delinquent before we restructured. To calculate your payment accurately, you need three data points from your loan documents: your current outstanding balance, your annual percentage rate (APR), and the number of months remaining in your repayment period. For the draw period, the calculation is straightforward — multiply your balance by your APR and divide by 12. So $50,000 at 8.5% APR divided by 12 equals roughly $354 per month in interest. For the repayment period, it becomes an amortization calculation. Using the same $50,000 balance with 15 years remaining at 8.5% APR, your monthly payment would be approximately $489. That number includes principal and interest and remains fixed for the life of the loan unless your rate adjusts. If your HELOC has a cap on rate changes — most do, typically 2 percentage points per adjustment period — your payment could shift upward or downward at each adjustment date, which further complicates budgeting.
Get the Full Details
I recommend using an amortization calculator and running both scenarios — draw period and repayment period — side by side before you ever close on the line. Do not rely on the lender's estimate. Their projection assumes you will draw the full available amount and never pay it down early, which is not how most people use the product.
Common Pitfalls That People Miss
The first pitfall is the reset shock. Lenders are not required to warn you explicitly about the payment increase that occurs when the draw period ends. They will include the terms in your closing documents, buried somewhere in section 7 or 8 of a 40-page packet. I have spent more hours than I care to admit explaining to homeowners that their "minimum payment" of $380 is about to become $820 because they ignored the amortization schedule attached to their note. The second pitfall is the variable rate component. Most HELOCs use an index — usually the prime rate — plus a margin set by the lender. When the Federal Reserve raises rates, your payment goes up automatically. There is no notice period that guarantees you time to adjust. In 2022 and 2023, borrowers with HELOCs tied to the prime rate saw their payments increase by 3 to 4 percentage points in a single year. That is not hypothetical. I tracked this with three separate clients who all underestimated the impact because they budgeted using the original rate shown in their promotional materials. A third issue that rarely gets discussed is the lock-in period. Some lenders offer a fixed-rate option during part of the draw period, where you convert a portion of your variable balance into a fixed-rate installment loan. This can be useful if you want payment certainty, but the trade-off is that you lose access to that converted amount. You cannot re-borrow it. I had a situation where a borrower locked $25,000 at 6.5% fixed, then needed an additional $8,000 for an unforeseen medical expense six months later. He could not access it because it was no longer part of the revolving line. His options were to take a new loan at current rates — which were higher — or pay out of pocket. It was a costly lesson in liquidity management.
Practical Steps to Manage Your HELOC Payment
Start by pulling your original disclosure documents. Locate the section labeled "Repayment Period" and "Payment Adjustment Schedule." Write down the exact date when your draw period ends. Set a calendar reminder 18 months before that date. You need time to evaluate whether refinancing, paying down the balance aggressively, or converting to a fixed-rate structure makes sense for your situation. During the draw period, consider making principal payments even though they are not required. Paying down $5,000 this year reduces your interest charge going forward and lowers your repayment-period payment by roughly $40 per month. It is free money on the table if you plan to stay in the home long enough to recoup any prepayment considerations. Most HELOCs do not have prepayment penalties, but verify this in your note before assuming it. If your lender offers a payment calculator on their website, use it with your actual balance rather than the maximum credit line. The default display often shows the worst-case scenario — maximum draw, minimum payment, variable rate at the cap. That will alarm you unnecessarily if you are only using half the available credit. I found that the internal tool on my lender's portal let me input a custom balance and showed both the current interest-only payment and the projected repayment-period payment. This single step saved me from a $200-a-month budget shortfall when I refinanced my primary mortgage and adjusted my HELOC draw expectations.
Track your rate adjustment dates. Most HELOCs adjust monthly or quarterly. Mark each adjustment on your calendar and compare your new payment to the previous one. If the increase is significant, contact your lender to discuss whether a rate lock or partial conversion is available at that time. Some lenders will offer a rate lock for a fee — typically 0.25 to 0.5 percentage points — which can provide stability during volatile rate environments.
When a HELOC Is the Wrong Tool
A HELOC is not a substitute for a traditional home equity loan if you need a large, one-time sum of money. A home equity loan gives you a fixed amount, fixed rate, and fixed payment from day one. The trade-off is less flexibility — you cannot draw additional funds after closing. But your payment is predictable. For a $60,000 project with a known timeline, a home equity loan is often the safer choice. The HELOC structure rewards disciplined users who understand the mechanics and have the cash flow to manage variable payments. It penalizes everyone else through confusion and payment shock. I also see people use HELOCs as a catch-all solution for short-term cash needs — consolidating credit card debt, funding a vacation, covering an emergency expense. The tax implications deserve attention here. Interest on a HELOC is only tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Using it for other purposes eliminates the deduction. I worked with a client who thought his $40,000 in HELOC interest was deductible because he used it to pay off high-interest credit cards. The IRS disallowed the entire deduction. He ended up owing an additional $3,200 when he filed. Make sure you understand the tax treatment before you close. The fundamental reality is that a HELOC payment is only as manageable as your understanding of its structure. The product itself is straightforward — draw what you need, pay interest during the draw period, amortize during the repayment period. The complexity comes from the variable rate, the two-phase design, and the tendency for people to treat it like a permanent financing solution when it was designed for short-to-medium-term needs. If you go in knowing exactly what each phase entails, you can use it effectively. If you do not, you will learn the hard way, usually while dealing with a lender who already has their procedures in place for handling the transition.