How to Actually Use a HELOC Payment Calculator Without Getting It Wrong
You pull up a Heloc Payment Calculator Free tool because your lender sent a PDF full of amortization tables and you need to understand what's happening to your monthly payment when rates reset. The calculator looks simple enough. Input your outstanding balance, pick the draw period or repayment period, throw in the current variable rate, and hit calculate. But that's where most people start making mistakes that cost them thousands over the life of the loan. First, let me tell you about the problem I ran into last November. A client came to me with a second lien of about $85,000 on a property in Colorado. The bank's online calculator showed her minimum payment as $680 per month during the draw period. She was comfortable with that. Then the rate ticked up from 7.25% to 8.75% between quarters. Her payment jumped to $847 overnight. She hadn't budgeted for the volatility. The calculator she'd been using only showed static numbers. It didn't model rate changes between periods. That's a critical gap I want to address before we go further.
Getting Started with Heloc Payment Calculator Free
The basic mechanics are straightforward. A HELOC works differently than a traditional mortgage, and that difference matters for the calculator you choose. During the draw period, which typically runs 5 to 10 years, you're only required to pay interest on whatever you've actually drawn. After that, you enter the repayment period, usually another 10 to 20 years, and the payment recalculates based on the remaining balance. The payment jumps significantly because you're now paying principal plus interest instead of just interest. Here's what you actually need to enter into any calculator, not just the free ones: Outstanding balance: This is the amount you've drawn so far, not your total credit limit. If you have a $100,000 HELOC limit but you've only used $42,000, enter $42,000. Entering the full credit line will give you a wildly inflated payment number that has nothing to do with your actual obligation.
Interest rate: This should be your current rate, not the initial teaser rate your lender advertised. Check your most recent statement. The opening rate is often 1 or 2 points below the current index rate plus the lender's margin. Lenders adjust these quarterly or semi-annually depending on the index they're tied to, usually the Prime Rate. Draw period remaining: Count the months left in your interest-only phase. This determines whether you're calculating a minimum payment or a fully amortizing payment. Repayment term: Once the draw period ends, how many months do you have to pay off the balance? Some lenders default to 180 months. Others use 240. This number dramatically affects your payment calculation.
Get the Full Details
Let me walk through a real example. Say you've drawn $60,000 and your current rate is 8.5%. You have 3 years left in your draw period, then 15 years to repay. During those final 36 months of the draw period, your monthly payment is just interest: $60,000 times 0.085 divided by 12 equals $425. Simple enough. Then day one of the repayment period, the calculator re-estimates based on 180 months at 8.5%. That new payment jumps to about $571. Not a huge jump in absolute dollars, but it's a 34% increase, and that's the kind of thing that catches people off guard. Now here's something most free calculators won't tell you, and this is where it gets useful to understand what's actually happening under the hood. The payment recalculation at the end of the draw period uses your remaining balance but applies it across the full repayment term as if you never made any extra payments during the draw phase. So if you paid down $20,000 of principal early in the draw period, that reduced balance does carry forward, but the calculator assumes you'll pay it off on schedule during repayment regardless. That assumption is baked into the formula.
Common Pitfalls That Mess Up Your Calculation
The biggest error I see people make is confusing their credit limit with their balance. I had someone fill out a calculator with their full $150,000 limit and then wonder why the payment came out to over $1,200. They'd only drawn about $38,000. The calculator gave them a correct number for a completely different loan than they actually had. Another issue is ignoring the rate floor. Most HELOCs have a minimum rate, often 5% or 5.5%, regardless of where the index goes. If you're looking at a calculator during a rate-cutting cycle and the index drops below that floor, your payment won't decrease like the calculator might suggest. You need to find your note or loan estimate document and look for language about a rate cap or floor. It'll be somewhere in the fine print, usually section 4 or 5 of the Truth in Lending disclosure. There's also the compounding frequency to consider. Most HELOCs compound daily but bill monthly. A free calculator that assumes monthly compounding will give you a slightly different answer than your actual statement. The difference is small on a $50,000 balance — maybe $8 to $12 per month — but it adds up and it makes your planner look inaccurate if you don't account for it.
I encountered one edge case recently that I haven't seen addressed anywhere. A client had a HELOC with a payment ceiling feature, sometimes called a payment cap. The lender guarantees the payment won't increase by more than a certain percentage each period, even if the rate jumps. This is separate from the rate cap. When I ran the numbers through a standard Heloc Payment Calculator Free tool, the output was misleading because the calculator assumed full amortization at the new rate. The actual payment was locked at the ceiling. The workaround was to pull the lender's payment schedule document, which lists the specific maximum payment percentages by year, and model that manually instead of relying on the generic calculator.
When Free Calculators Fall Short
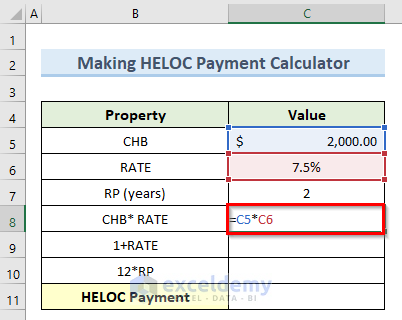
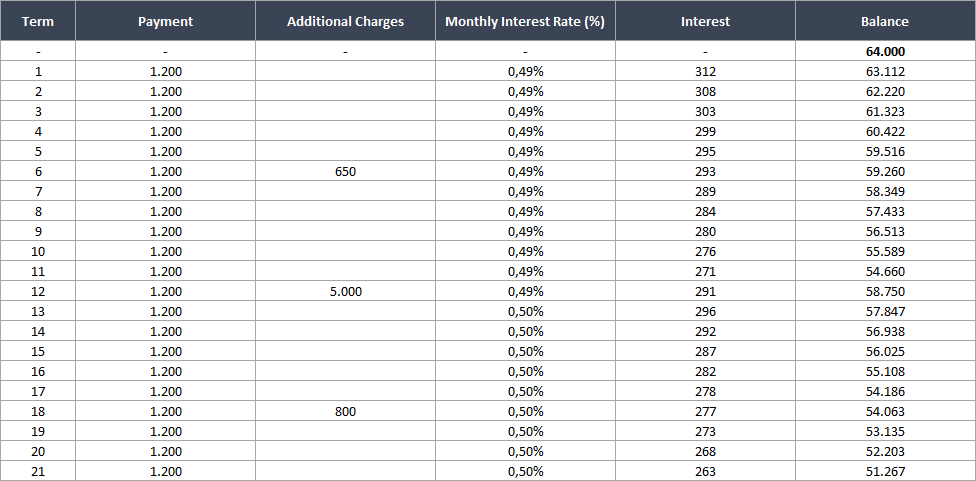
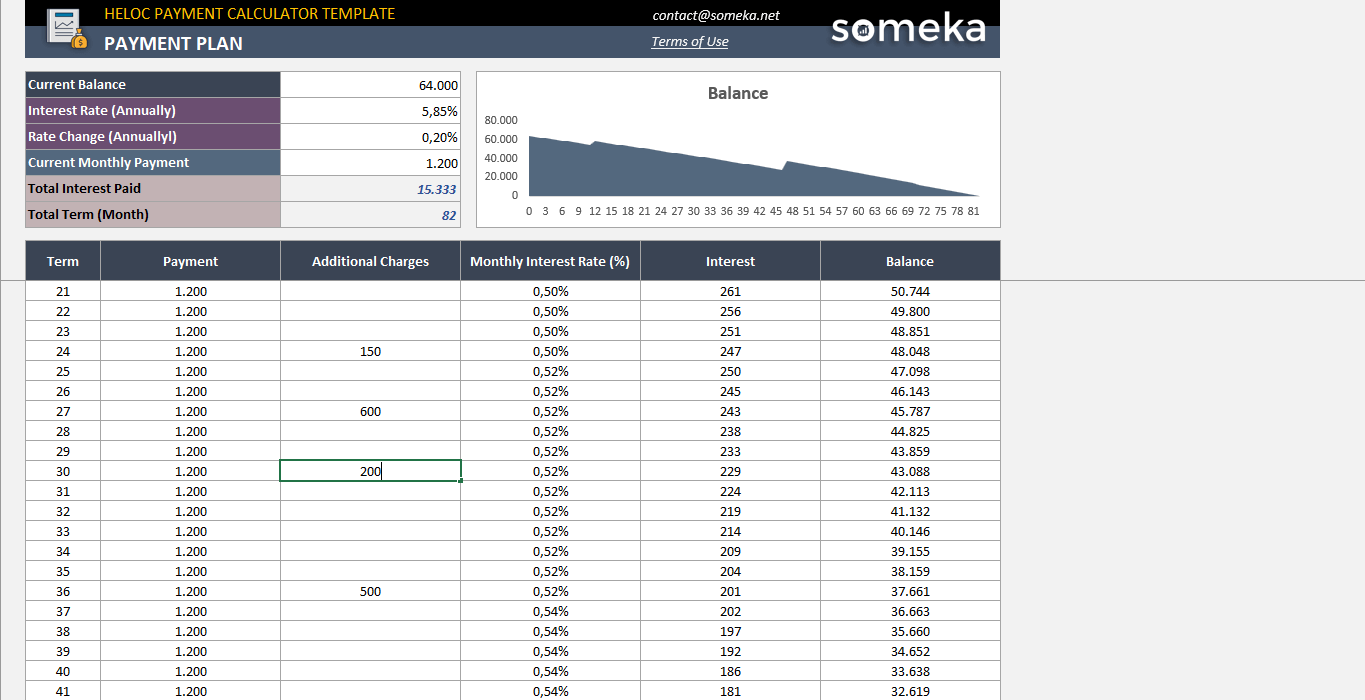
Free online calculators are fine for a rough picture. They're not fine if you're trying to plan for a rate change, model early payoff scenarios, or understand the exact payment in your repayment phase. The ones I tend to recommend are the ones that let you adjust the rate in real time and show you side-by-side scenarios. That way you can see what happens if rates go up another point, or if you throw an extra $5,000 at the balance next month. If you want something more accurate, you can build a simple spreadsheet. It takes about 15 minutes. Set up columns for the payment period, the remaining balance, the rate for that period, and the calculated payment. For the draw period, use the interest-only formula. For the repayment period, use the standard amortization formula: P equals r times B divided by 1 minus 1 plus r all raised to the negative n, where r is your monthly rate, B is your balance, and n is your number of remaining payments. Plug in your actual numbers and adjust for rate changes whenever they happen. One more thing that matters and most people skip: check whether your lender uses a 360-day or 365-day year for their daily interest calculation. It's a small detail, but it changes the monthly payment by a few dollars, and over 10 years that's a meaningful difference if you're comparing multiple lenders or trying to match your statement exactly.