Understanding HELOC Payment Estimators
Most people think a HELOC payment is straightforward. It's not. You're looking at a line of credit secured by your home, which means the payment structure changes depending on whether you're in the draw period or the repayment period. A Heloc Payment Estimator helps you model those numbers before you commit, but the results it gives you are only as good as the assumptions you feed into it. A HELOC operates in two distinct phases. During the draw period, which typically lasts 5 to 10 years, you can pull funds from your available credit line as needed. The minimum payment during this phase is usually calculated as interest-only on the amount you've actually drawn. Some lenders require a small percentage of the outstanding balance plus accrued interest. After the draw period ends, you enter the repayment period. At that point, the remaining balance gets amortized over the remaining term, and your payment jumps significantly because principal starts getting paid down alongside interest. The estimator takes your credit limit, the rate your lender quoted, how much you plan to draw, and which phase you're in to project your monthly payment. It's basically an amortization calculator with a draw-period twist layered on top. The formula isn't complicated, but the variables matter more than most people realize.
The Numbers Behind the Estimate
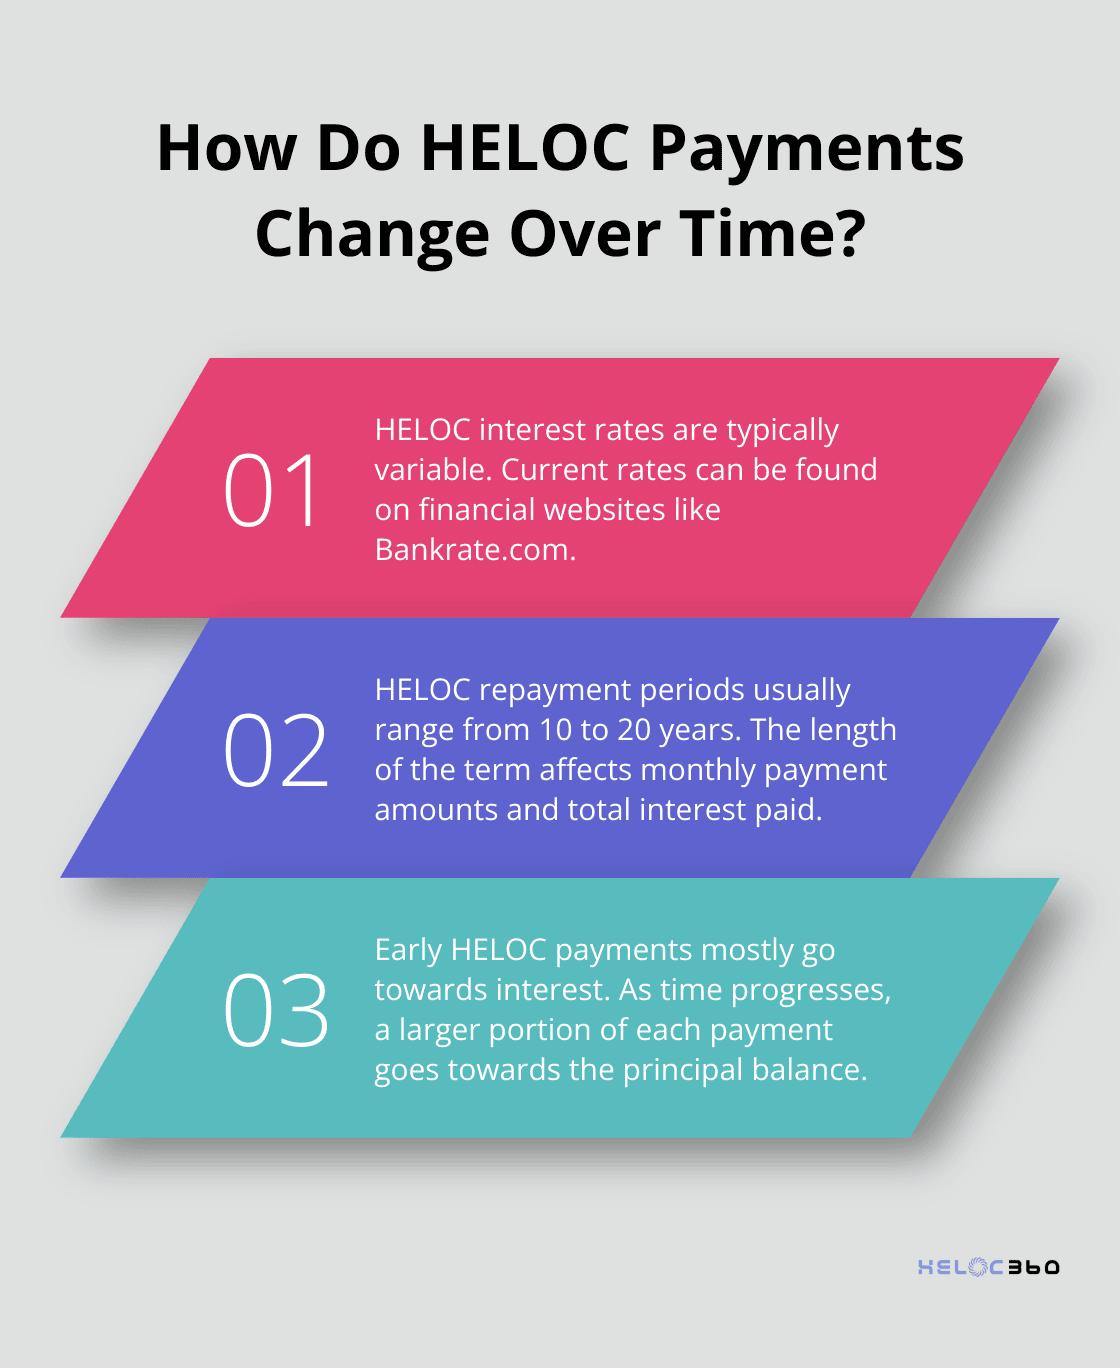
HELOC rates are variable, which is the single biggest complication. Most are tied to the prime rate with a margin added on, usually ranging from 0.5 to 2.5 percentage points above prime. If prime is 8.5 percent and your margin is 1.75 percent, your rate is 10.25 percent. That rate can float up or down whenever the Federal Reserve moves rates, and your payment moves with it. Here's how the calculation breaks down during the draw period. Take your outstanding balance, multiply it by your annual rate, then divide by 12 to get the monthly interest charge. That's your minimum payment in most cases. If you owe $40,000 at 10.25 percent, your monthly interest comes to about $341.67. That's it. No principal reduction. You could draw another $10,000 next month and your payment would recalibrate to reflect the new balance at the current rate. During the repayment period, the math shifts. Your remaining balance gets spread across the remaining months with compound interest applied each cycle. The formula becomes P × r × (1 + r)^n / ((1 + r)^n - 1), where P is your principal, r is your monthly rate, and n is your number of remaining payments. That same $40,000 balance over 15 years at 10.25 percent would produce a payment around $454 per month. Over 20 years, it drops to about $392. The longer the term, the lower the payment, but the more interest you pay in total. That tradeoff is never mentioned in the marketing materials.
A Problem I Ran Into With These Estimators
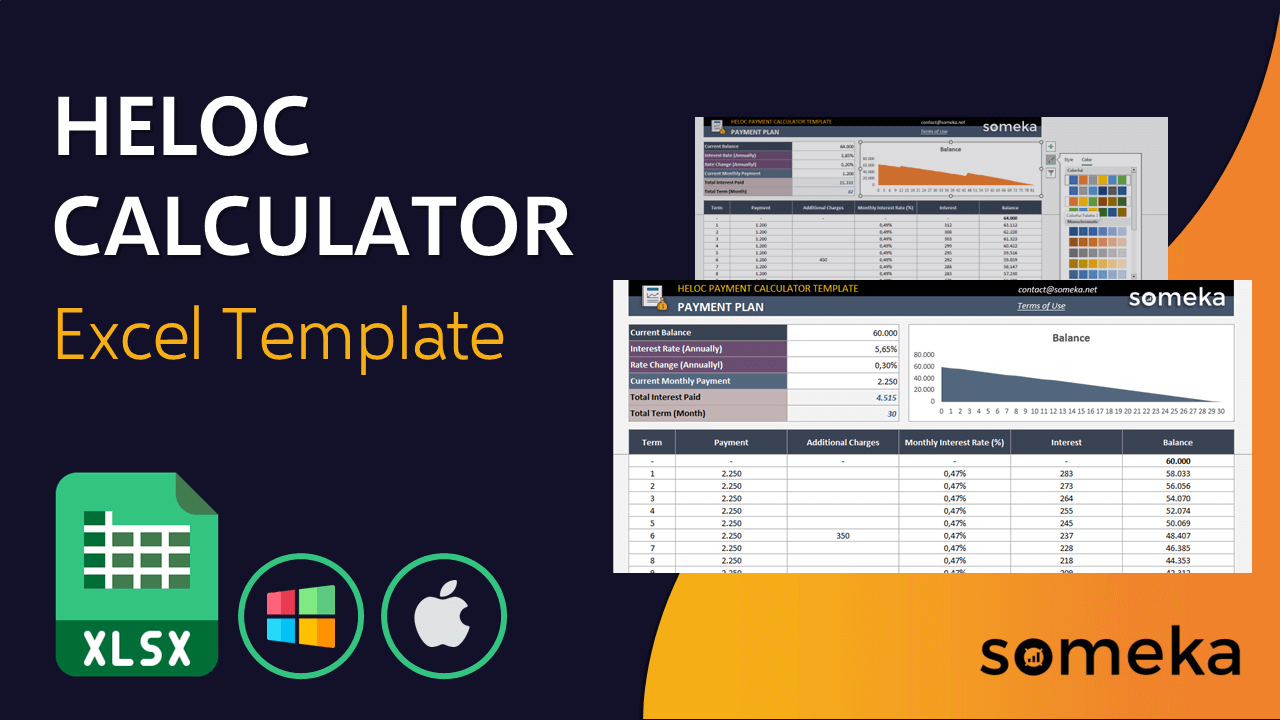
Several years ago, I was helping a client model their HELOC payments using an online estimator. The tool assumed they'd drawn the full credit limit upfront and stay in the draw period for the entire 10-year window. Their actual situation was completely different. They planned to use about 60 percent of the line initially and expected to ramp up usage gradually over the first two years. The estimator gave them a payment projection that was roughly 40 percent higher than what they'd actually owe for the first few years. More importantly, it didn't account for the payment shock they'd face when transitioning to repayment mode. The workaround was to build a year-by-year projection in a spreadsheet instead of relying on the one-size-fits-all calculator. I set up columns for each year showing: opening balance, draws during that year, ending balance, interest rate assumption, and minimum payment for the draw phase. Then I switched the formula to standard amortization once the draw period ended. It took about 20 minutes to build and gave a far more realistic picture than any off-the-shelf Heloc Payment Estimator could produce. The key insight is that these tools assume a static scenario. Real HELOCs are dynamic. Your balance changes, your rate changes, and the estimator won't adjust for either unless you do the adjustment manually.
Get the Full Details
Common Pitfalls That Undermine Accuracy
The most frequent mistake I see is assuming the quoted rate stays fixed. Lenders advertise teaser rates, especially when the market rate is falling. A 7.5 percent rate today might be a 2/1 buydown or just the current prime environment. When rates climb, your payment climbs with it. Some estimators let you lock in a single rate, but that produces a false sense of certainty. A more useful approach is to run sensitivity analysis at three different rate scenarios: current, plus 2 percent, and plus 4 percent. That tells you the range of what your payment could look like over a five-year horizon. Another overlooked factor is the compounding frequency. Some lenders compound interest daily, others monthly. Daily compounding on a variable balance means your interest accrues faster between statements, which slightly inflates your payment compared to a monthly compounding estimate. The difference is usually small on a per-payment basis, but over a full draw period it adds up to hundreds of dollars in additional interest costs. Check your loan documents for the compounding method and adjust your estimator assumption accordingly. There's also the fee structure that most estimators ignore entirely. Origination fees, annual maintenance fees, and early closure penalties are real costs that affect your effective borrowing cost but never show up in a monthly payment calculation. A $500 origination fee on a $50,000 draw is a 1 percent upfront cost that effectively raises your interest rate by roughly 0.15 to 0.25 percent depending on your payoff timeline. Factor that into your decision even if the payment estimator doesn't ask for it.
When a Heloc Payment Estimator Falls Short
These tools are fine for a rough ballpark. If you want to know whether a $30,000 draw at an estimated rate puts you under a comfortable monthly threshold, the estimator gets you in the right neighborhood. They break down completely when you need precision for financial planning or comparison shopping. Here's why. First, most free online estimators don't let you model partial draws at different times. They assume a lump-sum draw on day one. If you're a contractor who pulls funds in tranches as projects start, your actual payment pattern looks nothing like the output. Second, they rarely incorporate rate change simulations. You'd need to manually adjust the rate assumption for each hypothetical Fed move, which defeats the purpose of using a calculator. Third, they don't handle the overlap period well. Some HELOCs have a brief grace window after the draw period where you're making interest-only payments on the full balance before the amortization kicks in. That transition month can catch people off guard if their estimator doesn't flag it. If you need accuracy beyond a general estimate, a spreadsheet model or a consultation with a loan officer who can run scenario analysis through their internal pricing tools will give you results you can actually rely on. The estimator is a starting point, not a destination.
What to Check Before Trusting the Output
Verify that the estimator uses the correct rate type. Some tools default to fixed-rate assumptions even for HELOC products. Make sure you're selecting variable rate mode. Confirm the draw period length matches your actual loan terms. Ten years is common, but some lenders offer seven or twelve. The repayment term matters too. A 20-year repayment period produces very different payments than a 10-year repayment period, and the total interest paid over the life of the loan diverges sharply between the two. A 20-year term might save you $60 a month but cost you nearly $20,000 more in total interest compared to a 10-year payoff schedule. Also check whether the tool accounts for negative amortization. In rare cases, if your minimum payment doesn't cover the accrued interest, the unpaid interest gets added to your principal balance. This can happen during steep rate hikes when the draw period is extended. Most modern HELOC agreements prevent this, but older loans or certain lender structures may still allow it. An estimator that doesn't flag this possibility is giving you incomplete information. The bottom line is that a Heloc Payment Estimator is a useful rough guide, but it operates on simplified assumptions that don't always match how HELOCs behave in practice. Variable rates, phased draws, fee structures, and transition mechanics all introduce real-world complexity that static calculators struggle to capture. Build a detailed model if the numbers matter to your financial planning. Otherwise, use the estimator the way it's intended: as a quick sanity check before you walk into a lender's office.