Understanding HELOC Payoff With Extra Payments
A HELOC payoff calculator with extra payments is basically a spreadsheet or web tool that shows you what happens when you throw additional money at your line of credit each month. Most people have a standard amortization schedule built into their lender's portal, but those schedules assume you only make the minimum payment. When you add extra principal, the whole timeline shifts, and the standard tool doesn't account for it without some manual adjustment. I ran into this exact problem a few years ago when I was refinancing a property. The lender's online calculator showed a payoff in 18 years, but I was paying an extra $400 a month toward principal. I had to build a custom calculator that pulled the current balance, tracked the variable rate changes month by month, and applied the extra payment as a pure principal reduction. Took me about two hours to get right.
How to Use a Heloc Payoff Calculator With Extra Payments
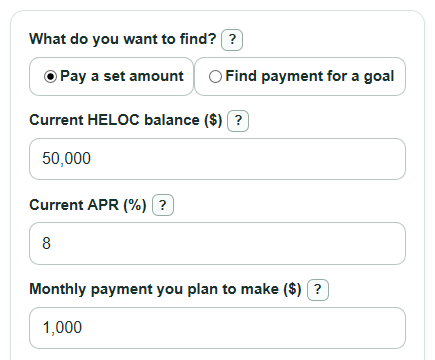
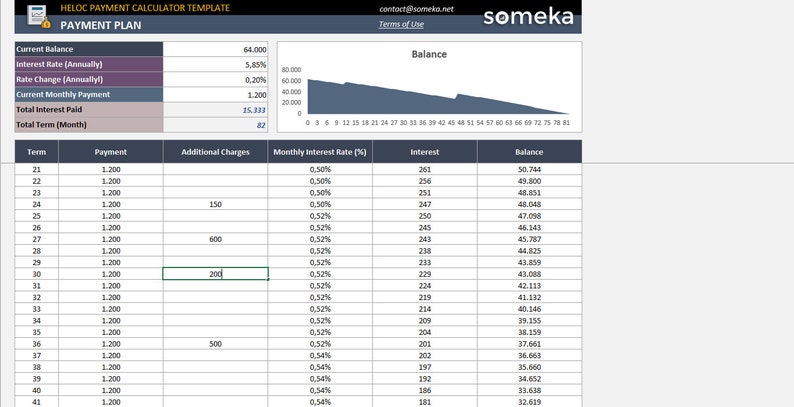
Start by pulling your current statement. You need three numbers: the outstanding principal balance, your current interest rate (draw period rates are variable, so this matters), and the remaining draw period or repayment period timeline. Some HELOCs are interest-only during the draw period, which means every dollar you pay beyond the minimum goes straight to principal. That's the best-case scenario for extra payments. Enter your base monthly payment, then add the extra amount you plan to pay each month. The calculator should recalculate the payoff date and total interest paid. Look for a breakdown that shows how much of each payment goes to principal versus interest, especially if your HELOC transitions from draw to repayment phase. That transition is where most people get surprised. I keep a simple Excel sheet for this. Columns for month number, starting balance, interest charged (balance times annual rate divided by 12), minimum payment, extra principal payment, and ending balance. Copy the formula down. It takes about five minutes to set up and gives you more accuracy than most online calculators, which often assume a fixed rate that never changes.
Here's something most calculators gloss over: many lenders apply extra payments to the next billing cycle rather than immediately reducing your daily balance. If your HELOC calculates interest daily on your average daily balance, paying extra mid-cycle can shave days off the accrual. I learned this the hard way after an extra $2,000 payment sat in limbo for three weeks while my lender processed it. The calculator didn't account for processing lag, so my actual payoff timeline was slightly longer than the estimate. Now I always buffer the extra payment by about ten days in my own calculations. Another edge case worth noting: some HELOCs have tiered interest rates based on your utilization ratio. If you're below 30% of your credit limit, you might get a lower rate than someone maxed out. An extra payment that drops you below that threshold could quietly reduce your rate, which compounds the savings. Most basic calculators don't factor this in. You have to manually adjust the rate and rerun the numbers. There's also the question of whether your lender allows partial prepayments without penalty. Most HELOCs do, but a handful of credit unions and older loan documents include clauses that limit how much you can overpay in a single year. Check your original promissory note. If there's an annual prepayment cap, your extra payment strategy needs to respect that ceiling or you could trigger a default clause.
Get the Full Details
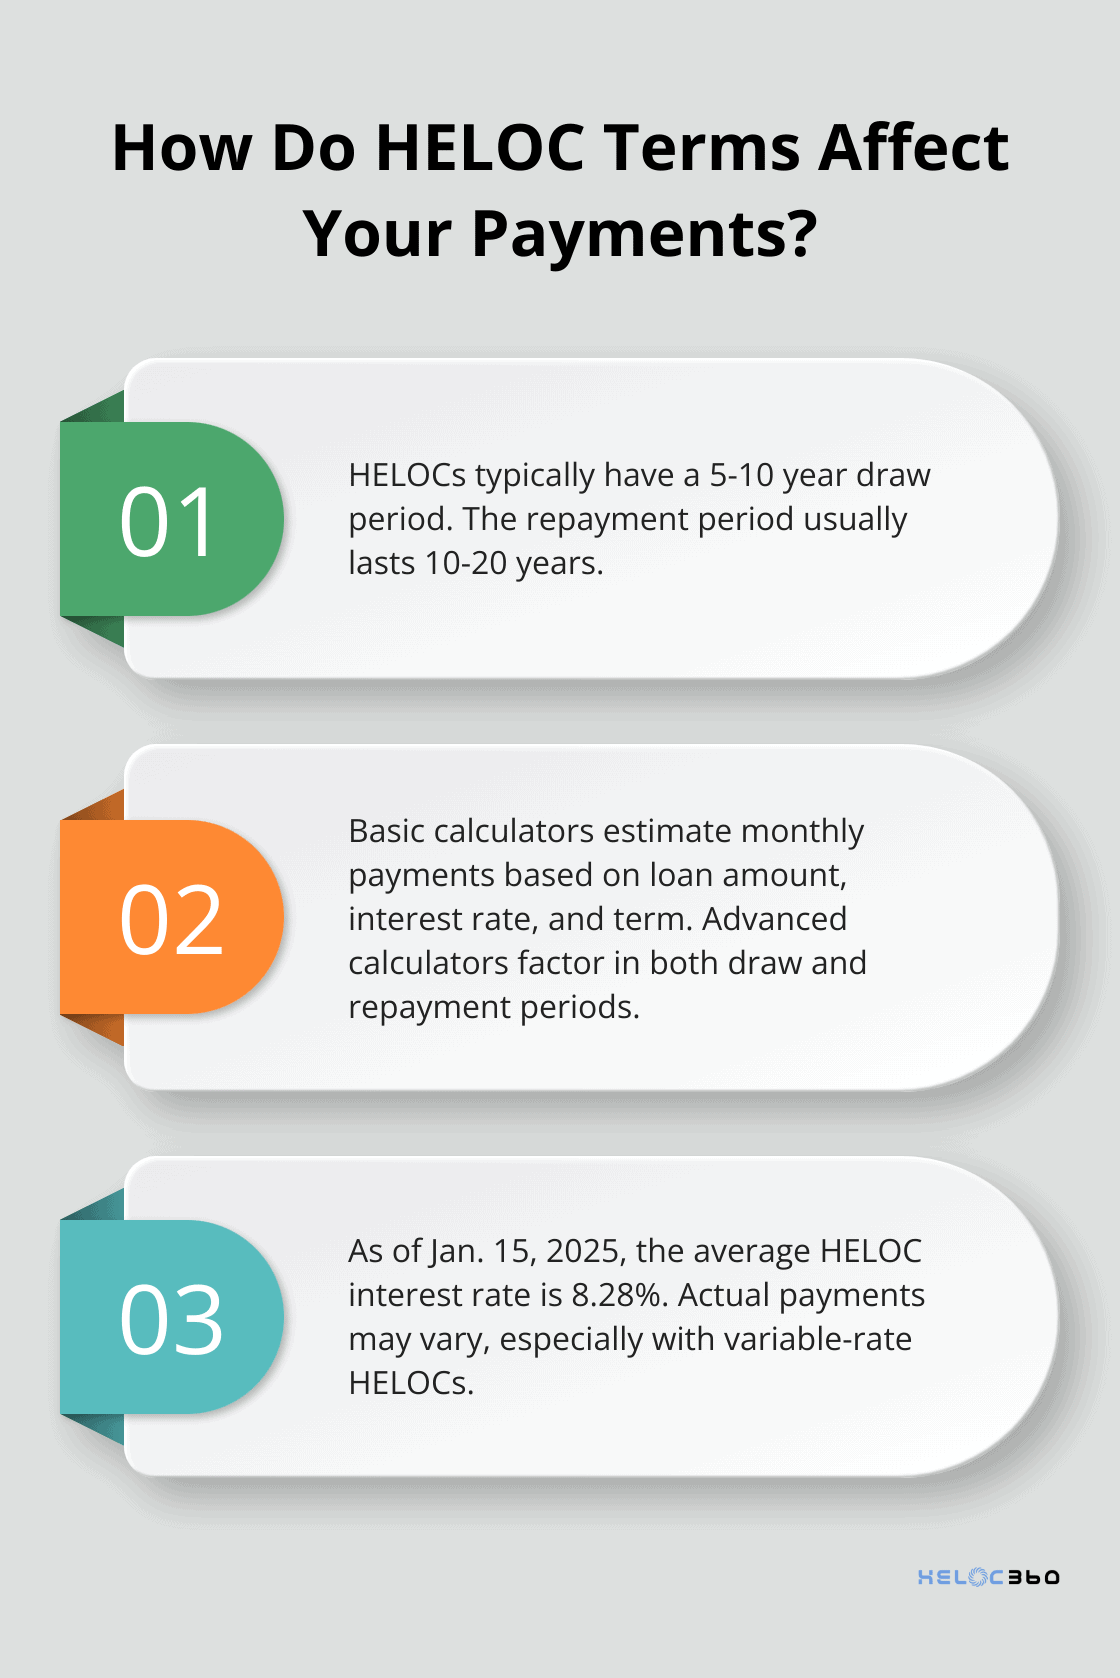
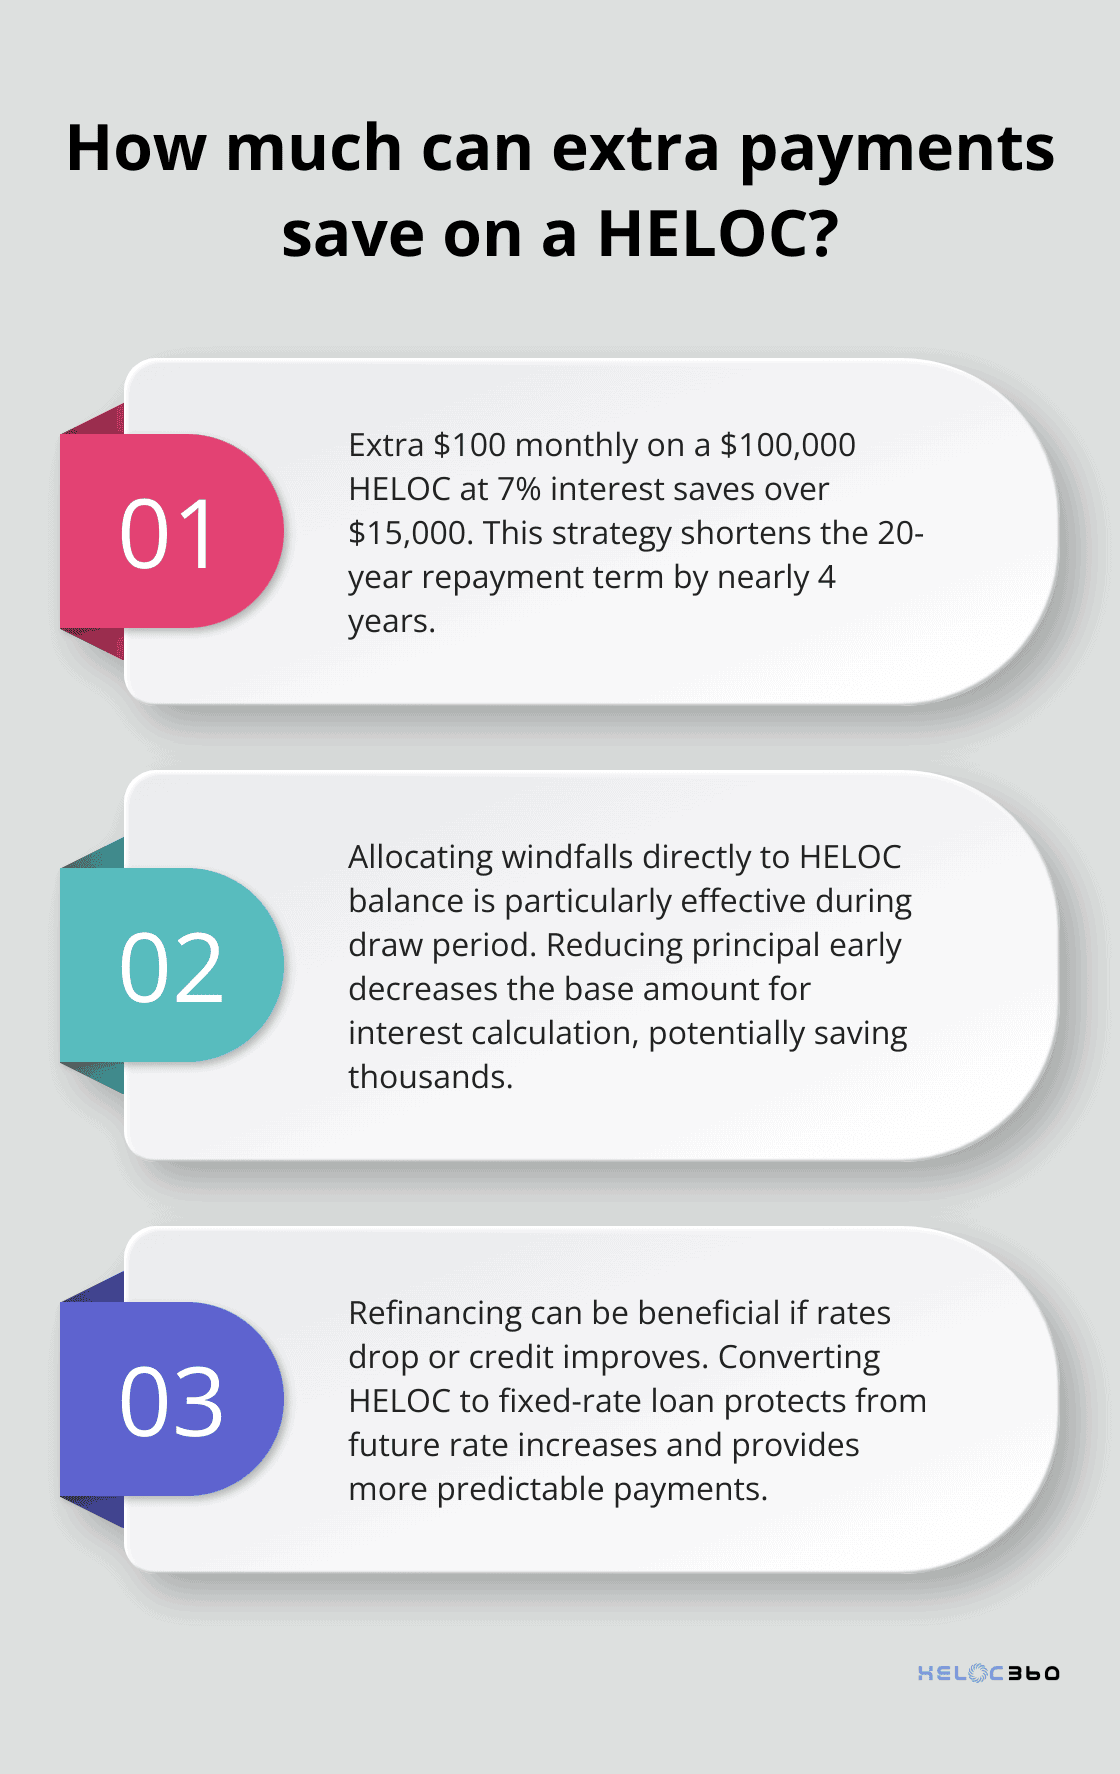
When you're comparing payoff scenarios, focus on total interest saved and months shaved off the term, not just the new payoff date. A calculator that shows you'll be debt-free two years early sounds good, but if the interest savings is only $800, the effort might not be worth the budget disruption. My rule of thumb is that if the interest savings doesn't exceed 3% of the original loan amount, I shift the extra payment elsewhere unless the psychological benefit of being free faster outweighs the math. One more thing. Variable rate HELOCs can reset at any time. If the prime rate jumps 200 basis points, your minimum payment could increase significantly even if you've been making extra principal payments. I ran a stress test on my own calculator by bumping the rate up 3% across the board, and it pushed my payoff out by 11 months compared to the baseline estimate. You should do the same. Run a worst-case scenario and see if the extra payment strategy still makes sense under pressure.