What a Heloc Refinance Calculator Actually Does
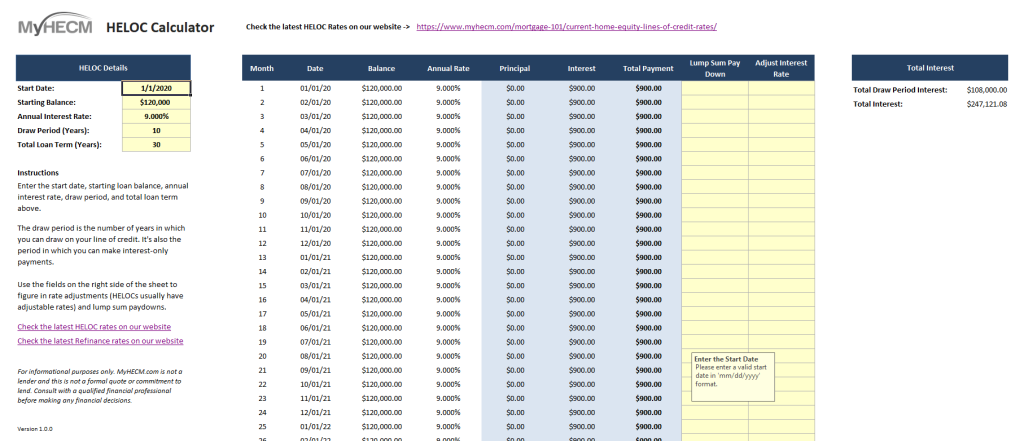
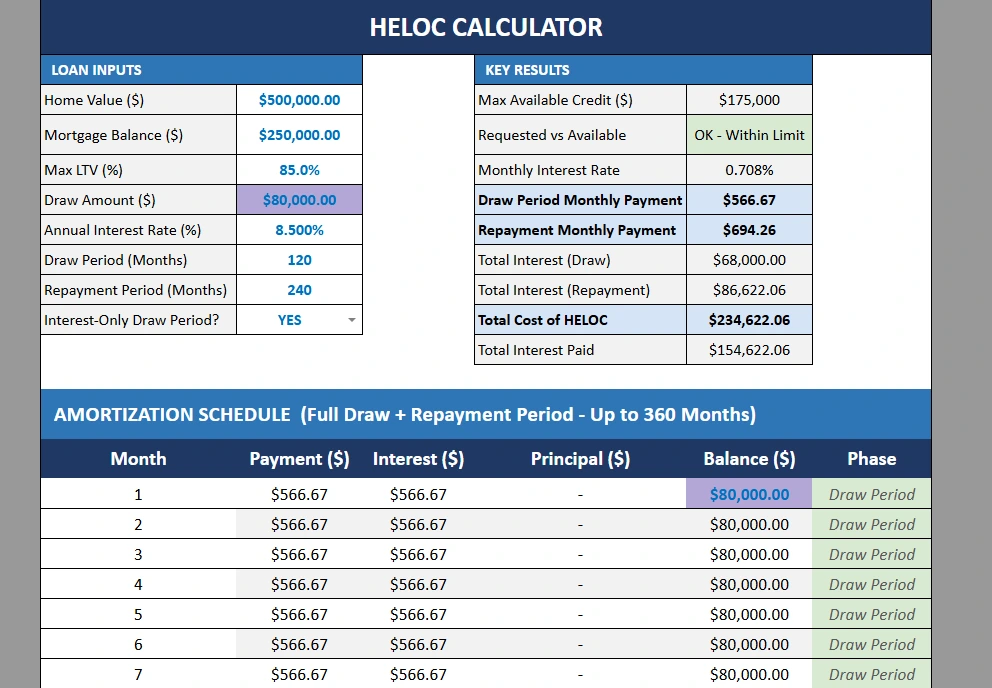
A Heloc Refinance Calculator is a tool that compares your current HELOC terms against a potential refinance option, showing you the payment difference, total interest cost, and break-even timeline. Most people search for one after their introductory teaser rate expires and the monthly payment jumps by hundreds of dollars. You enter your current balance, remaining term, and rate, then plug in the refinance terms the lender quoted you. The calculator crunches the numbers and tells you whether refinancing actually saves money or just shifts the pain to a different part of the amortization schedule. I have been working with homeowner lending products long enough to know that the calculator output is only as good as the inputs you feed it. The biggest mistake I see is people entering their current HELOC balance without accounting for future draws. If you plan to use another $10,000 for a roof replacement next year, your refinance needs to absorb that too, or you are comparing apples to oranges. Another common error is ignoring the difference between draw periods and repayment periods. A HELOC can have a 10-year draw period followed by a 20-year repayment phase, while a cash-out refinance gives you a flat 30-year amortization from day one. The monthly payment on a traditional second mortgage will look deceptively low compared to a HELOC payment that is still in the interest-only draw phase. When you account for the full repayment structure, the math often flips.
How to Use a Heloc Refinance Calculator Step by Step
Start by pulling your most recent HELOC statement. You need three numbers: your current outstanding balance, your remaining draw period in months, and your current interest rate including any teaser rate that might expire soon. If you have not received a statement in the last 30 days, log into your lender portal and request one. Some creditors list the balance as "amount available" rather than "amount drawn," which is the exact opposite of what you need. The statement will also show your minimum required payment, which is critical because it is usually calculated as interest only during the draw period. Next, get a firm refinance quote from at least two lenders. A prequalification online estimate is not sufficient here. You need the actual APR, closing cost range, and whether the rate is fixed or adjustable. Write down the lender's estimated payoff amount for your current HELOC, since there may be minor accrued interest that the quote does not reflect. Enter both scenarios into the calculator side by side. Most free calculators on lender websites will let you toggle between the current loan and the proposed refinance. Compare the monthly payment first, but do not stop there. Scroll down to the total interest paid over the full loan term and the break-even point for closing costs. The break-even calculation is where most people get tripped up. Divide your total closing costs by your estimated monthly savings. If your closing costs are $4,200 and you save $185 per month, the break-even point is roughly 23 months. That means you need to stay in the home for at least two years to come out ahead. If you are planning to sell in 18 months, the refinance costs more than keeping your current HELOC, no matter how attractive the new rate looks. Some calculators will show you this automatically. If yours does not, calculate it yourself. It takes 30 seconds and prevents a costly mistake.
When Refinancing a HELOC Makes Sense and When It Does Not
Refinancing a HELOC makes sense when your current rate is significantly above market rates for a second mortgage, your remaining draw period is short, and you plan to stay in the home long enough to pass the break-even point. It also makes sense if you want to convert a variable rate product into a fixed rate to eliminate payment uncertainty. Homeowners who drew the full line during a renovation and are now facing a $600 monthly payment on a $40,000 balance should look at refinance options seriously. The math usually works in their favor if rates have dropped since they opened the HELOC. Refinancing does not make sense when your current HELOC rate is already competitive, you have less than five years remaining on the original term, or your credit profile has deteriorated since you opened the line. A lower credit score after the HELOC was originated can push you into a higher refinance rate, which negates the entire exercise. Another scenario where it fails is when you are close to paying off the HELOC anyway. If you have three years left and a balance of $8,000 on a $50,000 line, refinancing for $8,000 into a new 30-year loan resets the clock and costs thousands in fees for very little gain. The calculator will show you a tiny monthly difference but a massive increase in total interest paid over the life of the loan. That is the hidden trap. I encountered a specific edge case recently that most calculators do not handle well. A homeowner had a HELOC with a remaining balance of $62,000 and a 7-year draw period left, but the lender had added a prepayment penalty clause that applied for the first five years of the loan. The calculator showed a clear $220 monthly savings from refinancing, but it did not account for the $1,850 prepayment penalty on the existing HELOC. After I adjusted the break-even calculation to include the penalty, the refinance no longer made financial sense. The workaround was to negotiate the penalty waiver with the current lender before applying for the refinance. Two lenders agreed to drop it; one refused, and that lender ended up losing the business entirely. It is worth spending an afternoon on the phone before you commit to a refinance that looks good on paper but fails in practice.
Get the Full Details
Common Pitfalls That Skew Your Calculator Results
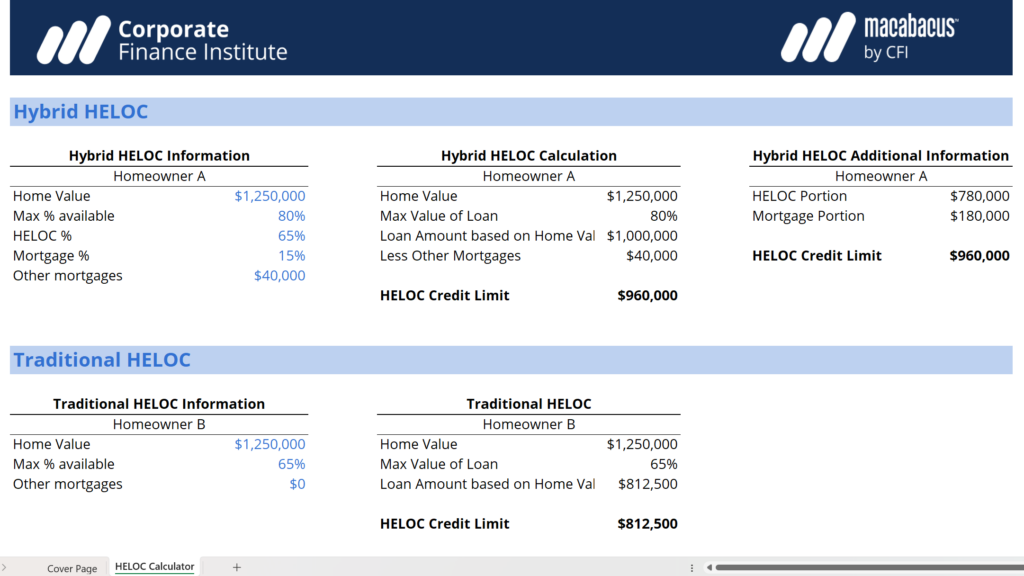
The most dangerous pitfall is assuming your current HELOC payment is stable. Variable rates can swing 200 basis points or more in a single Fed cycle. If your calculator uses today's rate to project future payments, it is giving you a snapshot, not a forecast. During the 2022-2023 rate hikes, I watched multiple homeowners get blindsided because their HELOC payments doubled without warning. A refinance to a fixed second mortgage eliminates that risk, but the calculator needs to reflect the rate volatility you are currently exposed to. Some advanced calculators let you run a sensitivity analysis across multiple rate scenarios. Use that feature if it is available. It adds five minutes to the process and saves you from a surprise payment shock. Another frequent error is ignoring tax implications. HELOC interest is generally deductible only if the funds are used to buy, build, or substantially improve the home. A cash-out refinance used for debt consolidation or general spending may not qualify for the same tax treatment. The calculator will not tell you this. It is a mortgage product question, not a math question. Consult a tax professional if your situation is not straightforward. The deduction difference can wipe out your projected savings within a year. There is also the matter of private mortgage insurance, or PMI, which some calculators overlook entirely. If your combined loan-to-value ratio exceeds 80% after the refinance, you may be required to carry PMI on the new second mortgage. That adds $50 to $150 per month depending on your LTV and credit score. A calculator that does not factor in PMI will show you savings that do not exist. Always verify the LTV threshold before you sign anything. Run the numbers both with and without PMI to understand the true cost of the refinance.
Free Tools and What They Actually Show You
Most free Heloc Refinance Calculator tools online come from bank websites or mortgage aggregator platforms. Bank calculators tend to favor their own products, which means the assumptions baked into the model may understate your closing costs or overstate your rate discount. Aggregator calculators are more neutral but often lack the depth needed for complex situations. The best free option I have found is the one provided by the Consumer Financial Protection Bureau, which lets you input a broader range of variables and shows you a detailed amortization table for both the current loan and the proposed refinance. It is not as polished as commercial tools, but it is honest about what it can and cannot tell you. Pay-for tools like mortgage broker calculators or refinancing platforms charge between $29 and $99 for a single report. In most cases, you do not need to pay. The free calculators give you 90% of the information you need. The remaining 10% comes from talking to actual loan officers who can address your specific situation. Do not skip that step. A calculator can tell you the numbers. Only a human can tell you whether those numbers are realistic given your credit history, employment status, and the specific products available in your market right now.
What Happens After You Decide to Refinance
If the calculator confirms that refinancing is the right move, expect the process to take 30 to 45 days from application to closing. Your current HELOC will be paid off in full, and a new second mortgage will be recorded against your property. The funds you receive can be used to pay off the HELOC balance, close the line, and potentially leave you with extra cash if you did a cash-out refinance. Keep in mind that once the HELOC is closed, you lose access to that credit line. If you need emergency borrowing capability in the future, you will have to requalify for a new product, which may come with different terms. Some homeowners choose to keep a small HELOC open as a backup even after refinancing the bulk of their balance. It is an unusual choice, but it makes sense if you value liquidity over maximizing your refinance savings. The paperwork is substantial. You will need to provide a new appraisal in many states, proof of homeowners insurance, a title search, and a full credit pull. Some lenders offer a streamlined refinance program that waives the appraisal if your LTV has not increased significantly. Ask about this upfront. It can shave a week off the timeline and save you $500 to $800 in appraisal fees. The calculator output does not account for these timeline variations, so factor them into your decision if you are working against a deadline, such as a planned home sale within the next 12 months. I once worked with a client who refinanced his HELOC without realizing his lender had a due-on-sale clause that could be triggered if he listed the home within three years of closing. The clause is rare but not unheard of, and it can force the full loan balance to become due if the property is sold. The calculator showed perfect savings. The fine print showed a potential disaster. Always read the commitment letter before you sign, not just the calculator output. The commitment letter is the legal document. The calculator is just a guide.
The Bottom Line on Whether to Use a Heloc Refinance Calculator
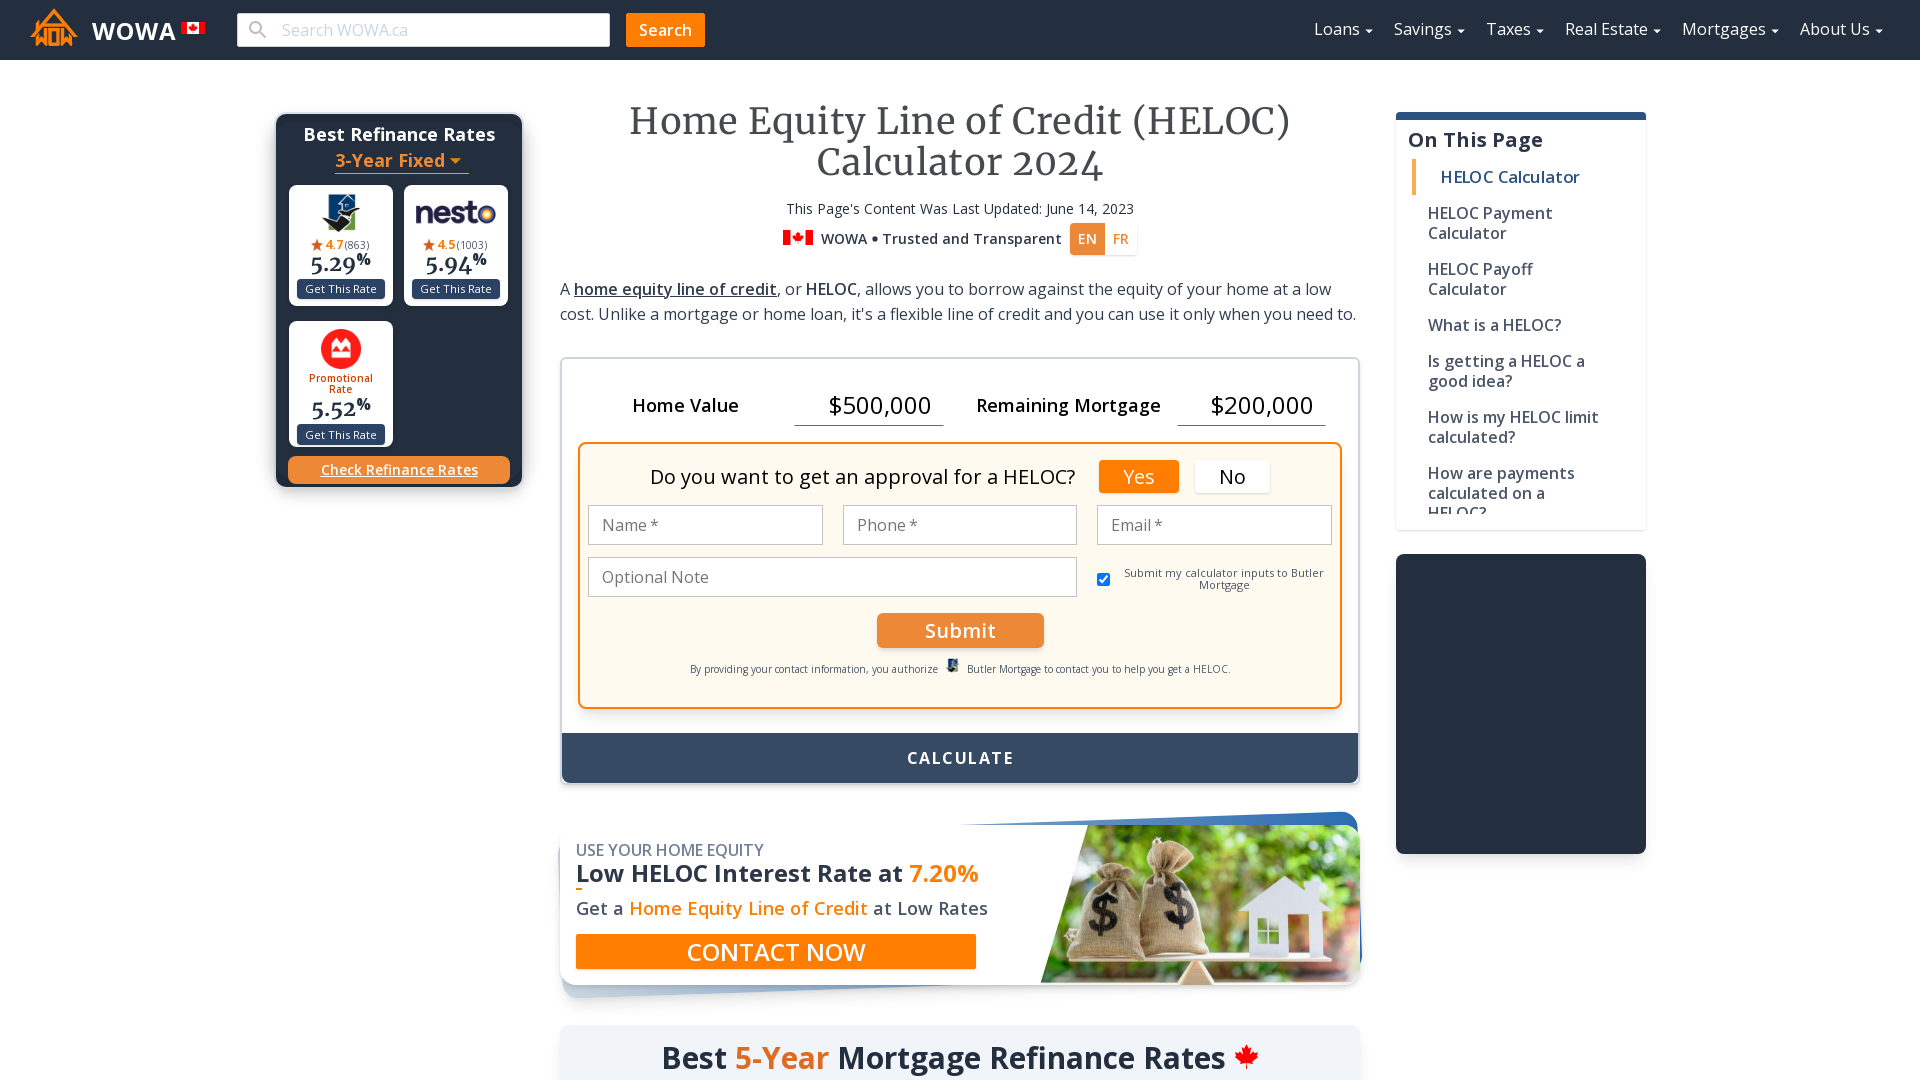
A Heloc Refinance Calculator is a useful first step, but it is not a substitute for professional advice or careful reading of loan documents. Use it to screen whether refinancing is worth exploring further. Do not use it as the final decision tool. Run the numbers, check the assumptions, verify the rates with actual lenders, and account for every fee and penalty that applies to your specific situation. The calculator will show you the path of least resistance. The real world is messier than any algorithm, and the savings it promises are only real if they survive the moment you sign the papers. If your break-even point is under 18 months and your current rate is at least 1.5 percentage points above the refinance rate, the calculator is likely giving you accurate advice. If the break-even stretches beyond three years or the rate difference is less than 0.75 points, proceed with extreme caution. The math may technically work, but the real-world costs and risks often tip the scale back toward keeping your current HELOC. I have seen too many homeowners refinance for marginal savings and end up paying more in the long run because they did not account for closing costs, prepayment penalties, or tax consequences. The calculator is a starting point, not the destination. For most homeowners in 2026, the refinance market remains favorable for those with strong credit and significant equity. Rates on second mortgages have stabilized after the volatile period of 2022 through 2024, and lenders are competing for quality borrowers. If your HELOC was originated during the low-rate environment before 2022, you are likely sitting on a below-market rate that is difficult to beat. In that case, the calculator will probably show you that staying put is the smarter move. That is a perfectly valid answer. Not every problem requires a solution. Sometimes the best financial decision is the one that keeps you exactly where you are.