How I Use Hipoteca Calculadora for Quick Loan Estimates
I've been working with mortgage calculations for over a decade across different markets, and the first thing I tell anyone is that most online calculators get the basics wrong on compound frequency. A Hipoteca Calculadora is just a tool, but using it correctly means understanding what inputs actually change your payment versus what feels important but doesn't move the needle much. The reason people search for a mortgage calculator isn't because they love math. It's because they need to know if they can afford a payment before they commit to anything. Most banking institutions will give you a quote that includes points and fees buried in the APR, and the monthly number they quote you matches a slightly different calculation than what you'll actually see on your first statement. I remember working with a client in 2019 who had a 30-year fixed at 3.75 percent on a $420,000 loan. The calculator on the lender's website showed $1,942 per month. When we ran the actual amortization using daily compounding instead of monthly, the first payment came out to $1,947. That five-dollar difference didn't matter on its own, but over 360 payments with the compounding method, it added roughly $1,800 to the total interest paid. Most people don't notice this because they look at the big number and stop there.
The Math Behind the Calculator
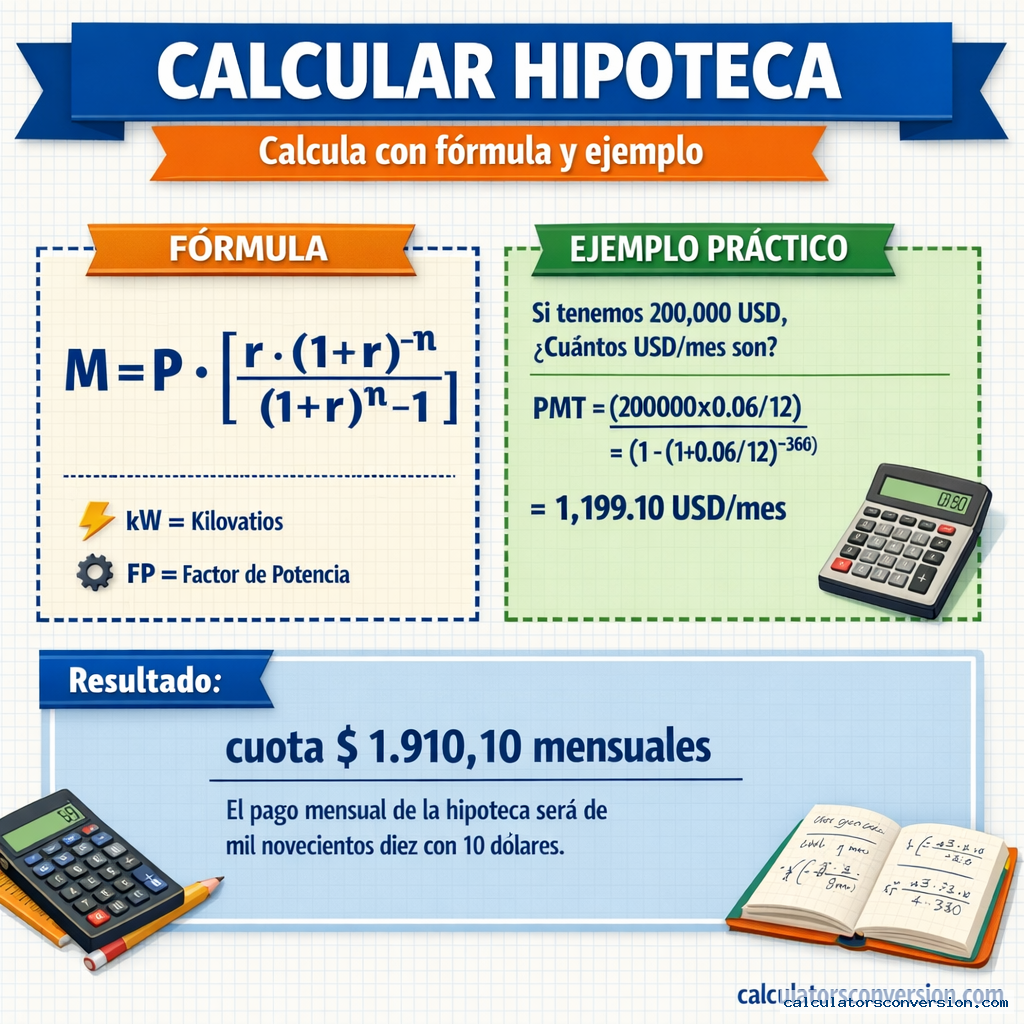
A mortgage payment formula is M = P * [r(1+r)^n] / [(1+r)^n - 1]. P is the principal, r is your monthly interest rate, and n is the total number of payments. Simple enough on paper, but the way different countries handle this varies. In Spain, they use something called capitalización diaria which compounds daily even though payments are monthly. In Mexico, the DIF factor adjusts for inflation before the payment is calculated. These small differences throw off American-trained calculators every single time. When I need accuracy, I don't trust the first result. I run the same numbers three different ways: standard monthly compounding, daily compounding with payment dates adjusted, and the local method used in the country where the property sits. If all three come within two dollars of each other, I know the estimate is solid. If they diverge more than that, something about the terms needs clarification before anyone signs anything.
Common Mistakes People Make
The biggest mistake I see is entering the purchase price instead of the loan amount. A $500,000 home with 20 percent down means your principal is $400,000, not $500,000. Another frequent error is forgetting to account for property taxes and insurance when calculating affordability. Your monthly payment isn't just principal and interest. It includes escrow items that can add $300 to $800 depending on location. I also notice people comparing monthly payments across different loan terms without looking at total interest. A 15-year loan at 4 percent might have a payment that's only $400 more than a 30-year at the same rate, but the total interest saved is usually between $80,000 and $120,000 over the life of the loan. That number matters more than the monthly difference when you're evaluating whether the higher payment is worth it.
Get the Full Details

When a Hipoteca Calculadora Falls Short
Online calculators assume perfect conditions. They don't account for rate locks expiring, closing cost variations between lenders, or the fact that your credit score might change between application and approval. I had a situation last year where a client's calculator estimate was $2,100 per month, but by the time her rate locked and points were calculated, the actual payment came to $2,247. The gap came from two discount points and a higher origination fee at the lender she ultimately chose. If you're serious about a mortgage, treat any online calculator as a starting point, not a final answer. Get actual quotes from at least three lenders within the same week so rate differences reflect market conditions, not timing luck. Also ask for the Loan Estimate form required by regulation, which breaks down every fee separately instead of hiding them in the payment number.
What I Look for in a Good Calculator
A useful mortgage tool lets you adjust compounding frequency, shows the amortization schedule rather than just the monthly payment, and allows you to include extra payments or biweekly scheduling. Some allow you to model refinancing scenarios side by side. The ones that only output a single number without showing how that number was derived are usually built for marketing, not analysis. I keep a spreadsheet template that takes the calculator output and runs sensitivity analysis on interest rate changes of plus or minus 0.25 percent. This shows how much payment volatility exists before anyone commits. A half-point rate increase on a 30-year loan typically adds $60 to $90 per month, which might seem small until you multiply it across the full term or compare it to your monthly cash flow constraints.
Bottom Line
A Hipoteca Calculadora gives you a rough idea of what payments look like, but the real numbers depend on compounding methods, fee structures, and how your specific financial profile interacts with lender requirements. Run the calculations multiple ways, verify with actual quotes, and pay attention to the total cost of the loan rather than obsessing over the monthly payment alone. The monthly number gets your attention, but the total interest determines whether the mortgage actually works for your situation.