How Charles Schwab Actually Changed Brokerage
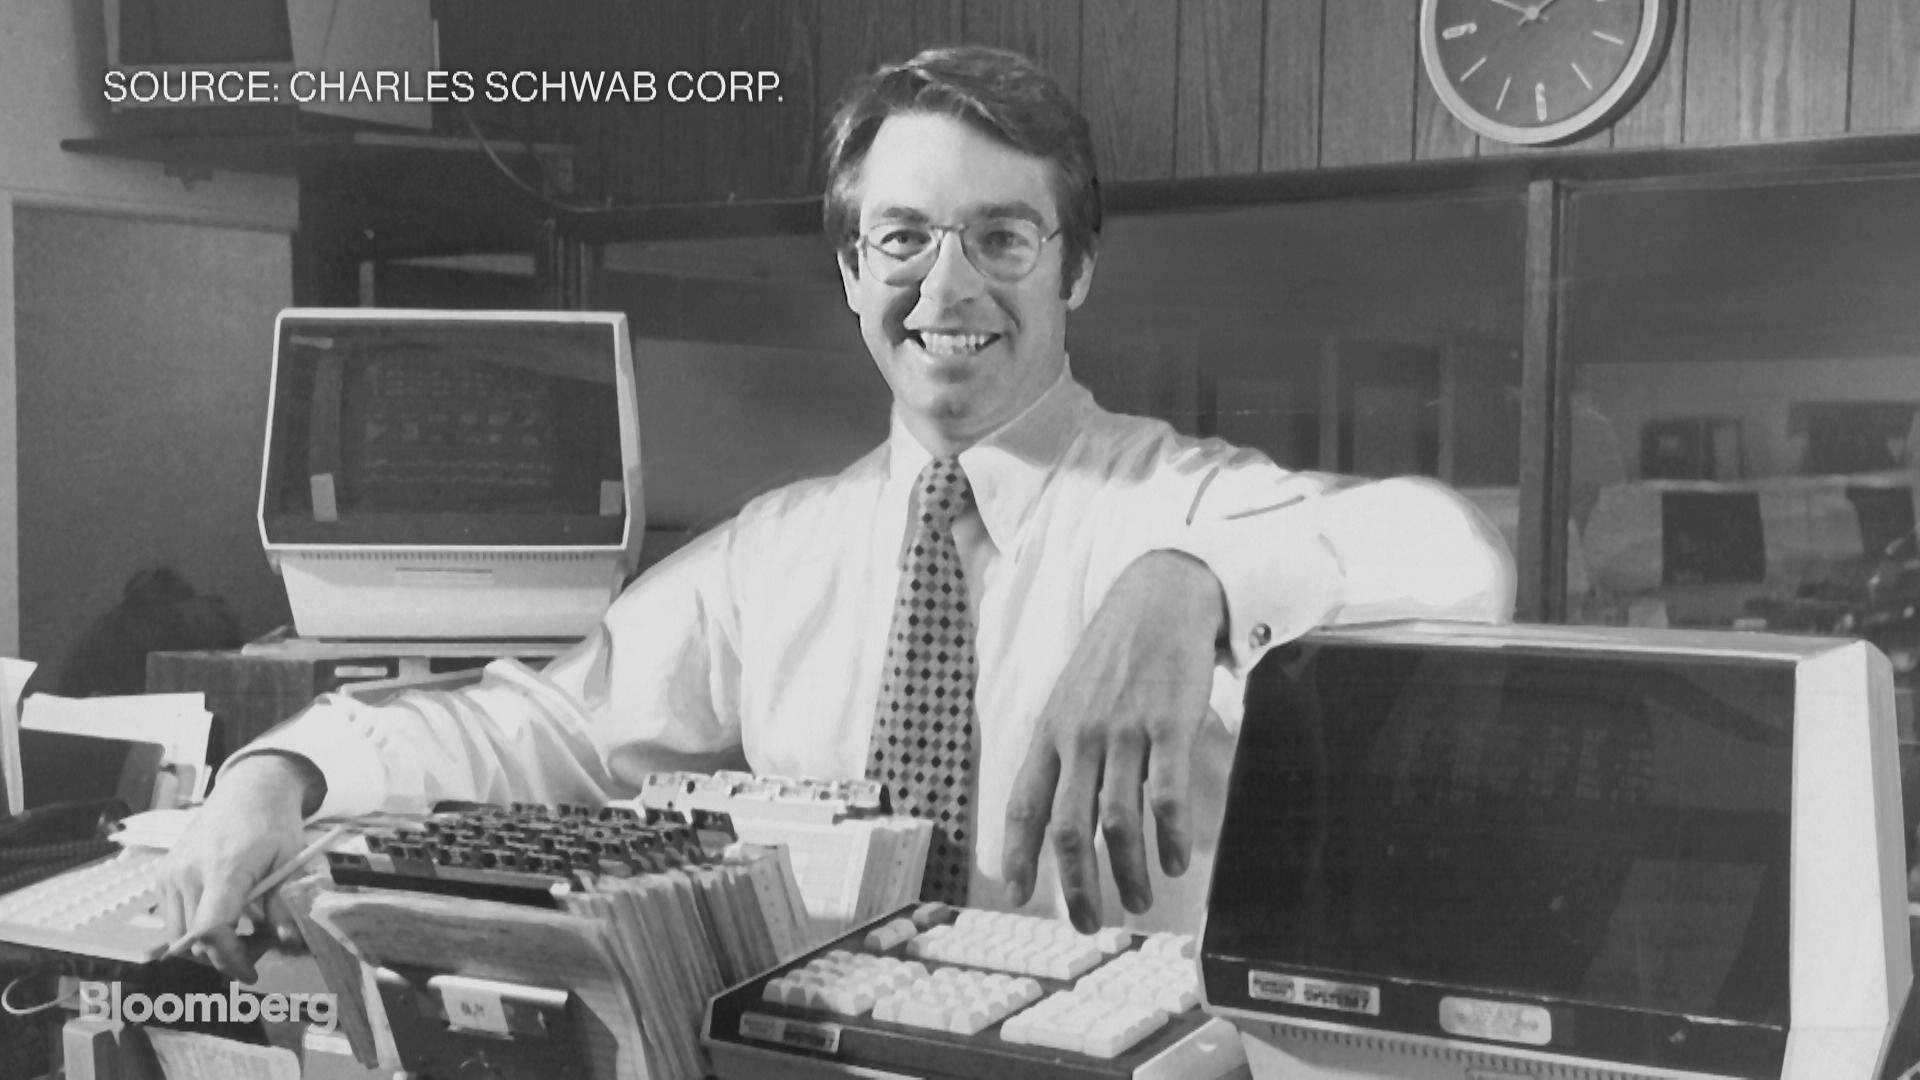
Charles Schwab Corporation isn't just another financial firm with a cool name. It's the company that broke the commission-based brokerage stranglehold and forced every major player in the industry to lower their fees or die trying. The History Of Charles Schwab is really the story of one guy deciding that regular people deserved better than the 5% load fees the Wall Street giants were charging in the late 1970s. Charles R. Schwab was a Yale grad who came up through Goldman Sachs and Drexel before starting his own thing. In 1971, he opened a small brokerage in San Francisco with one key difference: he charged a flat $29.95 per trade instead of the typical $100-plus. That price point wasn't a marketing gimmick. It was calculated to be just enough above cost to stay profitable while making discount trading actually viable for everyday investors who weren't dealing in six-figure blocks.
The History Of Charles Schwab and the Discount Brokerage Wars
Here's what most people miss when they look at the History Of Charles Schwab: the early years were brutal. Schwab's original company, Charles Schwab & Co., ran into regulatory trouble when the SEC investigated whether their commission structure violated anti-trust provisions. They settled without admitting wrongdoing, but the whole experience showed that the old guard wasn't going to let a discount broker survive quietly. They'd find reasons to make life hard. The real breakthrough came in 1986 when Schwab eliminated commissions entirely for trades over a certain size, and then gradually moved toward zero-commission for most stocks. This was the moment the entire industry started collapsing. Merrill Lynch, which had been the gold standard for full-service brokers, couldn't compete on price and had to restructure painfully. The lesson here is that discount brokerage wasn't a niche product. It was the inevitable end state of any market where information asymmetry between brokers and clients could be reduced by technology. I worked on a project back in 2008 where we had to migrate account data from a legacy Schwab system to a newer platform during the financial crisis. The documentation was sparse. Nobody at the time realized how much reliance there was on proprietary file formats from the early trading systems. What saved us was finding an archived copy of the original schema definitions from the mid-1990s upgrade, which someone had kept in a departmental folder nobody checked. We rebuilt the migration maps from that and avoided a complete data loss scenario. You don't hear about these edge cases because they get resolved quietly, but they're exactly the kind of problem that shows how much institutional knowledge lives in legacy systems at firms like Schwab.
Where Charles Schwab Stands Now
The company went public in 1986 and has been growing ever since, mostly through acquisition. The biggest move was buying the TD Waterhouse retail business from TD Bank in 2020 for about $4.5 billion. That deal added roughly 4 million accounts and made Schwab one of the largest online brokers in the US overnight. Before that, they'd acquired American Brokers Clearing in 1995, Bear Stearns' prime brokerage in 2008, and various other players to build out their infrastructure. What's interesting about the current structure is how Schwab has moved from being purely a discount broker to offering a full range of services: banking, wealth management, retirement planning, and even a robob advisory platform called Schwab Intelligent Portfolios. They learned early that low commissions alone wouldn't keep clients loyal. Once you have their money, you want them using every product you offer. The 2023 situation with Silicon Valley Bank was a moment where Schwab's size actually helped them. When SVB collapsed, Schwab had about $162 billion deposited there. Rather than freezing all client access, they used capital reserves to make sure customers could access their money immediately. That decision cost them but built enormous goodwill. The alternative would have been a run on the bank that no amount of PR could fix.
Get the Full Details
How to Use Schwab's Services Today
If you're looking at Schwab for your own investing, the practical reality is that they're solid for most retail investors. The platform is stable, the research tools are decent, and the customer service response times are reasonable compared to competitors. The brokerage itself is regulated and SIPC insured. One thing to watch out for: the margin rates. Schwab's margin interest rates are competitive but not the lowest available. If you're planning to carry a significant margin balance, shop around. I've seen people save a few hundred dollars a year just by moving a large margin account to a different provider. The rate differential adds up fast when you're carrying six figures on margin. The bank side of the business offers a decent high-yield savings account and checking with no monthly fees. The CD rates aren't industry-leading but they're fair. If you're just looking for a place to park cash while you decide what to invest, it's fine. Don't expect it to outperform specialized online banks on yield.
The wealth management side targets higher net worth clients with minimums around $100,000 in investable assets. The advisors there are generally competent, but the fee structure can be confusing. Make sure you understand exactly what you're paying and whether the advice justifies the cost. Not everyone needs a dedicated advisor, and Schwab's own materials sometimes blur the line between when you need one and when you're fine managing on your own. The mobile app has gotten noticeably better over the past few years. It's not perfect, but it handles the basics well. Place trades, check balances, view positions. The advanced order types work, though the interface for complex orders still feels a bit clunky compared to some competitors. If you're doing a lot of options trading, you might prefer the desktop platform for speed. Overall, the History Of Charles Schwab is a story of a company that bet on giving regular people access to the markets at lower cost and then slowly expanded to keep them. That strategy has worked remarkably well. Whether it makes sense for you depends on your specific situation, but for most people looking for a reliable, well-established brokerage, Schwab is a legitimate option worth considering.