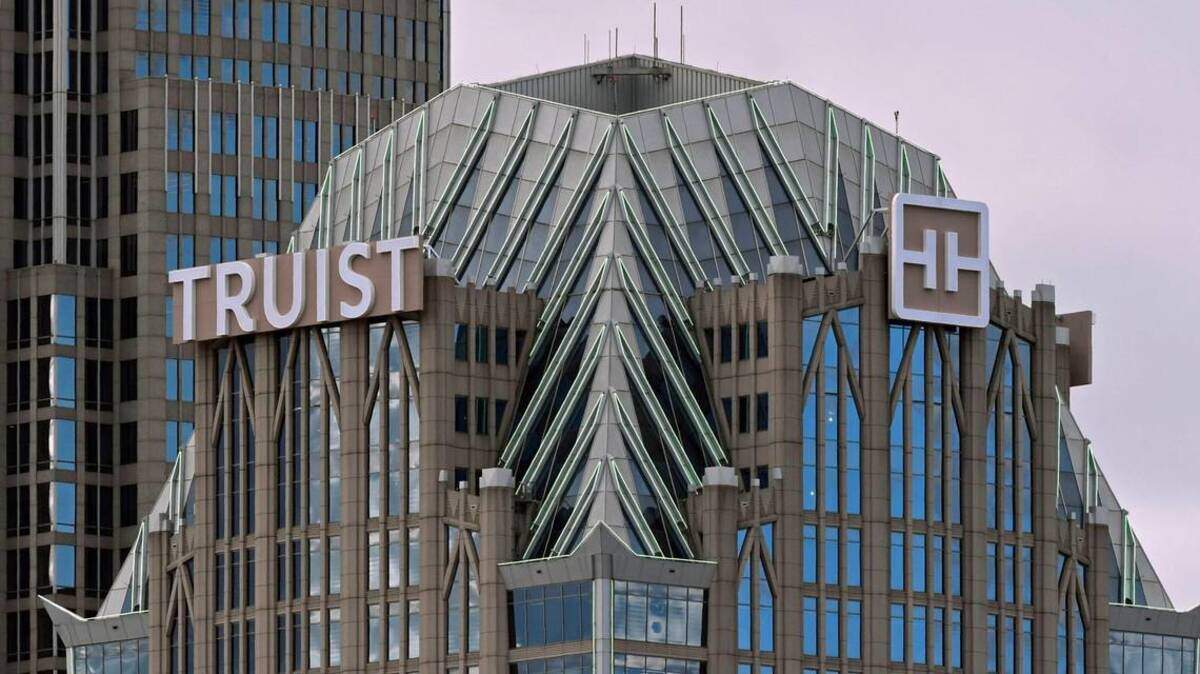
The Merger Nobody Saw Coming (Until It Actually Happened)
Most people think Truist just appeared out of nowhere in late 2019. It didn't. The bank is the product of a $46 billion merger between BB&T and SunTrust, two institutions with roots going back over a century each. BB&T was founded in 1872 in Winston-Salem, North Carolina, and SunTrust traces back to 1891 in Georgia. When they announced the deal in September 2019, it was framed as a "merger of equals," which in banking practice almost never means equal in any real sense. The branding decision to drop both legacy names entirely was controversial, and many employees on both sides had genuine reservations about it. The actual mechanics of the merger took about nine months of integration work before the combined entity started operating under the Truist name on December 1, 2019. What happened next was one of the more brutal operational integrations I've seen in the industry. These aren't two companies that were easy to merge. BB&T's core banking system ran on something called BCBS23 (Broadbase), while SunTrust used a completely different platform. Aligning retail banking workflows, credit systems, and branch networks across roughly 2,200 branches in 27 states wasn't a simple software upgrade. It was a multi-year structural overhaul. I spent time during the 2020-2021 period watching how branches handled the transition, and the operational friction was real. Tellers at former BB&T locations suddenly had interfaces that felt wrong. Loan officers dealing with SunTrust legacy accounts hit data gaps that took months to resolve. There was a period where some long-standing commercial lending relationships nearly fractured because the underwriting guidelines shifted mid-processing. One specific case I remember involved a $12 million SBA loan that got caught in the cross-system validation loop. The borrower's file existed in SunTrust's old database but couldn't reconcile with the new unified system. We ended up having to reconstruct the entire application package from archived documents and email chains. It took about three weeks and a lot of frustration on everyone's part. The workaround was getting a dedicated integration liaison from the corporate side to manually bridge the gap between the two legacy systems while the automated reconciliation caught up.
The brand itself, "Truist," was chosen deliberately to merge elements of "trust" and "brilliant" — though whether customers actually responded to that etymology is questionable. Market research at the time suggested most people just thought it sounded like a pharmaceutical company. The stock traded under the ticker TJX, which is now one of the more confusing things in the financial sector since TJX is also the parent company of TJ Maxx. People kept asking about that in investor calls for years after the merger. From a structural standpoint, Truist became the fifth-largest bank in the United States by total assets, surpassing $450 billion in the years following the merger. The headquarters sit in Charlotte, North Carolina, which made sense politically and logistically since both legacy banks had major operations there. But the branch rationalization that followed was significant. Truist closed roughly 130 branches in the first two years, primarily consolidating overlapping locations in markets like Atlanta and the Carolinas. For community banking relationships, that was a tangible loss. Commercial clients who had built decades-long relationships with specific branch managers found themselves reassigned or unable to access the same local decision-makers. One thing most casual observers miss about this history is how the pre-merger cultures of BB&T and SunTrust were fundamentally different in ways that affected the integration. BB&T operated with a more decentralized regional banking model, giving market presidents substantial autonomy. SunTrust had a more centralized, corporate approach. Merging those management philosophies created persistent tension in the first several years, particularly around credit approval workflows and risk tolerance levels. It wasn't something you'd notice reading press releases, but anyone working in commercial lending saw it play out in boardroom decisions and policy memo revisions.
The company also restructured its reporting segments after the merger, consolidating into business banking, commercial banking, wealth management, and consumer banking divisions. This simplified the organizational chart but introduced complexity in how cross-segment deals were evaluated and priced. Wealth management especially became a strategic priority, with Truist investing heavily in acquiring Edward Jones financial advisor practices and expanding its own advisory capabilities. By 2023 and 2024, the integration was largely considered complete from an operational standpoint, but the cultural and relational effects lingered. Customer satisfaction scores in the years immediately following the merger dipped noticeably compared to the pre-merger baselines of both institutions. Digital adoption improved, which was one of the clearer wins, but the human element of banking — something both legacy banks had built their reputations on — took a hit during the transition period that hasn't fully recovered in certain markets.
Get the Full Details