Understanding How Special Assessments Actually Work
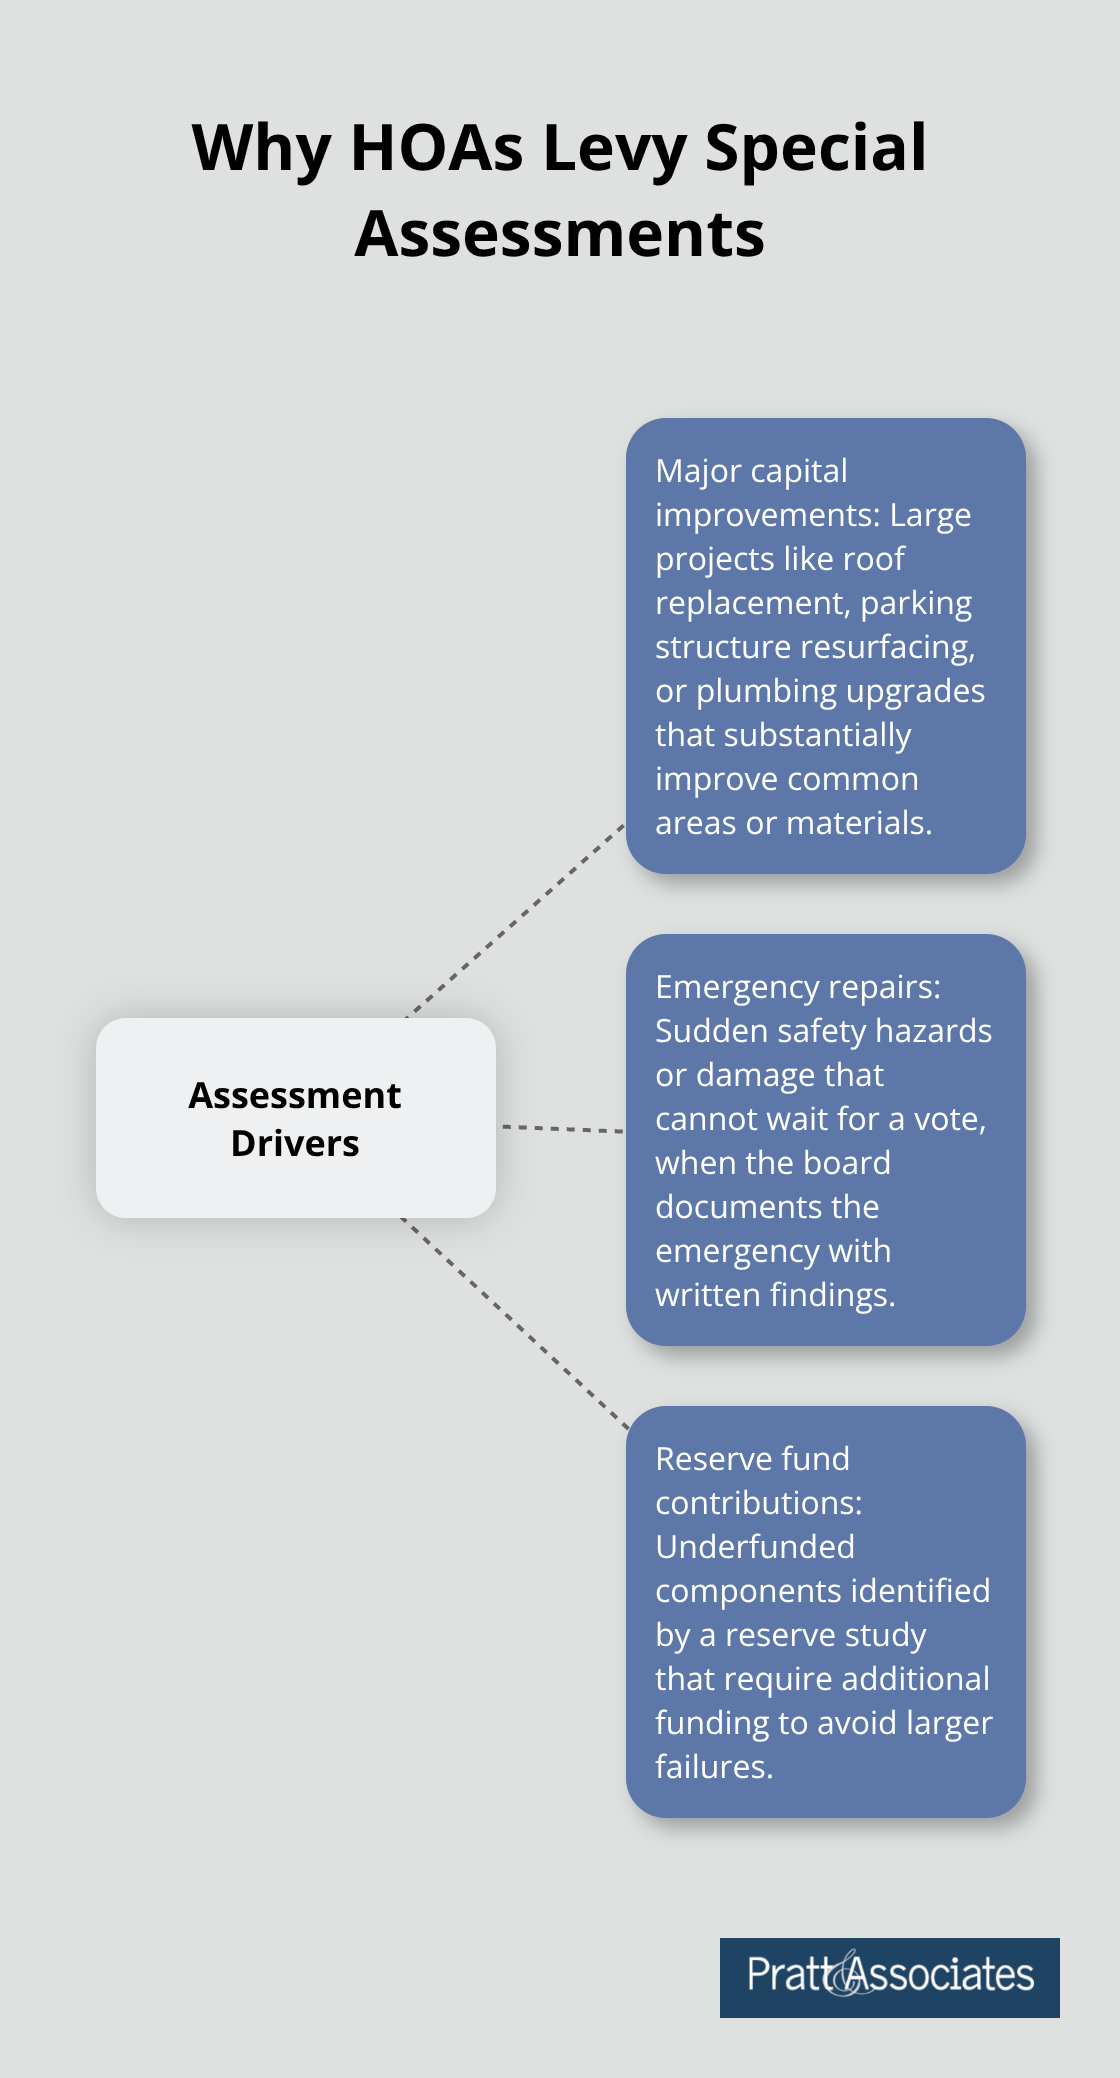
A special assessment is a one-time charge added to your HOA dues to cover a specific project or emergency expense that wasn't in the original annual budget. This might be a new roof for the clubhouse, repairing structural damage to the community pool, or replacing decades-old plumbing. The amount each homeowner pays depends on how the HOA's governing documents break down ownership percentages, and it can range from a few hundred dollars to several thousand depending on the scope of work. The Hoa Special Assessment Limit is governed by three layers: your state statutes, your community's declaration of covenants, and the board's adopted budget policies. Most states set a default cap—for example, Florida allows boards to levy assessments up to 5% of annual operating expenses without a membership vote. Beyond that threshold, you typically need homeowner approval. Your governing documents may impose a stricter limit than state law, so you always need to read those before assuming you have freedom of action. I learned this the hard way back in 2019 when we were dealing with a severe water intrusion problem in the basement parking garage of a mid-size community I was managing. The initial repair estimate came in at $280,000. Our state's default cap was 5% of annual operating expenses, which for our community worked out to roughly $45,000 per unit before requiring a vote. We were sitting at a $22,000 reserve balance. The board had no choice but to call a membership vote for anything above that threshold. Two homeowners challenged the assessment as unlawful because the board hadn't followed the proper notice period outlined in our bylaws. That mistake cost us an additional six weeks and about $18,000 in legal fees. The workaround was straightforward in hindsight: we restructured the project into phases, kept each phase below the statutory trigger, and funded Phase One through reserves while financing Phase Two with a modest short-term loan. It took longer but avoided the legal exposure entirely.
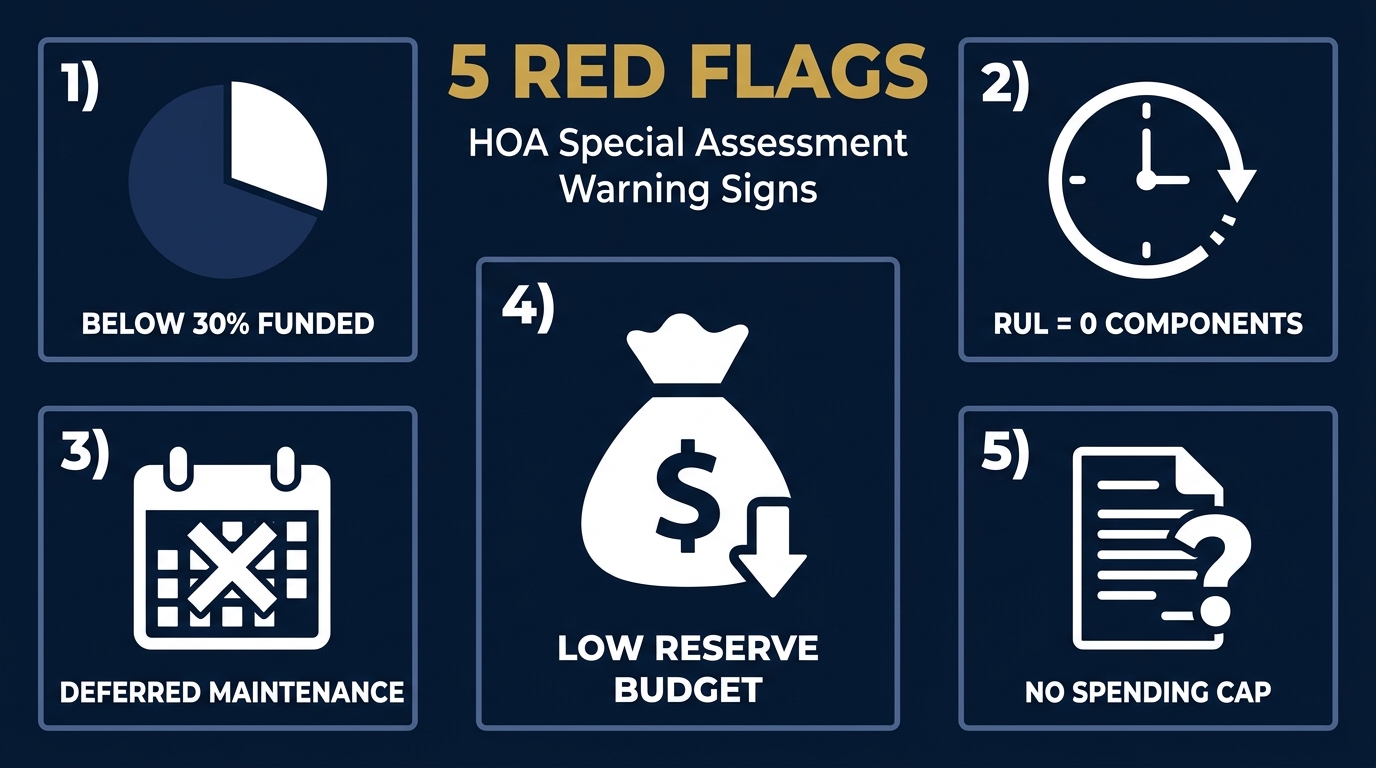
Here are the mechanics you need to understand when dealing with this. First, verify your state's specific statute on HOA special assessments. Some states like Texas and California have very detailed provisions, while others leave it almost entirely to the declarations. Second, pull your governing documents and find the section on assessments. Third, check whether your community has a reserve study and whether reserves are sufficient to cover the projected expense without triggering an assessment at all. When a board proposes a special assessment, they should provide a written justification that includes the project scope, the estimated cost, the funding source, and the per-unit breakdown. If you're a homeowner receiving one, request that documentation in writing. Boards are not required to hold a vote unless your state or your documents say so, but transparency here prevents disputes later. The biggest mistake I see is boards treating reserves as a black box. When reserves are depleted, the default assumption should not be an immediate special assessment. A construction loan or a line of credit against the association's assets often costs far less in total dollars over five years than a large one-time assessment that forces homeowners to refinance or sell. I've run the numbers on multiple occasions where borrowing at 6 to 7 percent over seven years came out cheaper than a 3,000-dollar-per-unit assessment that pushed a significant number of owners into negative equity situations.
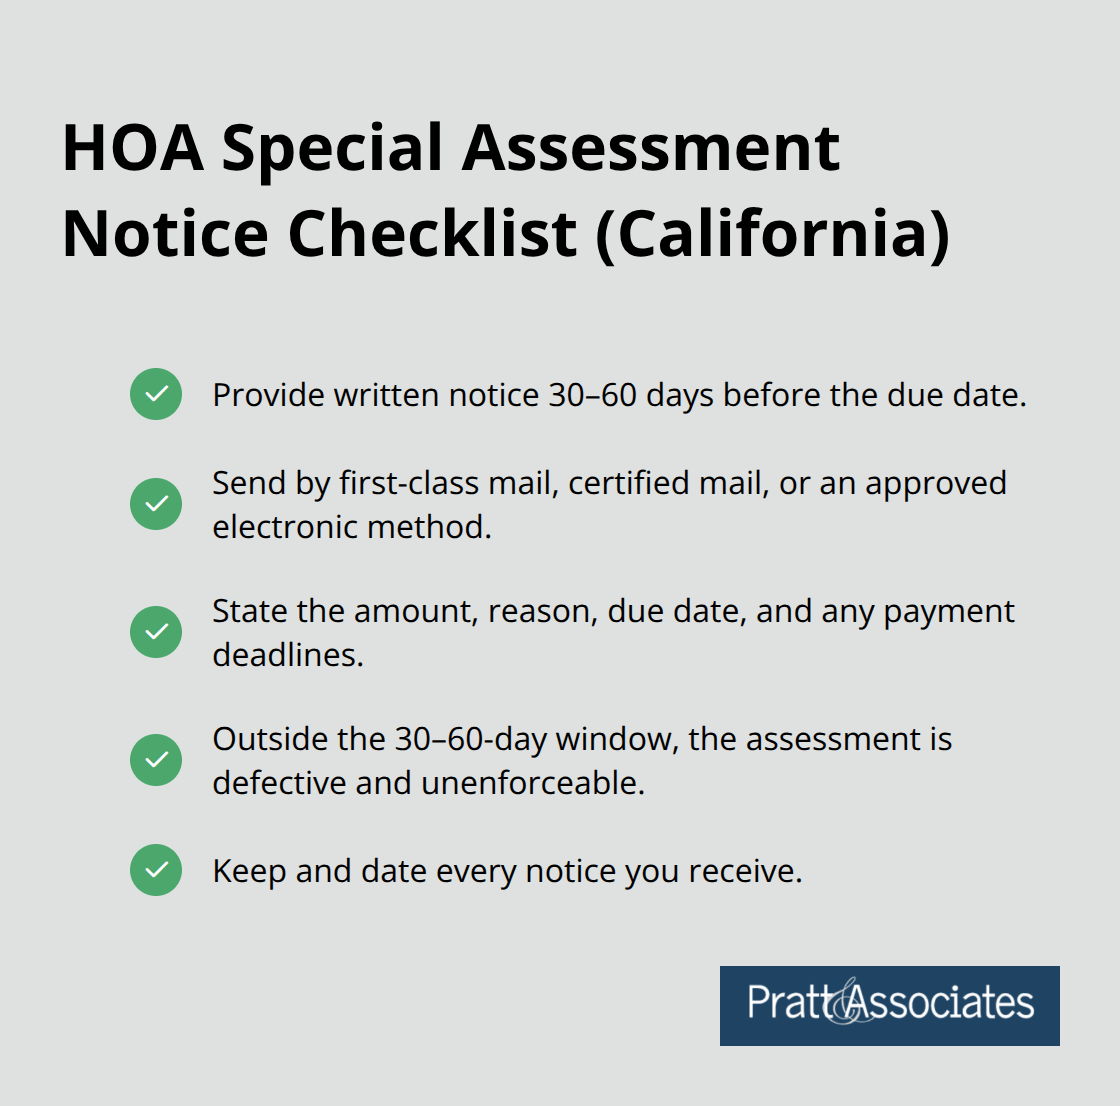
Another counter-intuitive point: some states allow boards to levy special assessments retroactively if the expense was authorized by a prior vote or is deemed an emergency. This is rare and usually contested in court, but it exists. If your board claims emergency authority to bypass normal procedures, ask for the specific statutory citation and documentation of why this qualifies as an emergency rather than a planned capital project. If you need to calculate what a special assessment will mean for your individual unit, take the total assessment amount, divide by the number of assessable units in the community, then multiply by your ownership percentage as stated in the declaration. That gives you your proportional share. Most professional management companies handle this calculation, but doing it yourself takes about ten minutes and prevents errors in billing. Community associations vary widely in how they handle these situations. Some boards communicate clearly and give homeowners 60 days to pay in installments. Others demand full payment within 30 days and place liens on properties for non-payment. Know your rights under state law before you agree to anything. If an assessment is being levied against you and you believe it is improper, your first step should be a written request for the legal basis and supporting documentation, not an immediate lawsuit.
Get the Full Details