How Home Equity Line Calculators Actually Work
Most people grab a Home Equity Line Calculator Monthly Payment tool online and plug in their numbers, then stare at the result wondering if it's real. Here's the thing — these calculators are generally accurate for estimation purposes, but they operate on assumptions that don't always match your actual loan terms. I need to walk through what's happening under the hood because the output can mislead you if you don't understand the mechanics. A HELOC calculator models two distinct phases: the draw period and the repayment period. During the draw period, you're typically only paying interest on whatever you've actually borrowed, not the full credit line. That's where most people get tripped up. They see a payment estimate based on the full credit line and assume that's what they'll owe every month. It isn't. The calculator has to ask you how much you plan to draw, at what rate, and over what term to give you a usable number.
Home Equity Line Calculator Monthly Payment: The Real Math
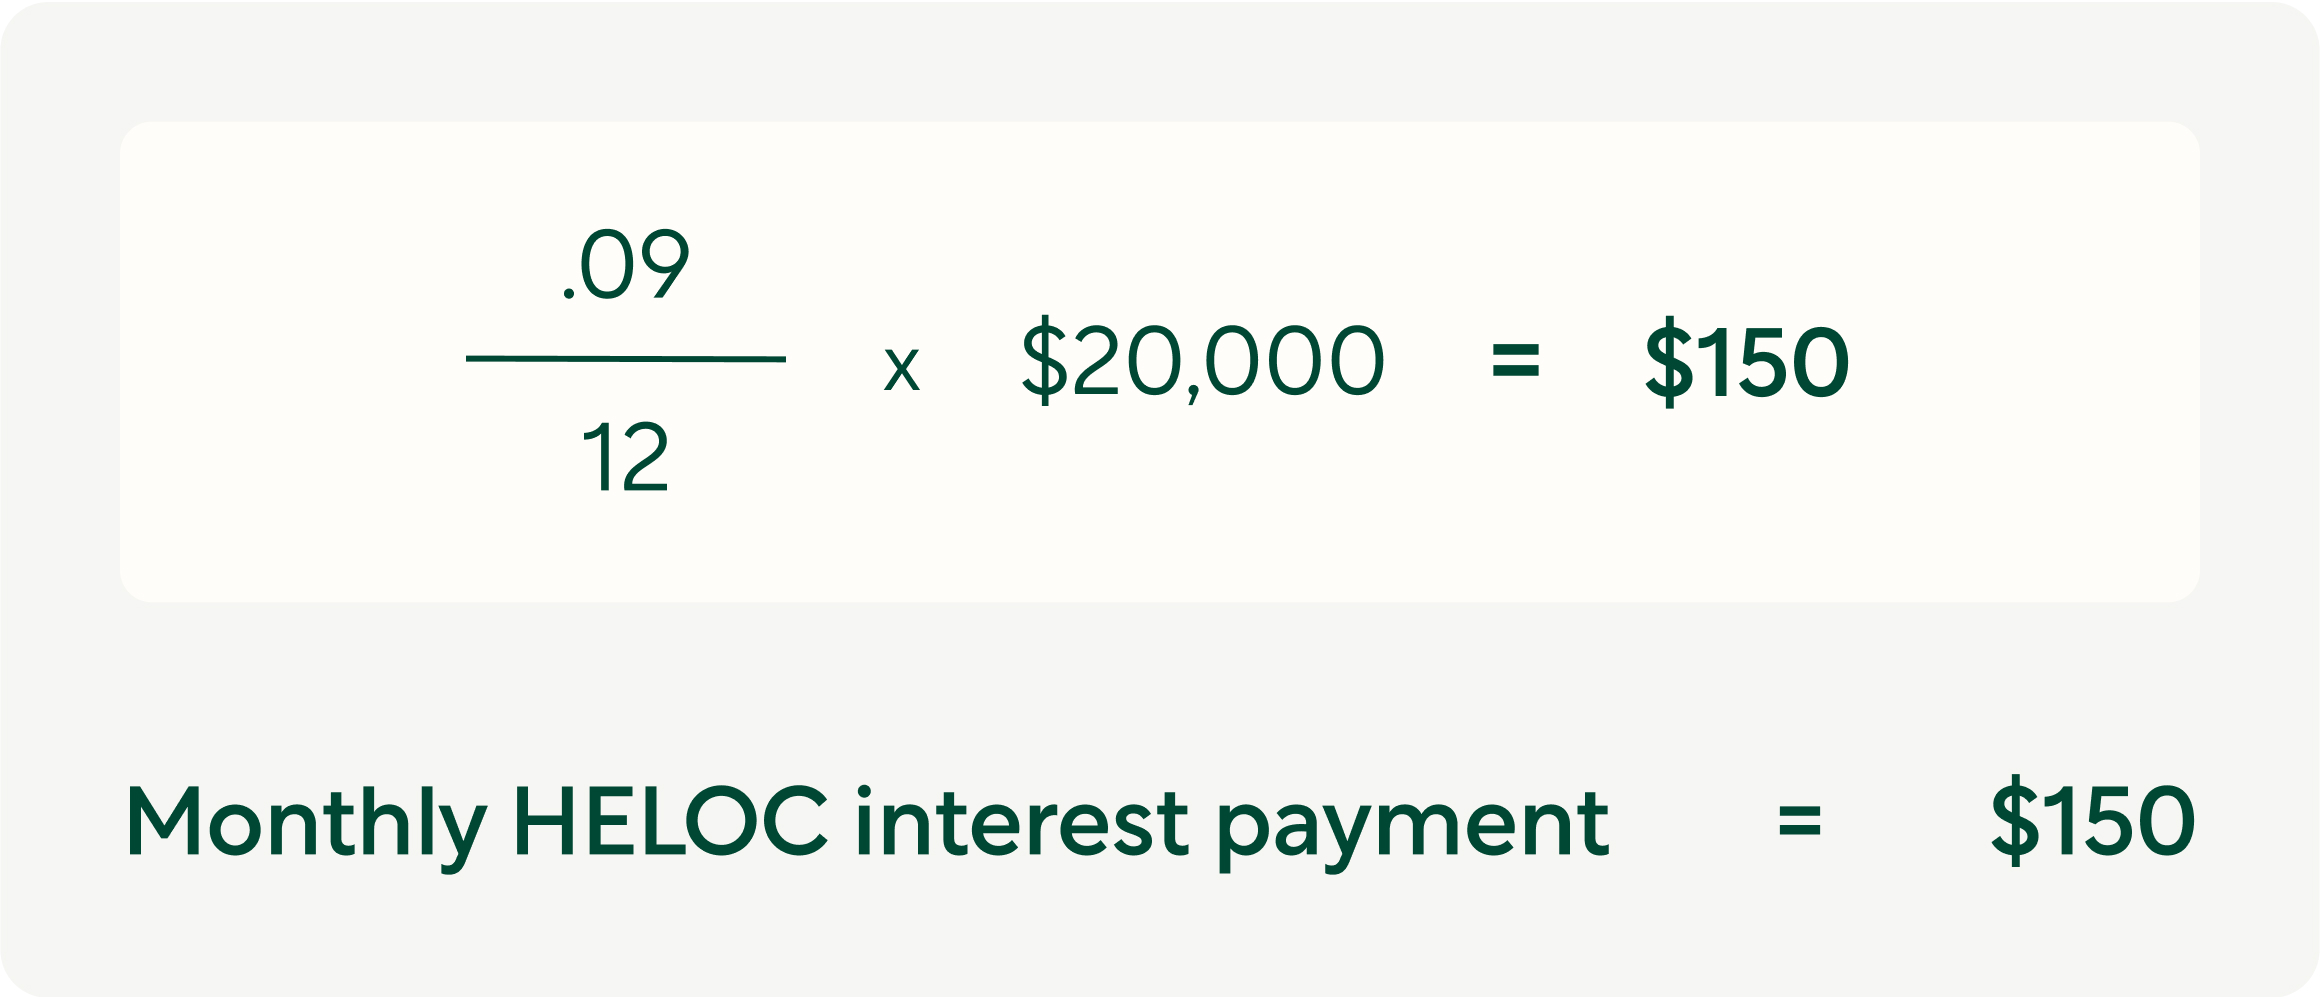
The monthly payment during the draw period is calculated as your outstanding balance multiplied by your annual interest rate divided by twelve. So if you've drawn $40,000 at 8.5% APR, your minimum monthly payment is roughly $283. But here's the catch that nobody puts in the description box — most HELOCs have an adjustable rate tied to the prime index. That means the calculator output you see today could be off by a significant amount in six months when the rate resets. During the repayment period, the calculation flips entirely. Now you're paying principal and interest over a set term, usually 10 to 20 years, using an amortization formula. The payment jumps dramatically because you're no longer just covering interest — you're actually paying down the balance. A $40,000 balance repaid over 15 years at 8.5% comes out to approximately $389 per month. That's a $106 increase from the interest-only phase, and it catches a lot of people completely off guard. I ran into a specific problem last year with a client who used a generic calculator that assumed a fixed rate throughout the entire life of the loan. His HELOC was variable, and the prime rate had risen 1.5% since he opened the line. The calculator was telling him his payment would be $290, but his actual statement came in at $372. I ended up building a custom spreadsheet that pulls the current prime rate from the Federal Reserve data and recalculates the projected payment at each reset date, then compounds that forward over the remaining draw period. It took about 40 minutes to set up, but it saved him from a nasty surprise when his next adjustment hit.
Here's something most calculators won't tell you: some lenders include a teaser rate for the first six to twelve months. The calculator shows you the standard rate, but your actual opening rate might be a full percentage point lower. Conversely, some calculators assume you'll draw the full credit limit on day one. If you only need $15,000 out of a $100,000 line, your payments will be a fraction of what the default calculation shows. When you use a Home Equity Line Calculator Monthly Payment tool, make sure you're entering the draw amount, not the credit limit. These are two different things and mixing them up is the single most common error I see. Another nuance: several lenders structure their HELOCs with a partial amortization or balloon payment at the end of the draw period. The monthly calculator won't account for this unless it's specifically built for your lender's product. You could be looking at a comfortable $300-a-month payment for eight years and then suddenly owe the entire remaining balance in one lump sum. That's not a calculator failure — it's just that the calculator doesn't know your lender's specific terms.
Get the Full Details

What These Calculators Miss
They don't factor in closing costs, annual fees, or prepayment penalties. A $350 annual maintenance fee on a HELOC is not unusual, and some lenders charge origination fees that effectively reduce your available credit before you even draw a dollar. The monthly payment number from any online calculator is purely about interest and principal — it ignores the cost of getting the line in the first place. If you're comparing HELOC offers from multiple lenders, you need to run the numbers yourself with a spreadsheet that includes those fees amortized across the draw period. I usually spread the closing costs evenly across the expected draw period months and add them to the payment estimate. It changes the comparison slightly but it's the only way to make an apples-to-apples decision between lenders who structure their fees differently. The other limitation is that calculators don't model your actual borrowing behavior over time. If you draw $20,000 in month one, pay it down to $5,000 by month six, then draw another $15,000, the calculator's static assumption about your balance will be wrong. The tool gives you a snapshot, not a timeline. For long-term planning, you need to build out a month-by-month projection or at minimum run the calculator multiple times with different balance assumptions.
I've seen people use a single calculator result and commit to a spending plan based on it, only to find out their payment was double what they expected because they hadn't accounted for the repayment phase transition. The shift from interest-only to fully amortizing payments is where the biggest financial surprises happen, and no basic calculator warns you about it explicitly. If you want something more accurate than a free online tool, I'd recommend downloading a simple HELOC amortization spreadsheet. There are a few decent ones available from financial planning forums and personal finance sites. You enter your rate, draw amount, draw period length, and repayment term, and it outputs a full payment schedule showing exactly what each month looks like. It takes about ten minutes to set up and runs in any spreadsheet application. The accuracy improvement over a basic calculator is substantial, especially when rates are variable.
Bottom Line
A Home Equity Line Calculator Monthly Payment result is useful as a starting point, not a final answer. Treat it as an estimate within a range, not a prediction. Adjust for variable rates, your actual draw amount, fees, and the repayment phase transition. Run it through a more detailed spreadsheet if you're serious about the numbers. Your lender's disclosure documents will have the exact terms — use those as your source of truth once you pick a product.