Working with HELOC Payment Calculators
Most people find these tools during the worst possible moment. They need an answer yesterday and the calculator gives them a number that feels wrong. Here is how to actually get useful output instead of wasting an hour tweaking fields that don't matter. The basic inputs are straightforward: your available credit limit, the draw period length, the interest rate, and sometimes the draw pattern. But the variables lenders use vary enough between institutions that throwing numbers into one calculator and expecting it to match your actual statement is a mistake waiting to happen. I learned this the hard way when a borrower brought me a calculator projection showing a $412 monthly payment during the draw period. Their first actual statement from the institution showed $587. The gap was the fee structure. That particular lender capitalized certain origination costs into the balance rather than billing them separately, which the generic online calculator had no way to account for.
How to Get a Reliable Home Equity Line Of Credit Calculator Payment Result
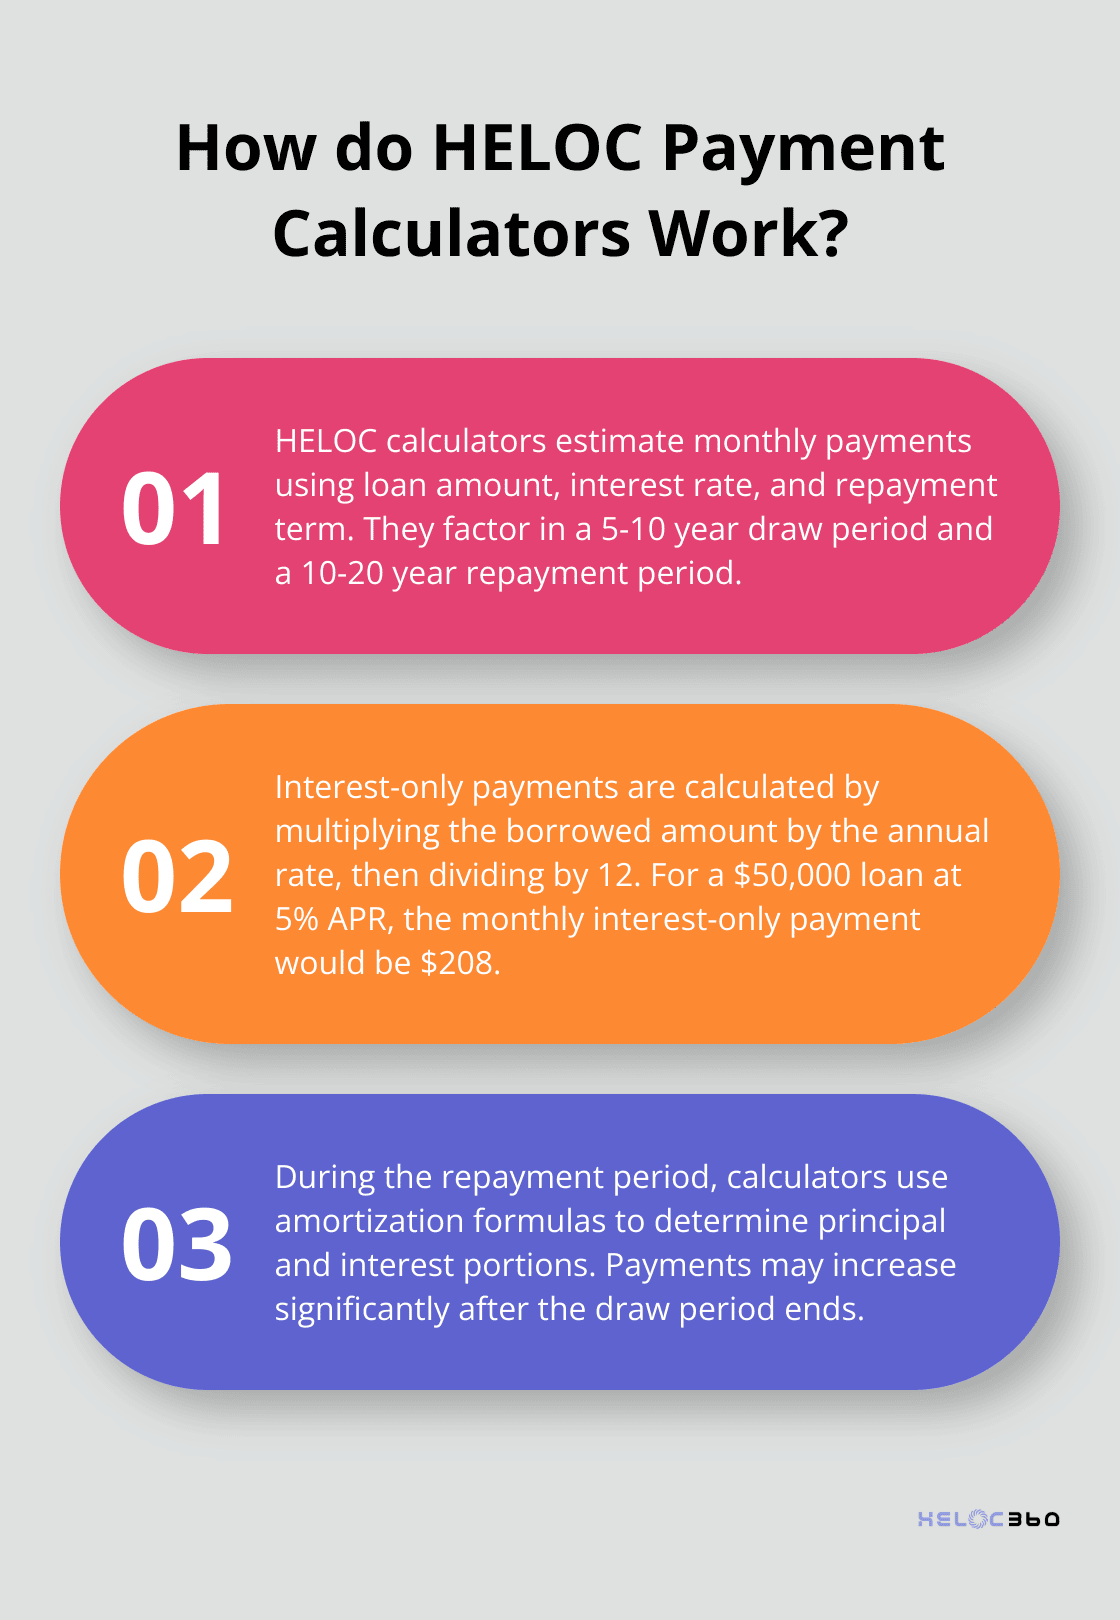
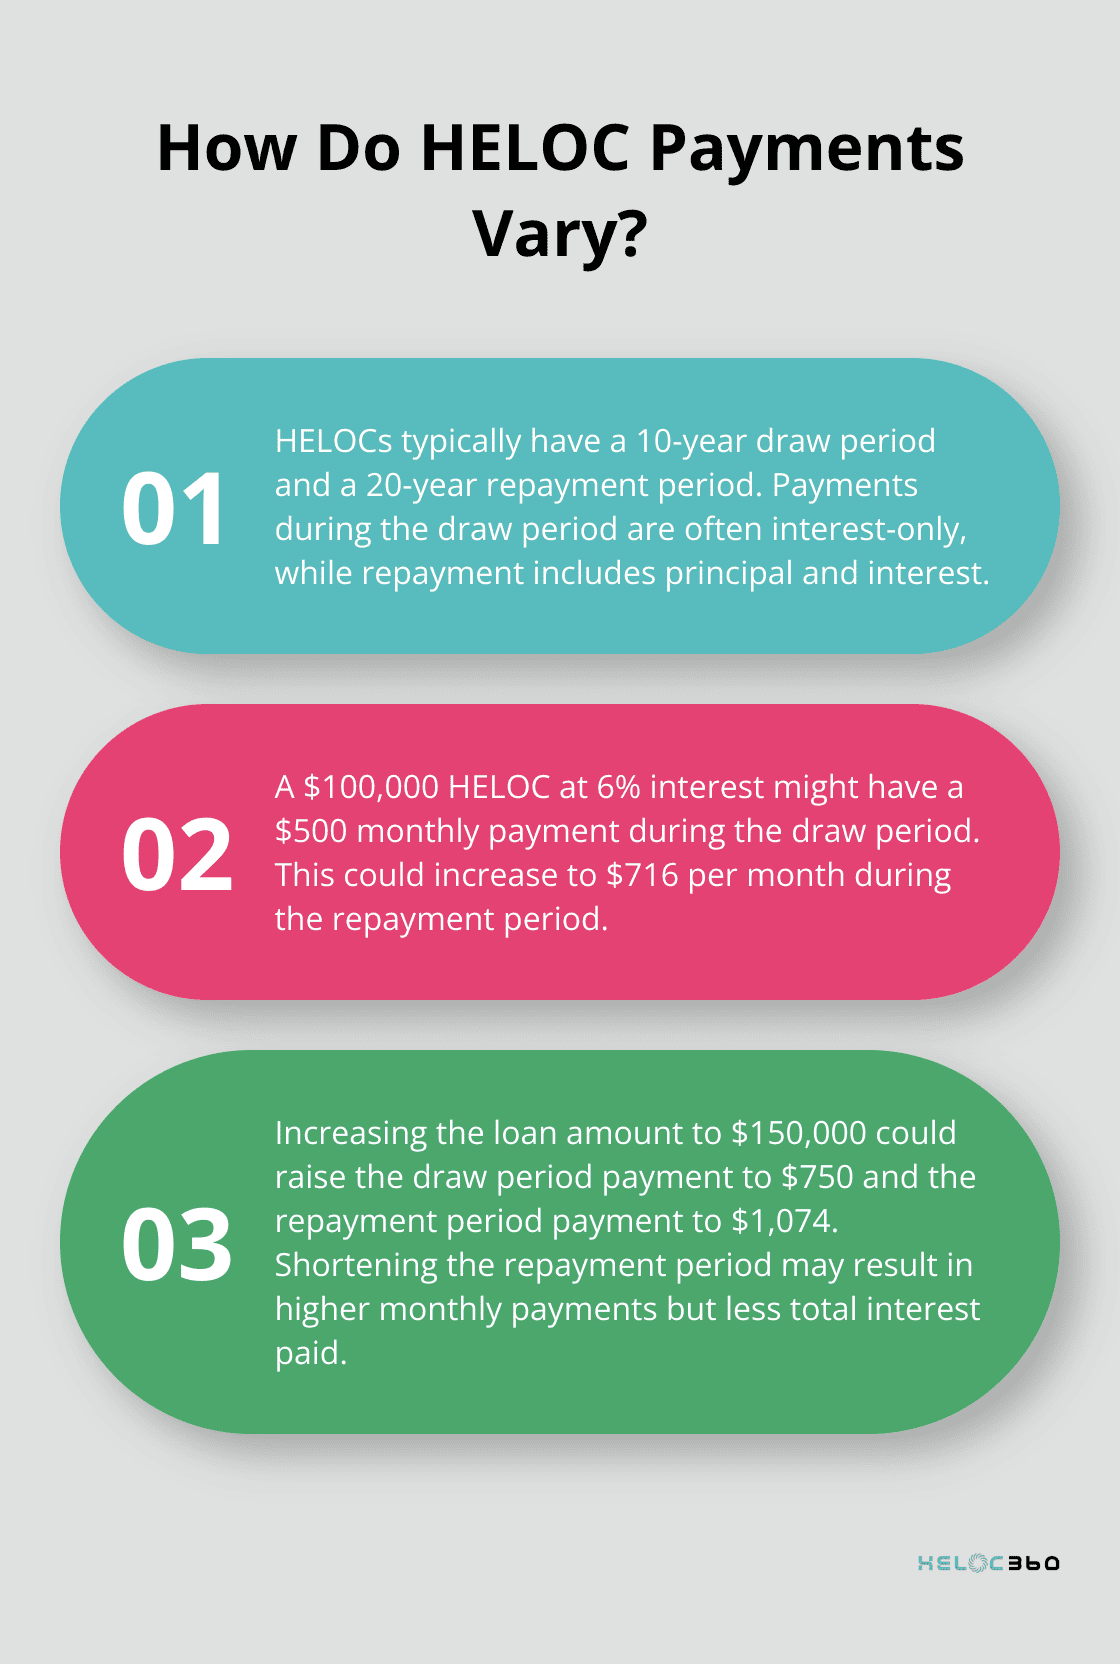
Start by confirming exactly which rate you will be charged. Lenders advertise the teaser rate first, and it is not the rate you will actually pay unless your credit profile is unusually strong. Look for the margin they add to the index. A 5/1 ARM HELOC might advertise 6.99% but could actually evaluate at 7.75% once the margin is applied. This one number changes your projected payment significantly. Next, determine whether you are looking at the draw period or the repayment period. These produce completely different payment profiles. During the draw period, most HELOCs require interest-only payments on whatever you have drawn, though some lenders calculate a minimum based on a percentage of your balance. After the draw period ends, the payment jumps because you are now paying principal and interest over a fixed term, usually 10 to 20 years, with no remaining credit access. Be precise about the draw amount. Calculators assume you withdraw the full credit limit immediately, which is rarely true. If you plan to use $40,000 of a $100,000 line, enter $40,000. Enter the full limit and you will see a payment that makes you unnecessarily anxious. Enter too little and you will underestimate the payment once you actually draw against the line.
Check whether the calculator handles the amortization during the repayment phase correctly. Some tools simply divide your outstanding balance by the number of remaining months and ignore interest. Others build a proper amortization schedule. The difference can be substantial over a 15-year repayment window. I ran into another edge case recently with a borrower whose lender used a 360-day year for interest calculations while the calculator I was using defaulted to a 365-day year. The monthly payment showed up about $3.50 higher on the actual statement. Small discrepancy, but it adds up when you are budgeting. I switched to a calculator that allowed me to select the day-count convention and matched the result within a dollar. Another common issue is variable-rate modeling. Most calculators show you a single static payment based on the current rate. If rates move, your payment moves with them. A few tools let you model different rate scenarios, which is much more useful. If yours does not, you should at least run three calculations: one at the current rate, one 1 percent higher, and one 1 percent lower. This gives you a realistic range rather than a single misleading number.
Get the Full Details

Something else people overlook is the impact of partial payments made before the statement closes. If you draw $50,000 on the 15th of the month and your billing cycle starts on the 1st, you may owe interest on that full $50,000 for 15 days before any payment is due. Some simplified calculators skip this timing detail and assume a full month of interest regardless. It is a minor point but it affects the very first payment you see. There are also calculators that factor in annual fees or closure costs, which most free ones do not. If your lender charges a $75 annual maintenance fee, it gets added to your balance and accrues interest. Running a calculation that omits it understates your true cost by roughly $75 plus however much interest that amount generates over the life of the loan.
What the Numbers Actually Tell You
A HELOC calculator payment figure is a projection, not a guarantee. It reflects the assumptions you fed into it. If those assumptions are sloppy, the output is useless. The most accurate approach is to pull your actual loan estimate or closing disclosure from the lender and enter those exact figures into the calculator. Use the note rate, not the APR. Use the actual credit limit and the amount you expect to draw, not the maximum possible. And confirm whether the lender charges any upfront fees that get folded into the balance. When the draw period is still active and you are only making interest payments, the calculator will usually show a relatively low monthly amount. Do not let this create false confidence. The repayment phase payment is what most people forget to check. Take the outstanding balance at the end of the draw period, subtract any principal you have paid down, and run that through the calculator with the full amortization term selected. The resulting number is what you will actually be paying for the next decade or so. One thing worth noting is that some lenders use a two-tier calculation method. During the draw period, the minimum payment is the greater of either the interest accrued or a small percentage of the outstanding balance, typically 1 to 2 percent. This means if your balance is large, your minimum payment might be significantly higher than pure interest alone. Most generic calculators do not model this floor payment, so you could be underestimating your obligation during the later years of the draw period.
If you need something more precise than a free online tool provides, there are downloadable spreadsheets that let you adjust day-count conventions, fee structures, and partial draw schedules. They are not glamorous but they are substantially more accurate than the average browser-based calculator. I keep one at hand and it has saved me from recommending incorrect payment figures multiple times. At the end of the day, a Home Equity Line Of Credit Calculator Payment output is only as reliable as the data behind it. Verify your rate, your draw amount, your fee structure, and your amortization assumptions before you trust the number. Run a second scenario at a slightly higher rate to see how sensitive your payment is to rate movement. And always cross-check the draw-period projection against what the calculator shows for the repayment phase, because that is where most people get caught off guard.