Home Equity Line Of Credit Qualification Calculator
Verma
2025-08-29
How Home Equity Line Of Credit Qualification Actually Works
Most people treat a Home Equity Line Of Credit Qualification Calculator like it will tell them exactly what they will get approved for. It won't. It tells you whether you clear the basic thresholds. Everything after that depends on who is looking at your file and how tired they are on a given Tuesday afternoon.
What the Home Equity Line Of Credit Qualification Calculator Actually Does
The calculator is just arithmetic wrapped in lender policy. You enter a few numbers and it checks two constraints most banks enforce simultaneously.
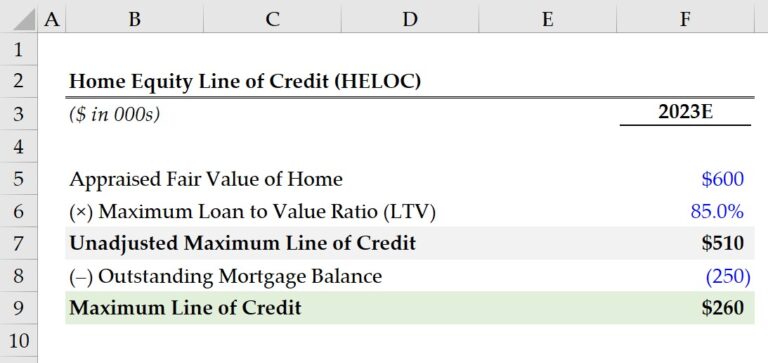
Constraint one is the combined loan-to-value ratio. Most lenders cap your total secured debt at 80 to 85 percent of your home's appraised value. Constraint two is the debt-to-income ratio. Your total monthly obligations divided by your gross monthly income usually must stay below 43 percent, sometimes higher if your credit profile is strong.
Inputting numbers is the easy part. Getting the right numbers is where people break things.
Use the current market value from a recent comparable sale or a price opinion, not what you paid. Use the remaining principal balance, not the original loan amount. Use gross income before taxes and deductions. Use minimum monthly payments for revolving accounts, not your actual spending amount.
I ran a file for a client last year where her calculator estimate showed strong approval, then got rejected on DTI. She had entered her actual credit card balance instead of the minimum payment. Her total monthly debt looked low. It wasn't. The underwriter used the minimum, which pushed her DTI over the ceiling. She fixed it by pulling her credit report, confirming each card's minimum, and recalculating. We resubmitted the next day and it cleared.
Key Variables That Matter More Than People Think
Credit score is the obvious one. Most HELOC programs want 680 or higher for decent terms. A score below 620 usually disqualifies you from the best pricing. A score above 760 helps with rate locks, but does not guarantee approval if your other numbers are weak.
Payment history matters more than most calculators reflect. A single late payment in the past two years can push an otherwise solid applicant out of automated underwriting. You end up with manual review instead, which adds weeks.
Employment length matters too. Two years of consistent income is the baseline. Gap-filled resumes get flagged. Self-employed applicants often face additional scrutiny because lenders average income over two tax years and sometimes adjust for deductions.
Existing liens get forgotten. A second mortgage, a home equity loan, or even an IRS lien counts toward your CLTV. The calculator will include it if you enter it correctly. Skip it and your result is wrong.
Where the Math Falls Apart
The qualification calculator has real limitations. It assumes the home value you enter is what the lender will accept. Appraisals frequently come in lower, especially in fast-moving markets. When that happens, your effective CLTV jumps and your approved amount shrinks.
It does not account for lender-specific overlays. Some banks require 700 for approval. Others require 660. The tool cannot know your local branch's preferences.
It also ignores rate environments. A qualification estimate today may not hold if rates move before you submit. Variable-rate products like HELOCs make this worse. Your qualifying rate is usually based on current index values, which shift monthly.
I learned this the hard way with a contractor client whose calculator showed he qualified for $120,000. He pulled credit reports for three lenders over ten days. By the time he submitted, two of the three had tightened their DTI limits and his estimate dropped to $85,000. He lost the window he needed for a property acquisition. The lesson is straightforward. Get a soft-pull pre-qualification early. Lock the terms if the lender allows it. Do not rely on a calculator result sitting unused for more than two weeks.
Counter-Intuitive Details Most Guides Miss
Here is something people rarely expect. A higher credit score does not always improve your outcome. Lenders sometimes cap the benefit above 740. Pushing from 720 to 780 may lower your rate by a fraction of a point, but it does not meaningfully change your approval odds. The DTI and LTV ratios matter more at that level.
Another detail. Some calculators treat your primary mortgage as a fixed number. If you have an interest-only period or adjustable-rate feature, the payment changes over time. Underwriters sometimes use the fully indexed rate rather than the current payment when calculating risk. The tool shows one number. The reality is higher.
How to Use This Tool Without Misleading Yourself
Enter your data carefully. Double-check every field against real documents. Use your most recent statement balances, not guesses. Record all joint debts, even if someone else pays them. Joint obligations count against your DTI regardless of who writes the check.
Run the calculation with two or three different tools if available. Results will vary by lender model. Look for the lowest estimate and build from there.
Take the result to a real lender for a pre-qualification. A soft credit pull takes minutes. It reveals whether your numbers align with actual underwriting standards. If the pre-qualification differs significantly from the calculator, investigate why. The gap usually points to something you overlooked or a lender overlay you were unaware of.
When a Calculator Is Useless
Do not bother if your credit is below 600. Do not bother if you have recent foreclosure or bankruptcy, unless you understand the waiting periods and have documentation ready. Do not bother if your home value has dropped sharply and you are underwater. The calculator will give you a number. The number will not translate to approval.
In those cases, work with a mortgage professional who understands secondary market programs. A qualification calculator is a starting point, not a verdict. Treat it that way and you save yourself time and a few unnecessary hard pulls.
Gallery Home Equity Line Of Credit Qualification Calculator
Home Equity Line of Credit (HELOC) Payment Calculator 2026
Home Equity Line of Credit Calculator | Excel - Google Sheets
Home Equity Line of Credit (HELOC) Calculator
HELOC Calculator - Home Equity Line of Credit Payment Estimator
Home Equity Line of Credit (HELOC) | Formula + Calculator