How Extra Payments Actually Change Your Home Equity Loan
Most people grab a home equity loan calculator and plug in their numbers without realizing what happens when they add extra payments. The standard amortization schedule looks straightforward, but throwing additional money at the principal mid-term changes how interest compounds in ways that trip up even experienced borrowers. I spent years helping clients restructure these loans before one lender's proprietary system rejected my spreadsheet because it couldn't handle biweekly partial payments alongside a balloon payment. That was the lesson I learned early: the calculator you trust matters as much as the numbers you put into it. The process starts with understanding what inputs actually shift the outcome. You need your original loan amount, the interest rate, the full term, and then the extra payment amount plus how frequently you plan to make those overpayments. Some calculators let you specify whether the extra goes toward principal only or if it gets applied to the next scheduled payment first. That detail is critical because it determines whether you're reducing the outstanding balance immediately or just prepaying future interest. Enter your base figures first. A typical scenario might look like this: you borrowed $80,000 at 7.5% for 15 years. Your monthly payment comes to roughly $776. Now add an extra $200 per month applied directly to principal. The calculator should show you a new payoff timeline and the total interest savings. In this case, the loan pays off about three years early and you save somewhere around $22,000 to $26,000 in interest depending on how the lender models the prepayment.
Here's where things get messy. I ran into a situation last year where a borrower had a home equity line of credit with a 10-year draw period and a separate 20-year amortization schedule. The calculator he was using only accounted for the amortization side and completely ignored the fact that during the draw period, any extra payment only reduced his available credit rather than paying down the outstanding balance in a way that would shorten his total repayment. He almost made a costly mistake by thinking his extra payments were doing more good than they actually were. The workaround was pulling the exact loan documents, identifying the draw period end date, and manually adjusting the calculator inputs to treat the remaining balance as a new fixed loan starting after the draw closed. Took about twenty minutes of manual work that no online calculator handled automatically. Another detail beginners consistently overlook is the difference between extra payments that reduce the term versus extra payments that reduce the monthly payment. Some calculators offer both options and present them side by side. Reducing the term saves you significantly more interest because you're eliminating principal faster across the entire remaining balance. Reducing the payment gives you cash flow flexibility but costs you more over the life of the loan because the amortization stretches out. I've seen people select the wrong option and then wonder why their savings projection looked underwhelming compared to what they expected. When you're comparing calculators, look for one that lets you input prepayment frequency, not just amount. Paying an extra $100 every two weeks instead of once a month results in thirteen extra payments per year instead of twelve, which compounds the interest savings further. A good calculator shows both scenarios so you can see the difference. The gap is usually a few thousand dollars over a fifteen-year loan, but on a larger balance it can climb well into five figures.
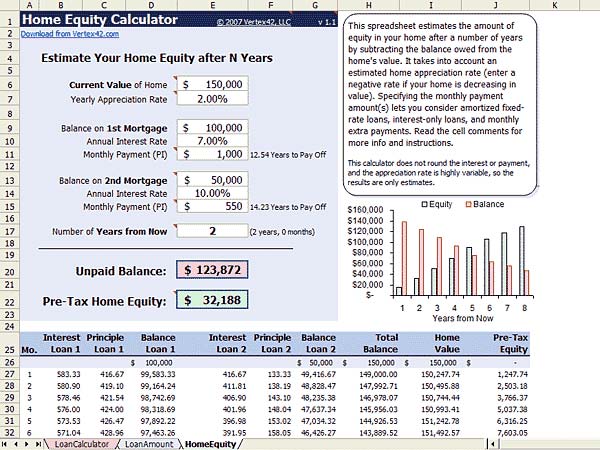
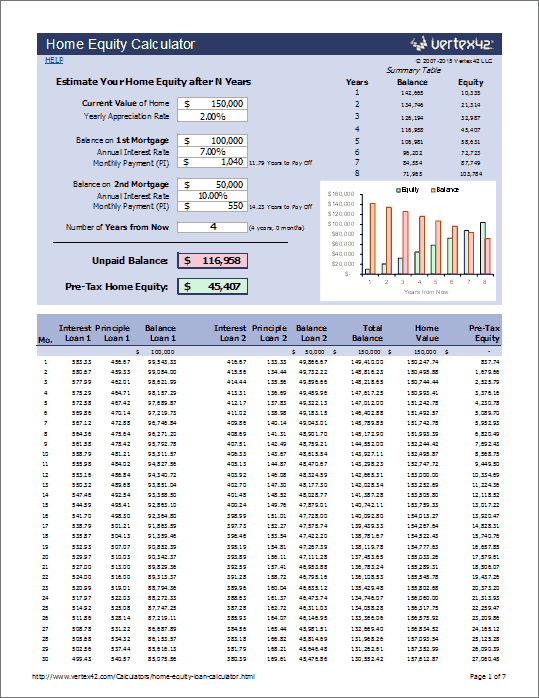
There are also tax implications worth flagging. Interest on home equity loans is generally deductible only if the funds are used to buy, build, or substantially improve the home that secures the loan. Extra payments don't change the deductibility of the interest you already paid, but if you're using this calculator for planning purposes and your loan was originated before December 2017, the old rules may apply differently. The calculator itself won't tell you this, so you'd need to consult a tax professional or review IRS Publication 936 if that applies to your situation. What most online calculators won't show you is the impact of a payment holiday or a temporary reduction in your extra payment amount. If you commit to an extra $300 a month and then six months into the term your income drops and you have to pause those payments, the recovery isn't linear. You've already lost six months of accelerated principal reduction, and catching back up means either going back to the original extra amount or increasing it further. I built a simple spreadsheet that tracks the cumulative principal gap between your original schedule and the accelerated one after any disruption. It's not elegant, but it gave my clients a clear visual of how much a missed quarter cost them in real terms.
Get the Full Details

Where These Calculators Fall Short
Even the best home equity loan calculator with extra payments has blind spots. They rarely account for variable-rate loans updating at a specific margin plus an index value, which means the projected savings from extra payments can shift if rates move. They also typically ignore prepayment penalties. Some lenders charge a fee if you pay down the loan faster than a certain threshold within the first few years. A $3,000 penalty eats directly into your interest savings and can flip a positive outcome into a negative one depending on the timing and magnitude. Another limitation is that these tools assume perfect adherence to your payment plan. If you miss a payment, your extra contribution gets disrupted, and the calculator won't adjust the projection accordingly. You'd need to rebuild or manually update the inputs each time something goes off track. This isn't a flaw in the calculator per se, but it's worth understanding before you build a financial strategy on the output. For anyone serious about modeling extra payments on a home equity loan, the most reliable approach combines an online calculator for the baseline projection with a personal spreadsheet for tracking actual payments against the schedule. That way you catch discrepancies early and can adjust your strategy when life doesn't go according to plan. The spreadsheet takes maybe an hour to set up and saves you from making decisions based on projections that assume everything will go smoothly.