What Home Flip Actually Is
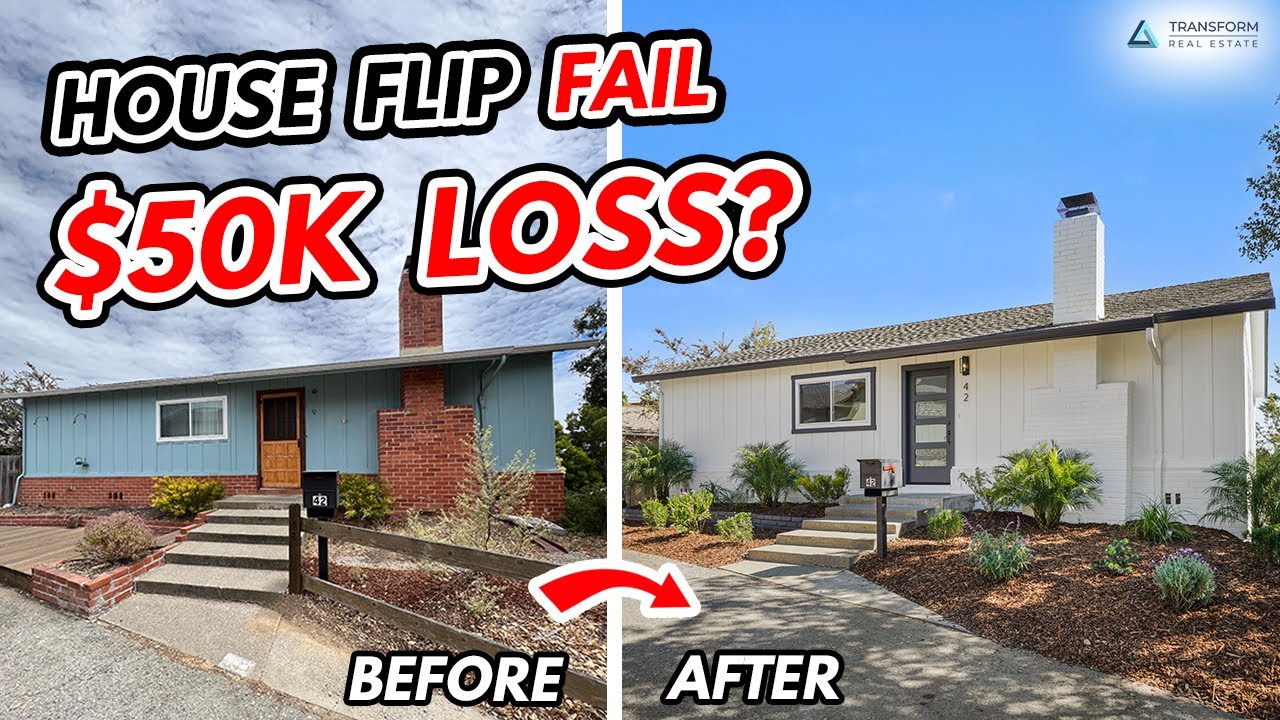
I keep seeing people ask about Home Flip on forums, and the confusion is pretty thick. Home Flip is essentially a property turnaround strategy where you buy a distressed asset, fix it up, and sell it for a profit within a relatively short timeframe. It is not passive income. It is not set-it-and-forget-it. You are taking on debt, managing contractors, navigating inspections, and hoping the market does not turn while your remodel is half done. The core loop is simple on paper: buy below market value, invest in value-add improvements, sell at or above asking. The devil is entirely in the details, and the details are what bankrupt people who treat this like a game.
How Home Flip Actually Works in Practice
I have done four flips in the past six years. Two were profitable. One broke even after you count the sweat equity. The fourth is still sitting in escrow because the buyer got cold feet and the inspection found plumbing that went back to the 1970s. Here is the actual process, stripped of the YouTube gurus: First, you source the deal. That means driving neighborhoods, checking public records for absentee owners, looking for motivated sellers, or working with a buyer's agent who understands you want problem properties, not show homes. The best deals never hit the MLS. They are whispered about at local hard money lender meetups or passed around between contractor crews.
Second, you underwrite the deal. This is where most beginners die. You need to know your After Repair Value, or ARV, before you write a check. Get comparable sales from the last sixty days, not the last year. A market moves fast. Then factor in every cost: purchase price, closing costs, holding costs, rehab budget, realtor commissions, and a contingency buffer of at least fifteen percent on the rehab. If the numbers do not work with that buffer baked in, walk away. Third, you close and rehab. Contractor selection matters more than people admit. The cheapest bid is not your friend. I learned this the hard way on my second flip when my drywall guy quit mid-project and left behind unfinished corners that took another crew three weeks to fix. Always get references, check licenses, and pay retainers to established crews, not guys with a truck and a Facebook page. Fourth, you sell. Staging helps. It is not magic, but it reduces time on market by maybe two to four weeks in most markets, and that saves you carrying costs. Pricing correctly from day one beats chasing the market down later.
Get the Full Details
The Math Behind a Realistic Home Flip
Let me walk through a real example from my last successful flip. Purchase price was 145,000 on a 3-bed, 2-bath in a transitioning neighborhood. ARV based on comps came to 235,000. Closing costs on buy side ran about 3,500. Rehab landed at 38,000, which included a kitchen update, new HVAC, flooring throughout, and fixing a foundation crack that I did not discover until demo started. That foundation issue ate into my timeline by three weeks and cost an extra 6,200. The holding costs for those three weeks added another 1,800 in interest and utilities. Selling costs came to roughly 14,000 with agent commissions and seller concessions. Total investment: 207,500. Sale price: 232,000. Profit before taxes: 24,500. That is a twelve percent return on about five months of work. Not glamorous, but it is honest. Any flip calculator showing you thirty percent returns without accounting for hidden repairs is selling you something.
Where Home Flip Falls Apart
This strategy does not work in every market. If you are in a area with low turnover, tight inventory, or prices that have already run ahead of rents, the spreads get thin fast. I watched a guy in Phoenix try to flip a 1980s ranch in 2024 and walk away because the comps were inflated by speculative cash buyers and he could not justify the purchase price without eating his margin. Another failure point is over-improving. Putting a forty-thousand-dollar kitchen in a thirty-five-thousand-dollar neighborhood does not give you a forty-thousand-dollar home. Buyers in that price tier are not paying for quartz counters. They are paying for location and move-in readiness. Match your renovation budget to the neighborhood ceiling, not your fantasy. Financing risk is real too. Hard money loans carry rates between eight and twelve percent, sometimes higher. If your flip stalls, those payments compound quickly. I had a property sit for eleven weeks waiting for permit approval and the interest alone was eight thousand dollars. Budget for delays as if they are guaranteed, because they are almost always guaranteed.
Alternatives If Home Flip Feels Too Risky
If the above sounds exhausting and expensive, it probably is. Consider rental properties if you have a longer time horizon and want cash flow over quick appreciation. BRRRR strategy, which stands for Buy, Rehab, Rent, Refinance, Repeat, lets you tie up less capital per property once you are comfortable with the rehab side. Or just buy and hold single-family rentals and let compounding do the work over ten to fifteen years. There is nothing romantic about patience, but it rarely blows up in your face the way a leveraged flip can. The key takeaway is that Home Flip is a viable strategy only if you treat it like a small business, not a side hustle. You need capital reserves, realistic underwriting, contractor relationships, and the emotional stability to handle surprises without panicking. Most people skip that last one and pay for it later.