Understanding How a Home Line of Credit Works Before You Plug Numbers Into a Calculator
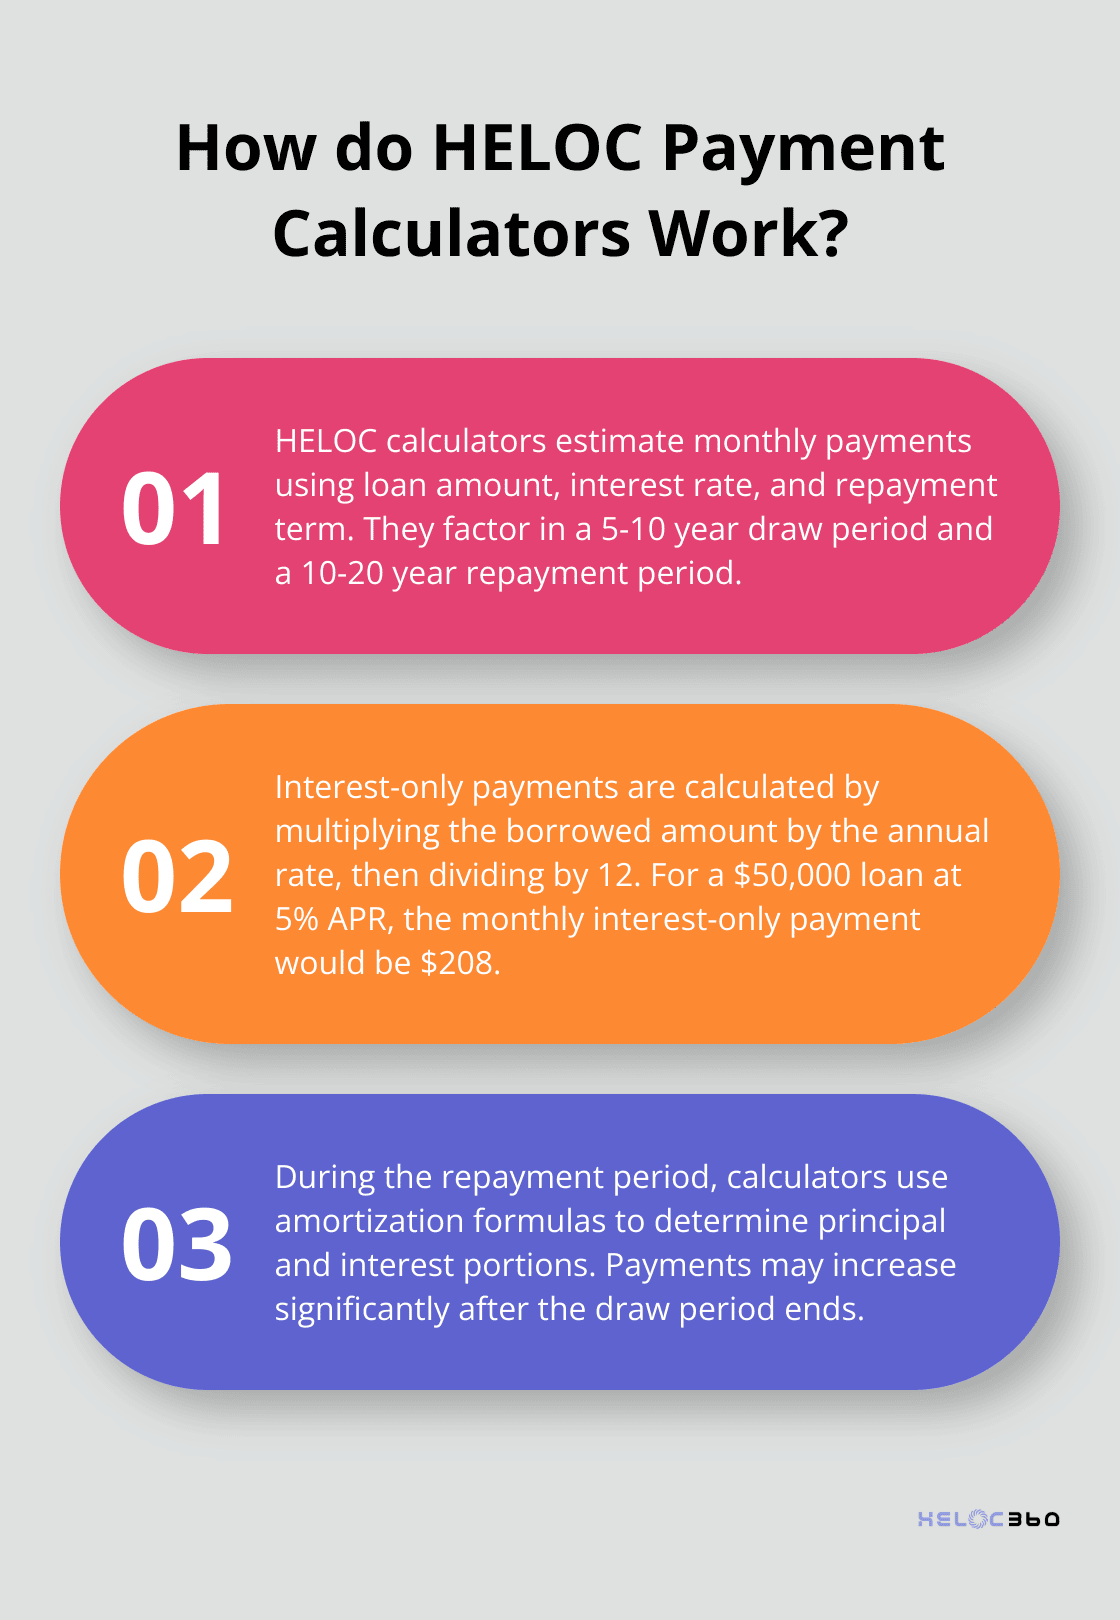
A home line of credit is basically a revolving loan secured by your house. You have a credit limit, you draw from it as you need, and you only pay interest on what you've actually borrowed. The payment structure is different from a standard mortgage or car loan, which is why people often get confused about what they're going to owe each month. The main payment formula breaks down into two parts: interest on the outstanding balance and any required principal payment, if your lender mandates it. Most HELOCs during the draw period only require interest payments, but once you enter the repayment period, things change fast. That shift is where most people get caught off guard.
Using a Home Line Of Credit Payment Calculator
A Home Line Of Credit Payment Calculator takes your credit limit, the amount you've drawn, the interest rate, and the remaining term to estimate your monthly payment. Some calculators also let you model the draw period versus the repayment period separately, which is the more useful approach since those two phases operate on completely different math. Here's how I usually walk through it. First, you need the current outstanding balance, not your credit limit. The credit limit means nothing for payment calculation purposes. Second, you need the variable rate if it's a HELOC, which most are. Lenders quote an index rate plus a margin, so make sure your calculator accounts for the fully indexed rate, not just the teaser rate they advertise. Third, enter the remaining months in your draw period and the remaining months in your repayment period. These are separate inputs that most cheap online calculators lump together incorrectly.
What Most Calculators Get Wrong
I've seen hundreds of people use these tools and come away with wildly inaccurate numbers. The biggest issue is the amortization assumption. Some calculators assume you'll pay off the entire balance over the full repayment term using a standard amortization formula. That sounds reasonable until you realize most HELOCs use a different method where the minimum payment is calculated as a percentage of the outstanding balance, not a fixed amortizing payment. The difference can be thousands of dollars per month. Another common problem is ignoring the draw period entirely. If you're still in the draw phase and only making interest-only payments, your calculator should reflect that. Once the draw period closes and the repayment period begins, your payment jumps because you're now paying both principal and interest over a shorter window. A good calculator models both phases distinctly.
Get the Full Details

A Real Problem I Encountered
Last year I was helping someone review their HELOC payment estimate and the calculator they were using showed a monthly payment of around $800 for a remaining balance of about $45,000 over ten years. When I ran the same numbers manually using the actual amortization schedule from their lender, the payment came out closer to $1,200. The calculator was using a standard loan amortization formula instead of the balloon-style repayment structure their HELOC actually used. Their lender required the full balance to be paid or refinanced at the end of the term, which changes the math significantly. The workaround was straightforward. I pulled the actual amortization table from their loan documents and built a spreadsheet that mirrored the lender's calculation method. It took about twenty minutes, and it gave them a number they could actually trust. That's the thing about these calculators, they're only as good as the assumptions baked into them, and most assume a standard installment loan structure when HELOCs rarely work that way.
Interest Rate Volatility Matters More Than You Think
HELOC rates are almost always variable, tied to the prime rate or a similar index. A calculator that uses a single fixed rate gives you a snapshot, not a realistic projection. If rates move up two points over the life of the loan, your payment could increase by thirty to forty percent. Some calculators let you input an assumed rate change, but most don't, and the ones that do often make it unnecessarily complicated. A practical approach is to run the calculation at three different rate scenarios: your current rate, a rate two points higher, and a rate one point lower. That gives you a range instead of a single number, which is actually more useful for decision-making. Budgeting for one specific payment is a trap when your rate can change every adjustment period.
Pitfalls to Avoid
Don't confuse your available credit with your outstanding balance. Entering your credit limit instead of what you actually owe will inflate your payment estimate dramatically. Don't ignore any fees that get rolled into the balance, like closing costs or annual maintenance fees, because those increase the principal and therefore the interest charge. And don't forget about prepayment penalties, some HELOCs charge a penalty if you pay off the balance early during the first few years, which changes the calculus entirely if you're planning to consolidate debt or refinance. The biggest mistake I see is people treating a HELOC like a second mortgage with a fixed payment. It isn't. The payment fluctuates with the rate and with how much you've drawn. A calculator can help you estimate, but it can't account for every variable your lender might throw at you, like a rate cap that kicks in after a certain adjustment or a mandatory payment increase that triggers when your balance exceeds a threshold.
When a Calculator Isn't Enough
If your situation involves a large balance, a short remaining term, or an especially volatile rate environment, online calculators will give you a rough idea at best. In those cases, the most reliable method is to request an amortization schedule directly from your lender. They're required to provide one if you ask, and it will show exactly how each payment is split between interest and principal over the life of the loan. It takes five minutes to email the loan servicing department and ask for it, and the document is usually sent within a business day. There's also the option of having a financial advisor or a mortgage broker model the payment under different scenarios, which can take an afternoon but saves you from making decisions based on incomplete or inaccurate estimates. I've had people come to me after they'd already committed to a payment plan based on a calculator that was off by several hundred dollars a month. It's a fixable problem, but it's unnecessary stress.
The Bottom Line on Accuracy
A Home Line Of Credit Payment Calculator is a useful starting point, not a final answer. It gives you a directional sense of what to expect, but the accuracy depends heavily on whether it accounts for draw versus repayment phases, variable rate adjustments, and the specific amortization method your lender uses. The tools from major banks tend to be more reliable than generic online calculators because they're built around actual loan products. Generic calculators are fine for quick estimates, but if you're making a financial decision based on the number, double-check it against your actual loan documents or run it through a lender-provided tool.