What a Home Line Of Equity Calculator Actually Does
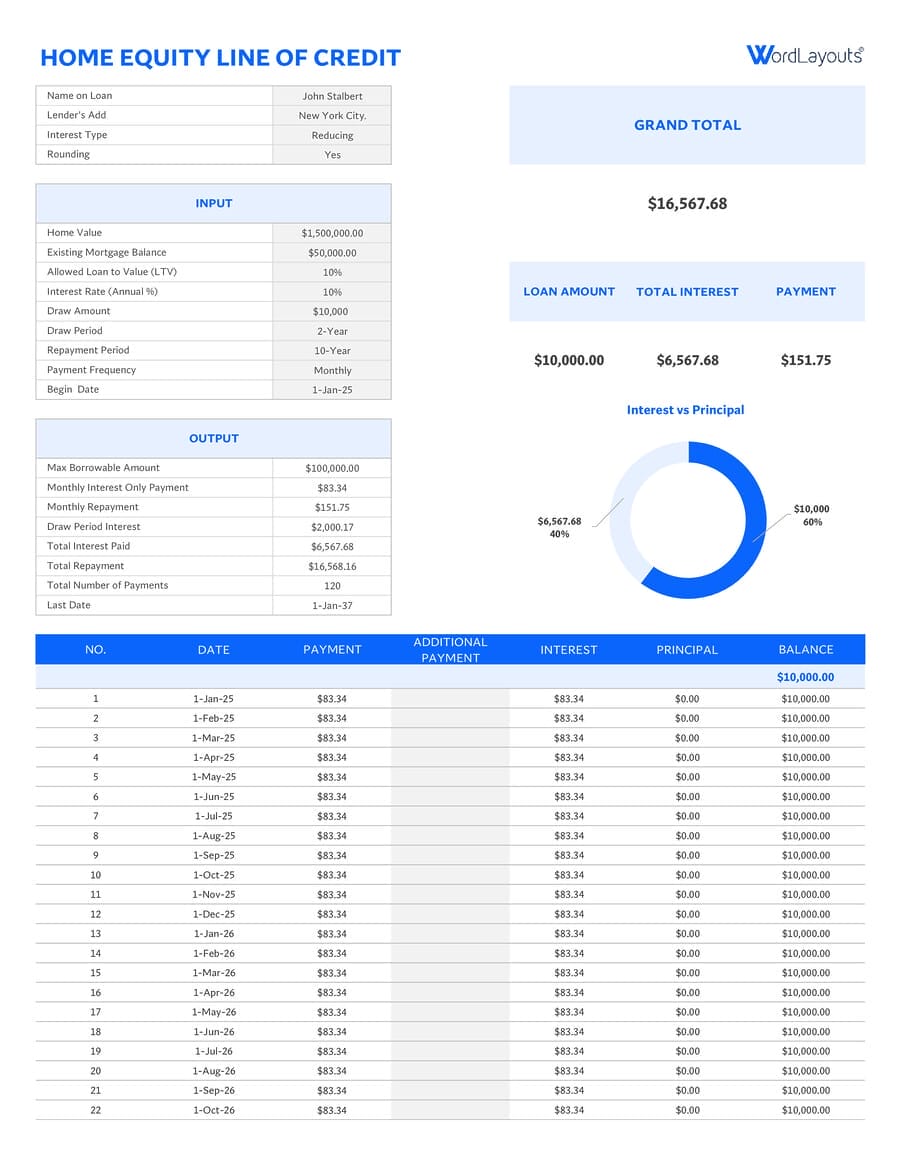
A Home Line Of Equity Calculator estimates how much borrowing capacity you have against your home's equity. You plug in your home's estimated value, your current mortgage balance, and sometimes your lender's maximum loan-to-value ratio. The tool spits out a number that represents roughly how much you could pull out as a HELOC or home equity loan. The math behind it is straightforward enough. Take your home's current market value, subtract what you owe on the mortgage, and apply the lender's maximum allowable combined loan-to-value ratio. Most conventional lenders cap total borrowing at 80 to 90 percent of your home's value, though some go higher depending on your credit score. The calculator then shows the difference between your current loan balance and that capped amount. Here's the thing most people miss. Those calculators are rough estimates at best. They don't account for your debt-to-income ratio, your credit score, the specific terms of your existing mortgage, or whether your lender has proprietary overlays that tighten their guidelines beyond standard requirements. I ran into this exactly during a refinancing situation where the online calculator said I could pull out about $62,000 in equity. The actual approval came back at $31,400. The gap came from three sources: my lender required a lower CLTV ratio for second-lien positions, my credit score was 721 instead of the 740+ they advertise for best terms, and the appraised value came in $18,000 below what I'd estimated. None of that showed up in any calculator I found.
Using a Home Line Of Equity Calculator Correctly
When you actually work through one, start with a realistic home value. Don't use Zillow's estimate or your listing price. Pull a recent comparative market analysis from a local agent or run a formal appraisal if you're serious about the numbers. The calculator output is only as good as the input, and home values are way more volatile than people assume. Next, confirm your exact payoff balance on your primary mortgage. Monthly statements show remaining principal, but there are often escrow shortfalls, missed payments that got capitalized, or late fees stacked into that balance. Call your servicer and get the payoff quote for a specific date. This usually takes ten minutes on the phone and saves you from being off by a couple thousand dollars in the estimate. Then factor in your lender's CLTV limits. Most banks publish these publicly now. Chase, Wells Fargo, and Bank of America all list their maximum combined LTV ratios on their HELOC pages. Subtract your existing mortgage's LTV from the maximum, and the remainder is your headroom. Multiply that percentage by your home value and you've got a manual calculation that often beats the automated tools.
The interest rate environment also matters more than calculators show. A 7 percent HELOC rate during a rising rate cycle eats into your usable equity faster than you'd expect because lenders factor in rate-adjustment risk when determining how much they'll extend. I've seen offers drop by 10 to 15 percent simply because the VIX spiked and the lender tightened their internal exposure limits. The calculator never captures that. Key variables to gather before running any calculation: Current estimated home value from a recent appraisal or CMA
Get the Full Details
Precise outstanding mortgage principal balance including any capitalized costs Your credit score and credit utilization ratio as of today Your total monthly debt obligations including car loans, student loans, and minimum credit card payments
The CLTV and DTI limits from the specific lender you plan to approach Any secondary liens like a previous HELOC or home equity loan that would share the collateral I once worked with someone who had two HELOCs on the same property and no idea they were using the same collateral. The second lender ran a title search and rejected the application because the first HELOC had already consumed 70 percent of the available equity. A calculator wouldn't have caught that unless he'd entered both lien balances correctly. I started making people pull their full credit reports and run a preliminary title search before they even opened a calculator. It adds about 20 minutes to the process but eliminates the most common source of wasted time and disappointment.
The Gaps That Make These Calculators Misleading
Home equity calculators online suffer from several structural limitations. They treat your home as a single asset with a static value, but real estate markets move and your property's worth can shift significantly quarter to quarter. They ignore the fact that your mortgage payments are declining your principal over time, which slowly increases your available equity without any market movement. They also don't account for closing costs, which typically run 1 to 3 percent of the loan amount for a HELOC and can eat into your usable funds immediately. Another blind spot is the difference between a home equity loan and a HELOC. The calculator might give you the same number for both, but a home equity loan gives you a lump sum at a fixed rate while a HELOC gives you a revolving line with a variable rate. In a volatile rate environment, the HELOC option becomes far riskier even though the calculated amount looks identical on paper. I've advised clients to lock a home equity loan instead of taking a HELOC when rates were above 6.5 percent because the payment uncertainty on the line was going to make their total housing costs unmanageable if rates climbed further. The calculator can't tell you that. Property taxes and insurance matter too. Some lenders include those in their debt-to-income calculation for HELOC applications, which means a $4,000 annual tax increase could reduce your available equity by several thousand dollars in borrowing capacity. Your lender might also require mortgage insurance if your CLTV exceeds certain thresholds, and that monthly premium counts against your income qualifications.

The most frustrating limitation is that calculators never show you the actual approval amount you'll receive. Lenders have internal models that weigh your employment history, income stability, and reserve requirements. A self-employed borrower with strong paperwork might get the full calculated amount while someone with identical equity but inconsistent income documentation gets reduced to 50 percent of the estimate. There's no way to know until you submit the application and the underwriter reviews your full financial picture. If you need precision, skip the online calculator and pull a pre-approval or soft quote from a lender first. Most banks will give you a conditional commitment letter that shows exactly how much they're willing to extend based on your actual financial profile. This takes about a week and costs nothing. It's the closest you'll get to a real number before you commit to anything. The best use of a Home Line Of Equity Calculator is as a starting point for understanding your rough positioning. It tells you whether you have equity to work with at all. Beyond that, it's entertainment dressed up as a tool. Run the numbers, understand the assumptions baked into the result, and then do the actual legwork to get a real quote from a lender who will underwrite your specific situation. That's where the real answer lives.