Why Most Home Loan Spreadsheets Are Wrong
I spent three years building financial models for a small mortgage brokerage before realizing the problem wasn't the math—it was the assumptions baked into every free template online. People copy-paste formulas from Excel forums without checking whether the underlying amortization logic actually matches how their bank calculates things. That gap between textbook theory and real lending practice is where a lot of people get burned. The standard approach starts with the annuity formula, which is straightforward enough. Payment equals the loan amount multiplied by the monthly rate, divided by one minus one divided by one plus the monthly rate raised to the power of total payments. Excel has this built into the PMT function, but PMT returns a negative number by convention because it represents cash outflow. You have to manually flip the sign or add a negative to the loan amount, which seems trivial until you're building a schedule and suddenly every row shows negative values everywhere and you can't figure out why your SUM formulas are broken.
Home Loan Calculator Xls
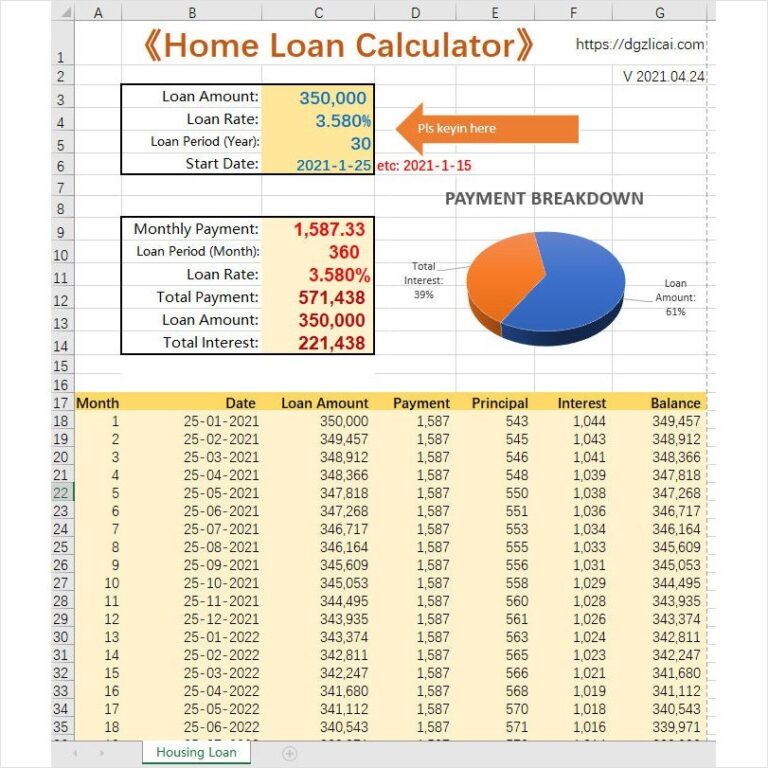
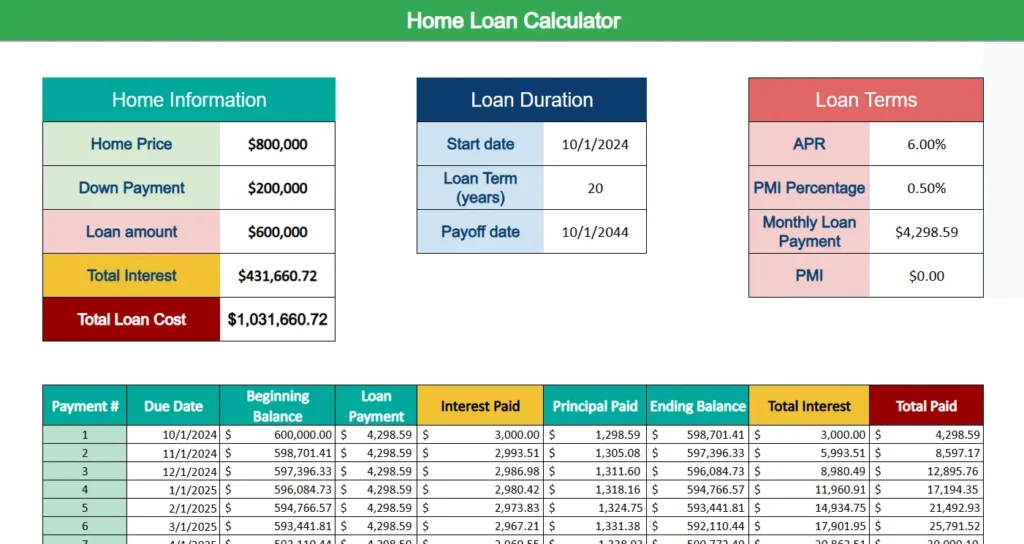
Here's what a proper spreadsheet should actually track. You need columns for period number, beginning balance, payment amount, principal portion, interest portion, and ending balance. The interest portion for any given period is simply the beginning balance multiplied by the monthly rate. The principal portion is the payment minus that interest amount. The ending balance becomes the beginning balance for the next period. Repeat for the life of the loan. The trick that nobody explains in tutorials is how to handle early payments correctly. When you throw an extra dollar at the principal, it doesn't just reduce the balance—it changes every single payment calculation going forward because the interest component shrinks each month based on the new lower balance. Most cheap calculators just subtract the extra payment from the current balance and keep the payment amount the same, which is technically correct for a standard amortization but misses the compounding effect that actually saves you money. A well-built Home Loan Calculator Xls recalculates the entire schedule after each lump sum payment, which takes more rows but gives you the real picture. I ran into a specific problem last year with a client who had a 30-year fixed at 4.25 percent and wanted to see what happened if he made an extra payment every sixth month. The template he found on a finance blog showed a savings of about twelve thousand dollars. I rebuilt the schedule from scratch, properly adjusting the amortization after each extra payment, and the real savings came out to twenty-one thousand. The difference wasn't in the payment formula—it was in how the template handled the recalculation of future interest charges. Once you cut the principal early, the interest stops compounding on that money, and a sloppy spreadsheet just doesn't track that chain reaction across sixty more periods.
What to Look For in a Working Template
A functional Home Loan Calculator Xls needs to handle at least three things correctly: variable extra payments, accurate day-count conventions, and the ability to show payoff date shifts. The first is the most commonly botched. Extra payments should reduce principal, not just subtract from a running total. The second matters more than people realize. Some lenders use 360-day years, some use 365. The difference is small on a monthly basis but noticeable over thirty years. The third is the one that makes the spreadsheet actually useful for decision-making. If your calculator can't tell you what month and year you'll be debt-free after throwing an extra payment at the loan, it's just showing you numbers for entertainment. There's also the issue of how the template handles the final payment. A properly built schedule will adjust the last payment downward because the remaining balance rarely lands exactly on zero after a full amortization. Some spreadsheets force a round payment at the end and throw off the total interest calculation. That error might look harmless—maybe it's fifty dollars off over thirty years—but it reveals whether the template was built by someone who actually understands loan amortization or just copied a formula from Stack Overflow.
Get the Full Details
Where These Spreadsheets Fall Short
Let me be clear about what a spreadsheet cannot do for you. It cannot replace a lender's actual disclosure documents. Bank loan estimates include fees, points, and insurance escrows that a simple payment calculator ignores entirely. If you're trying to determine your total monthly housing cost, a Home Loan Calculator Xls showing just principal and interest is missing roughly a third of what you actually pay each month in most cases. Property taxes, homeowners insurance, PMI—if your down payment is under twenty percent, that last one alone can add several hundred dollars a month to your obligation. Another hard limitation: these templates don't account for variable-rate mortgages with caps and floors the way real loan agreements do. An ARM calculator built in Excel requires you to manually input every rate adjustment date and new rate, and even then you're responsible for verifying the index, margin, and periodic cap structure against your actual note. Getting that wrong produces a schedule that looks clean but is fundamentally misleading. If you have an adjustable rate, you're better off using your lender's official calculator or a dedicated mortgage platform that pulls from the actual contract terms rather than a static spreadsheet. Prepayment penalties are another blind spot. Some loans charge a fee if you pay off too much principal in the first few years. A standard amortization schedule won't flag that. You need to read the good faith estimate your lender provides and manually note any penalty windows in the spreadsheet if you plan to use it for prepayment planning.
Building Your Own Is Faster Than Searching
When I can't find a template that handles a specific edge case, I build a fresh one rather than trying to fix someone else's broken logic. It usually takes about twenty minutes. The core structure is minimal. Column A is the period number. Column B is the beginning balance, starting with the loan amount in row two. Column C is the payment, locked with a dollar-sign reference to a single rate cell so you can change the interest rate once and have the whole schedule update. Column D calculates interest as the beginning balance times the monthly rate. Column E is principal, which is the payment minus the interest column. Column F is the ending balance, which is the beginning balance minus the principal. Drag it down. That's the engine. From there you add sections for extra payments, which create separate blocks where you manually adjust the beginning balance for affected periods. You add a summary area at the top that pulls total interest paid and the actual payoff date from the schedule below. The payoff date should use a MATCH or LOOKUP function that finds the first row where the ending balance drops to zero or below, rather than assuming it's always exactly thirty-sixty periods for a thirty-year loan. Variable prepayments change that timeline, and your calculator should reflect it. I keep a personal copy of a clean version that I've used and refined across dozens of client situations. It handles standard fixed-rate loans, allows multiple extra payment entries scattered throughout the schedule, shows the adjusted payoff date automatically, and flags when the remaining balance hits zero before the scheduled end. If you want something that actually works without requiring a finance degree to decode, you can find a working version at Mortgage Calculator. It's not the most feature-rich tool out there, but it's honest about what it calculates and doesn't pretend to include tax or insurance estimates it clearly doesn't track.
The Bottom Line
A decent Home Loan Calculator Xls is a useful planning tool, not a substitute for professional advice or actual loan documents. The formulas are simple. The implementations are frequently wrong. The value isn't in the spreadsheet itself—it's in understanding what the numbers represent, knowing where the gaps are, and using the tool to ask better questions when you sit down with a lender. Most people who build or buy these spreadsheets stop at the monthly payment number and call it done. The useful ones go further and check whether the total interest, payoff date, and prepayment impact all add up to something realistic before trusting the output.