The actual work of comparing home loans
Most people open a bank website, look at the interest rate, and assume they have enough information to make a decision. They don't. The rate is only one component, and usually not the most important one once you factor in the full cost over the life of the loan. I've sat across from borrowers who locked into what looked like a competitive rate, only to discover three years later that their monthly payment was $200 higher than expected because the loan had an adjustable rate that hadn't been properly disclosed in the marketing materials.A proper Home Loan Comparison requires looking at at least six distinct variables before you commit to anything. The nominal interest rate, the annual percentage rate, the loan term, the type of rate (fixed versus adjustable), the closing costs and fees, and the prepayment penalties if they exist. You need all of those numbers before any spreadsheet gives you a meaningful answer.
How I actually run a Home Loan Comparison
I keep a running comparison sheet in Google Sheets. Not Excel, because I need to pull it up on my phone when I'm at a closing appointment. The sheet has columns for the loan amount, interest rate, APR, monthly payment, total interest paid over the life of the loan, closing costs, and any additional fees like mortgage insurance or points. I add the APR column specifically because that number captures the true cost better than the rate alone. It includes the interest, the points, and most lender fees rolled into a single percentage.One thing most people miss is that the APR calculation assumes you keep the loan for the full term. If you plan to sell or refinance within five years, the APR becomes less useful as a comparison tool. In that scenario, I shift focus to the total cost over the holding period instead. I calculate the sum of all payments made during those five years plus the closing costs, then divide by the remaining balance to see the real effective cost. It takes about ten minutes per loan option once your template is set up.
The edge case that taught me to double-check everything
I had a borrower last year who was comparing three loans from different lenders. Two of the offers looked nearly identical on paper. Same rate, similar closing costs, same term. I ran the numbers and found a discrepancy in how one lender was treating their discount points. They had listed a 0.5-point fee in the closing cost breakdown but hadn't included it in the APR calculation. The other two lenders had rolled their points into the APR. This meant the apparent APR was actually higher than it seemed, and the real cost difference between the loans was about $1,800 over the life of the loan. My borrower picked the one with the lower true APR after the adjustment, and the difference showed up in the first year's interest payment alone.This happened because the Truth in Lending Act requires APR disclosure, but the timing and method of when certain fees get included can vary between lenders. Always verify that the fee lineup in the Loan Estimate matches what shows up in the APR calculation. If they don't align, ask the lender to explain the discrepancy before you sign anything.
Get the Full Details
What the comparison process actually reveals
When you properly compare loans side by side, a few patterns emerge that aren't obvious from just looking at rates. Lenders that advertise the lowest rate often compensate with higher fees or a worse APR. It's not a conspiracy. It's how their pricing models work. Some lenders compete on rate to get your attention, then make their margin back through origination fees and tighter terms. Others price their rate slightly higher but keep the fees low. Neither approach is inherently wrong. One might be better for you depending on how long you plan to hold the loan.I also recommend looking at the lock period. A rate lock that expires in thirty days but closes in forty-five days means you're exposed to market movement. Most lenders will charge a fee to extend the lock, typically 0.125 to 0.25 percent of the loan amount. That's another cost that should factor into your comparison. If you're working with a slower closing timeline, a slightly higher rate with a longer lock period might actually save you money compared to a low rate with a short lock.
Common mistakes that undermine the whole exercise
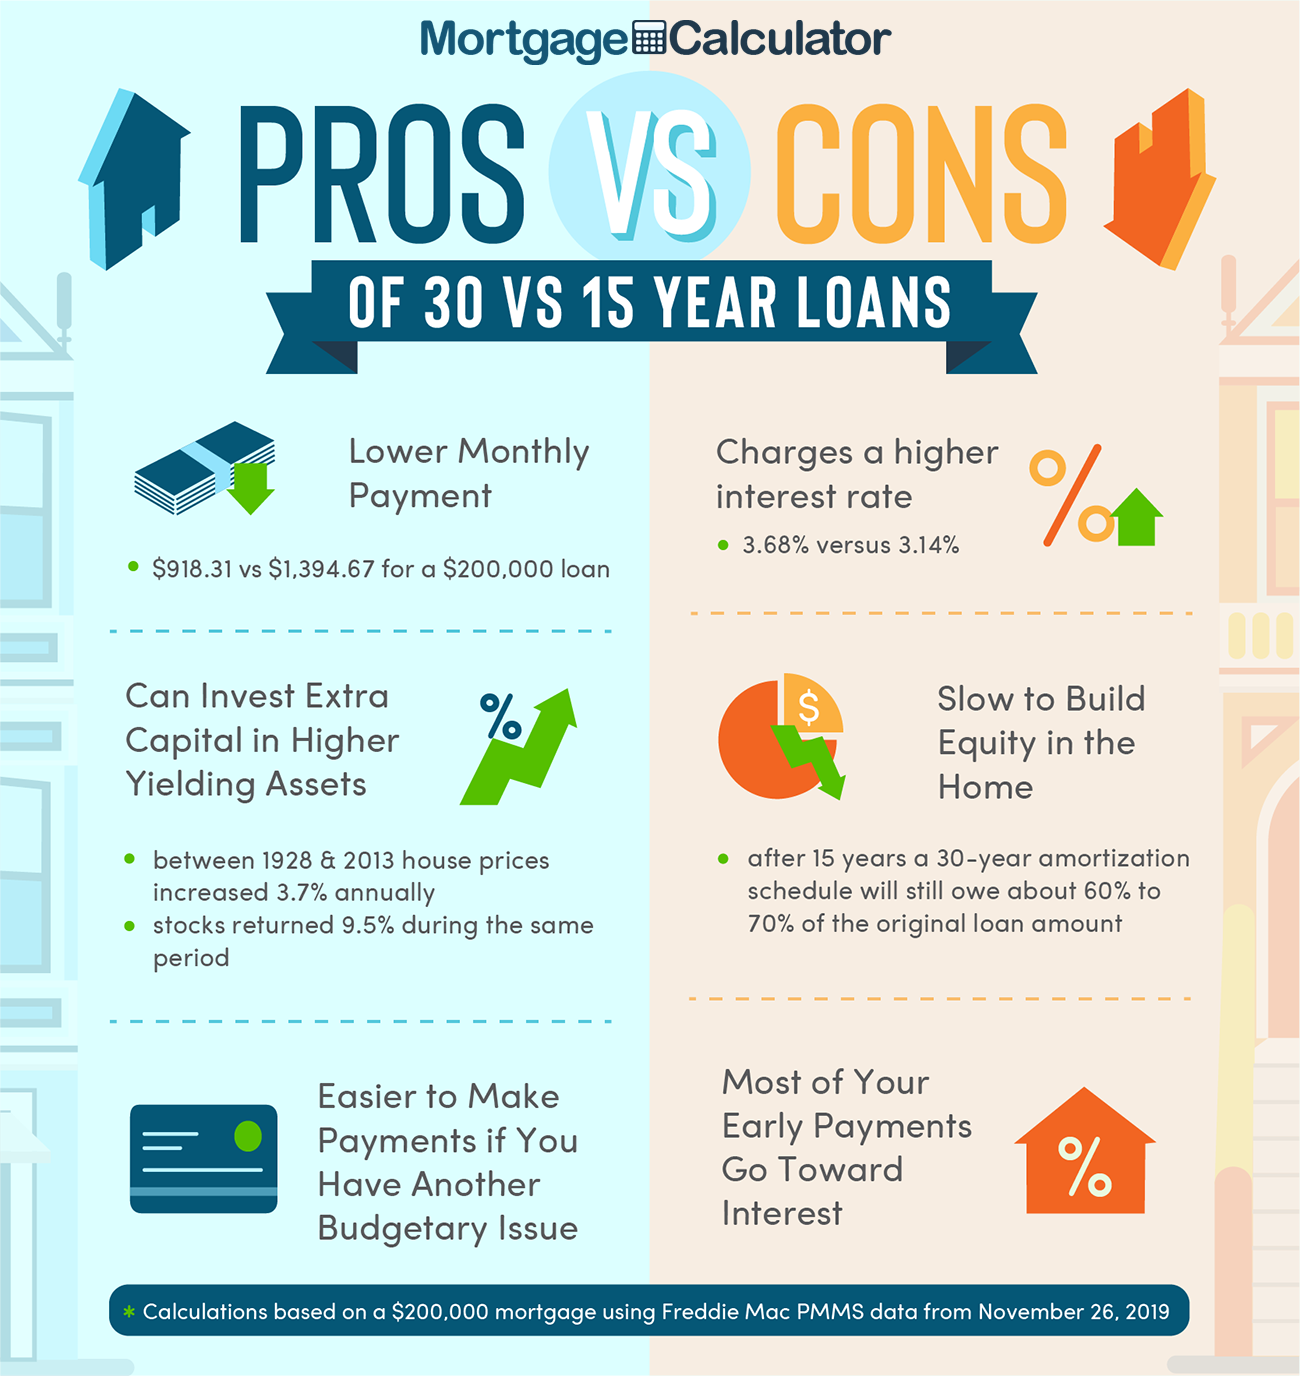
The biggest mistake I see is comparing quotes from different lenders without standardizing the loan parameters. If Lender A is quoting you a 30-year fixed at 6.5 percent and Lender B is quoting a 15-year fixed at 5.8 percent, you're not making an apples-to-apples comparison. The monthly payment will look very different, and the total interest paid will be vastly different, but that doesn't mean one loan is better than the other. You need to compare identical loan products before drawing conclusions.Another common error is ignoring the impact of mortgage insurance. If you're putting down less than 20 percent, you'll likely pay PMI or MIP on top of your payment. Some lenders bundle this into the monthly payment and others roll it into the loan amount. The effect on your total cost is the same, but it changes how the numbers appear in a side-by-side view. Always add the mortgage insurance cost to your comparison sheet as a separate line item so you can see the full picture.
What the data doesn't tell you
A Home Loan Comparison spreadsheet will give you precise numbers, but it won't capture service quality, processing speed, or how responsive the lender is when problems come up. I've seen loans close two weeks early because the underwriter was unusually thorough, and I've seen loans stall for a month because a document request went unanswered. The rate difference between two lenders might be 0.25 percent, which translates to roughly $150 per month on a $400,000 loan. But if one lender delivers a smoother process and the other creates avoidable delays, the monetary comparison becomes less relevant to your actual experience.That said, don't let service quality excuse a bad rate. A 0.5 percent difference on a $400,000 loan over 30 years is about $40,000 in total interest. Worth investigating, even if the lender's communication leaves something to be desired.

Where the comparison method falls apart
The comparison process assumes you have complete and accurate Loan Estimates from each lender. In practice, this isn't always true. Some lenders provide estimates quickly but with incomplete fee breakdowns. Others take longer but deliver more detailed disclosures. You can't force a comparison if one of the inputs is unreliable. I've had to abandon a comparison entirely when a lender refused to disclose their administrative fees until after the appraisal was ordered. At that point, I recommended the borrower pick a different lender rather than guess at hidden costs.Additionally, the comparison method struggles with adjustable-rate mortgages where the adjustment schedule is complex. An ARM with a 5/1 structure behaves very differently depending on how many times the rate can adjust and what the caps are. A simple spreadsheet row for "monthly payment" becomes misleading because the payment will change multiple times. In those cases, I build out a year-by-year projection instead of relying on a single payment figure. It adds time to the analysis but produces a far more accurate result.