Building a Working Home Loan Excel Sheet
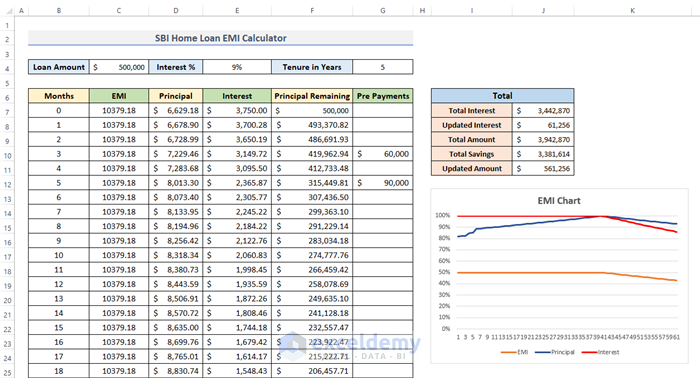
A home loan Excel sheet is really just a structured table that tracks principal, interest, and repayment over the life of a mortgage. Most people who build one end up with something that looks fine on the surface but breaks quietly when they try to compare two different loan offers side by side. I spent a couple of years reviewing these spreadsheets for clients before I started building my own from scratch. The core of a proper spreadsheet comes down to three things: an amortization schedule, a summary dashboard, and a comparison tool. Build them in that order because it forces you to think through what actually matters instead of getting distracted by charts. The amortization table is where most people make mistakes. They put the formula in the first data row and drag it down. That works until they need to sort, filter, or import data, and then everything collapses. I learned that the hard way when a client imported bank statement data that had a blank row in the middle of the schedule. Every cell below that gap became a #REF error and took me forty minutes to fix. The workaround was simple: convert the range to an Excel Table first using Ctrl+T before entering any formulas. Tables handle gaps gracefully and auto-extend formulas when new rows are added.
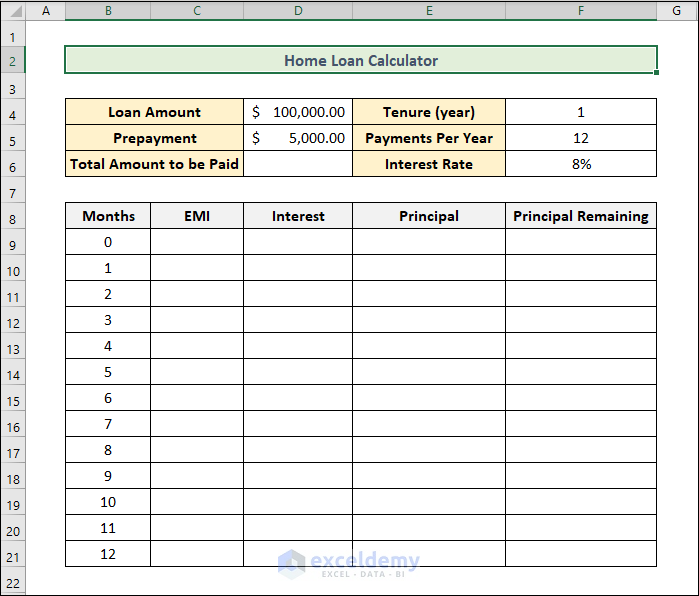
For the monthly payment calculation, use the PMT function. The syntax is =PMT(rate, nper, pv, [fv], [type]). Rate is your monthly interest rate divided by 12. Nper is the total number of payments. PV is the present value or the loan amount entered as a positive number. Enter these as references to cells rather than hardcoding values. I keep the loan amount, annual rate, and tenure in a dedicated settings area at the top so you only change one place when you update the inputs. The breakdown columns you need are payment number, beginning balance, payment amount, principal portion, interest portion, and ending balance. The principal portion equals the total payment minus the interest portion. The interest portion for any given month is the beginning balance multiplied by the monthly rate. Ending balance is beginning balance minus principal paid. Put all of these in a single contiguous block of columns and label each header clearly. You will be looking at this sheet for months and you will not remember what column F represents if you leave it unlabeled.
Setting Up the Summary Section
Below the amortization table, create a small summary block that pulls totals from it. Total interest paid over the life of the loan comes from summing the interest column. Total principal paid comes from summing the principal column. These should match your original loan amount and the total interest figure you calculated separately. If they do not match, you have an error somewhere in the schedule. I use SUMPRODUCT for more advanced summaries. For example, to find total interest paid in the first five years of a 30-year loan, the formula is =SUMPRODUCT((A2:A361
=60)*(C2:C361)) where column A is the payment number and column C is the interest portion. This saves you from creating helper columns and keeps the sheet cleaner. The comparison section is where most people stop and call it done. That is a mistake. A proper home loan Excel Sheet should let you overlay two loan scenarios on the same graph and see the difference in total interest and monthly cash flow. Set up two sets of input cells side by side, run both amortization schedules, and use a line chart to compare ending balances over time. The visual makes it obvious which loan is actually cheaper even when the monthly payment looks similar.
Get the Full Details
Edge Cases That Will Break Your Spreadsheet
ARM loans are the usual culprit. An adjustable rate mortgage changes its interest rate at set intervals, which means the payment formula cannot stay static. I worked with a borrower who had a 5/1 ARM and tried to use a standard PMT-based schedule. The numbers were wrong starting in year six because the rate reset to a higher value. The fix was to break the amortization into segments based on the adjustment periods and calculate each segment separately using the remaining balance as the new present value. Prepayments are another common issue. When a borrower makes extra payments toward principal, the remaining balance drops faster and the interest portion of future payments decreases. A basic home loan Excel Sheet does not account for this automatically. You have to manually adjust the beginning balance for each period where an extra payment occurs, or build in a separate input column for additional principal payments and reference that in your formulas. I added a column for extra payments and modified the principal paid formula to include that column. It made the sheet more realistic and the numbers stayed accurate even when the borrower changed their payment strategy mid-loan. Down payments that are not a round number can cause rounding discrepancies. If your loan amount comes out to $247,832.47 and you round it to $248,000 in the spreadsheet, the amortization schedule will be off by a few dollars per month and accumulate errors over time. Always use the exact loan amount from your closing documents. Small rounding differences compound significantly over 15 to 30 years.
Pitfalls to Avoid
One thing I see repeatedly is people using the FV function incorrectly. Some tutorials tell you to use FV to calculate remaining balance, but that gives you a negative number because Excel treats outgoing payments as negative cash flows. The correct approach is to use the FV function with consistent signs for all cash flows, or simply reference the ending balance column from your amortization schedule. The latter is more transparent and easier to audit. Another frequent problem is mixing annual and monthly rates. Enter your annual interest rate in one cell and divide it by 12 in the formula. Do not enter 0.05 as your monthly rate if it is actually your annual rate. The resulting payment will be wildly incorrect. I keep a clear label next to every input cell specifying whether it is an annual or monthly figure. It takes two seconds to add and saves hours of confusion later. Excel also handles leap years poorly in date-based calculations. If your amortization schedule uses DATE functions to project payment dates across decades, February 29 will appear every four years and throw off any manual date validation. Stick to payment number sequences rather than actual dates unless you specifically need a calendar view. If you do need dates, use the EOMONTH function to generate consistent month-end dates that ignore the irregularities of leap years.
When a Spreadsheet Is Not Enough
A home loan Excel Sheet works well for fixed-rate loans with standard terms. It breaks down when you introduce hybrid products like interest-only periods, balloon payments, or state-specific assistance programs with deferred interest. In those cases, I usually recommend moving to a dedicated mortgage calculator or working with a loan officer who uses professional underwriting software. The spreadsheet will still give you a rough estimate, but the numbers will drift from reality faster than you might expect. I also stop recommending personal spreadsheets when the borrower has multiple income sources, variable bonus structures, or self-employed income that changes year to year. The assumptions required to model that accurately make the spreadsheet too complex to maintain and too error-prone to trust. A certified mortgage professional with access to updated rates and program details will produce more reliable numbers in ten minutes than a custom-built spreadsheet can deliver in an hour. The practical takeaway is that a well-built home loan Excel Sheet can save you two hours of back-and-forth with lenders during the initial comparison phase and help you understand exactly how each dollar of extra payment affects your total interest cost. It will not replace professional advice, but it will make you a better-informed borrower. Start with the basics, validate the numbers against your loan estimate, and expand from there only if you have a specific reason to.