How to Actually Compare Home Loan Interest Rates Without Getting Lost
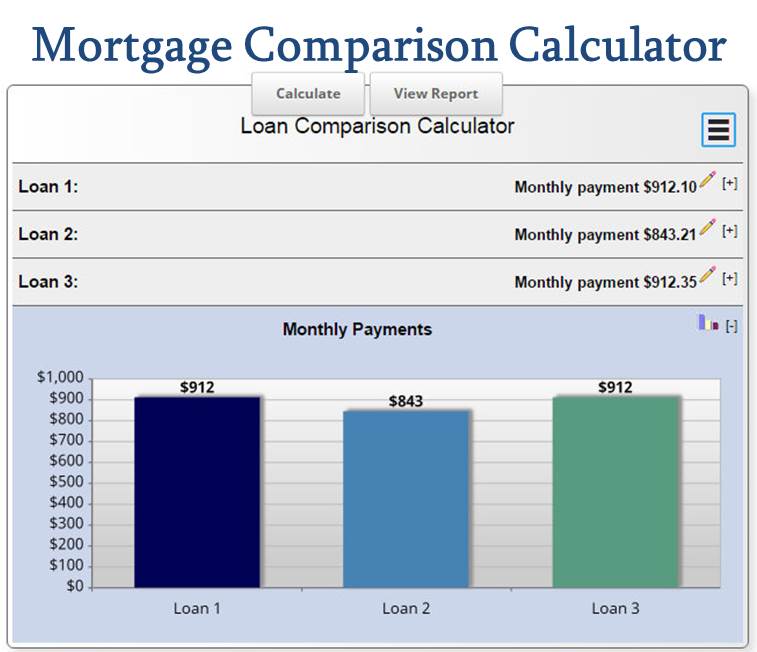
Most people open a Home Loan Interest Rate Comparison Calculator and immediately type in the interest rates they see advertised. That is a mistake. The advertised rate is usually just the starting point, and the final number you pay can be significantly different once you account for fees, discount periods, and the loan structure. I have watched applicants lose thousands by comparing only the headline rate and ignoring how the fees stack up over the life of the loan. Here is what you actually need to do when using this tool. Enter the principal amount first, then the interest rate, then the loan term. But before you click calculate, find the section for upfront fees and ongoing annual fees. Add those in. Then look at the comparison rate if the calculator provides it. The comparison rate is a regulatory requirement in many countries and it folds the interest rate and most fees into a single percentage. It is one of the most useful numbers on the page, but not everyone checks it.
Using a Home Loan Interest Rate Comparison Calculator Correctly
The calculator itself is straightforward, but the input quality determines the output quality. If you guess at the fee amounts, the comparison becomes meaningless. Here is the practical workflow I use: Step one: Gather the loan offer documents from each lender you are considering. Do not rely on the website rate card alone. The actual offer letter will list the establishment fee, the monthly account-keeping fee, and any annual review fee. These vary wildly between lenders and can add hundreds or thousands to your total cost. Step two: Enter the principal, the interest rate, and the term. Make sure the compounding frequency matches the lender's terms. Most home loans compound monthly, but some use daily compounding, which changes the effective cost slightly over time. A 0.02 percent difference in compounding method is not dramatic, but it is real and it matters when you are comparing loans side by side.
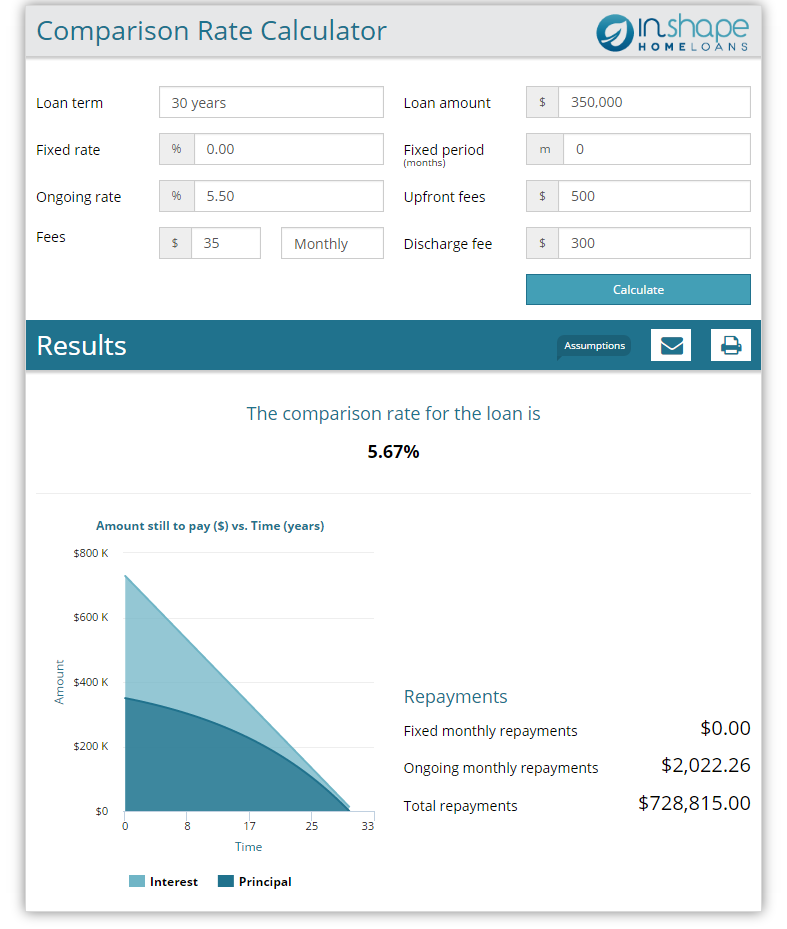
Step three: Add the fees. This is where most people skip ahead. Put in the establishment fee, the ongoing annual fee, and any monthly account-keeping charge. The calculator will show you the total cost of the loan, not just the interest portion. The difference between two loans that look identical on rate alone can be massive once fees are included. Step four: Check the comparison rate. If the calculator generates one, use it as your primary sorting metric rather than the interest rate. The comparison rate already includes most standard fees and gives you a more honest picture of what you will actually pay.
Get the Full Details

Edge Cases That Break the Calculator
I ran into a specific problem last year that took me about two hours to sort out. A client was comparing two loans that had the same interest rate and very similar comparison rates on paper. The calculator showed only a few hundred dollars difference over thirty years. But when I dug into the actual offer documents, I found that one of the loans had a variable rate with a negative amortization clause tied to the LVR. If the property value dropped and the loan-to-value ratio crossed a threshold, the interest rate would jump by half a percent automatically. The calculator does not model this kind of conditional clause because it is not a standard fee or rate input. The only way I caught it was by reading the fine print in the loan contract, not by looking at the calculator output. Another common issue is offset accounts. Many calculators let you enter an offset balance, but they often assume the offset is constant throughout the entire loan term. In reality, your offset balance fluctuates. A more accurate approach is to model a range of offset balances or use the calculator's "extra repayments" feature to simulate how additional payments reduce the principal and therefore the interest charged. Fixed-rate loans also create complications. The calculator will show you the cost of the fixed period, but switching from a fixed rate to a variable rate mid-term usually triggers a break fee. These fees can range from a few hundred dollars to several thousand depending on the lender and the remaining fixed period. If you are comparing a fixed-rate loan against a variable-rate loan, add the estimated break fee to the fixed-rate option or you are not comparing like with like.
What Beginners Miss
The biggest counter-intuitive thing about rate comparison is that the lowest interest rate is often not the cheapest loan. A lender might advertise 5.5 percent with a large establishment fee and a high monthly account-keeping charge, while another lender offers 5.75 percent with no fees. Over ten years, the second loan could cost significantly less. The calculator will show this, but only if you enter the fees correctly. A second thing people overlook is the redraw facility. Some calculators have a field for redraw availability, but most do not factor it into the cost calculation because it is free to access. However, redraw can materially affect your repayment strategy. If a loan allows you to make extra repayments and then redraw them later, it gives you flexibility that a standard loan does not. This flexibility has a real value, especially if your income is variable or you are managing cash flow around a renovation or other large expense. There is also the issue of repayment frequency. Most calculators assume monthly repayments, but paying fortnightly or weekly can reduce the total interest paid over the life of the loan. This happens because more frequent payments reduce the principal balance faster, which reduces the interest calculated each period. A standard monthly payment once a month is mathematically equivalent to twelve payments per year, while fortnightly payments result in twenty-six half-payments, which equals thirteen full monthly payments. That extra payment per year can save thousands over a thirty-year term, depending on the rate and principal.
When the Calculator Fails You
I need to be blunt about the limitations. A Home Loan Interest Rate Comparison Calculator is a blunt instrument. It cannot model every variable in a mortgage product. It will not tell you about lender reliability, customer service quality, or how likely a lender is to approve a variation request later. It will not warn you about hidden clauses in your contract, like the negative amortization issue I described earlier. It also cannot account for future rate changes unless you manually adjust the inputs, and even then, the model is still a guess. If you are dealing with a commercial property loan, a bridge loan, or a construction loan with staged disbursements, a standard residential calculator will not give you useful results. These products have entirely different fee structures and repayment schedules. In those cases, you should either use a specialized commercial mortgage calculator or get a quote from a mortgage broker who understands the product. Another scenario where the calculator falls apart is when you are comparing loans across different currencies or jurisdictions. A calculator designed for Australian dollar loans will not work for a New Zealand dollar loan, and neither will handle UK-based mortgages with different fee structures and regulatory frameworks. You need a calculator built for that specific market.
Practical Tips That Actually Matter
Run multiple scenarios with the calculator. Enter the loan at the advertised rate, then enter it again with a hypothetical rate increase of 0.5 percent and 1 percent. This tells you how much your repayments would rise if the reserve bank hikes rates and your lender passes that through. It is a stress test that most people skip, but it is one of the most useful things you can do before signing anything. Save your calculations. Export or screenshot the results for each loan you compare. Lenders change their rates frequently, sometimes weekly. If you come back to a loan offer three months later, the numbers may have shifted. Having your original comparison lets you see whether the gap between loans has narrowed or widened over time. Do not use the calculator as your only decision tool. It is a starting point, not the final word. After you have a shortlist of two or three loans based on the calculator output, read the product disclosure statements for those specific loans. Look for the clauses the calculator cannot model. That is where the real differences live.
One more thing. If you are between two loans that are very close in total cost according to the calculator, the smaller difference in dollars is often not worth the hassle of switching or the additional paperwork. A few hundred dollars over the life of a loan is usually swallowed by transaction costs, legal fees, and the time you spend managing the process. In those cases, pick the loan that feels simpler to deal with and move on.