How to Actually Use a Home Loan Pay Off Calculator Without Getting Misled
Most people treat a Home Loan Pay Off Calculator as a crystal ball. It isn't. It is a spreadsheet engine that projects what your balance looks like under assumptions you provide. The output is only as clean as the input. I have sat across from borrowers who walked out of a loan officer's office convinced they would be debt-free by a specific date, then discovered their numbers ignored private mortgage insurance, property tax escrow changes, and the fact that their loan had a prepayment penalty clause. Here is how to get useful numbers out of one, where the traps are, and what to do when the calculator gives you a result that feels wrong.
Using a Home Loan Pay Off Calculator Step by Step
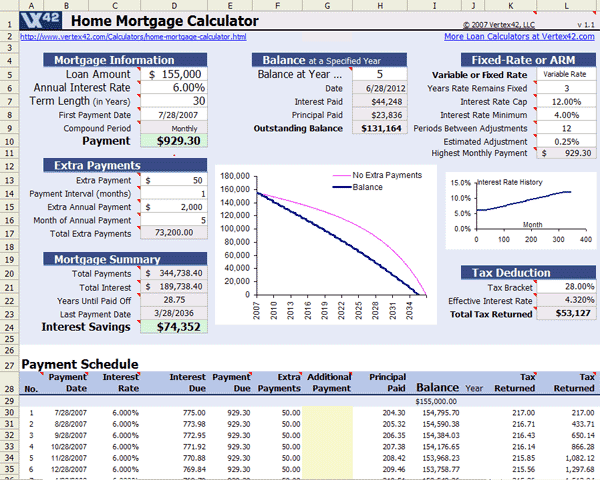
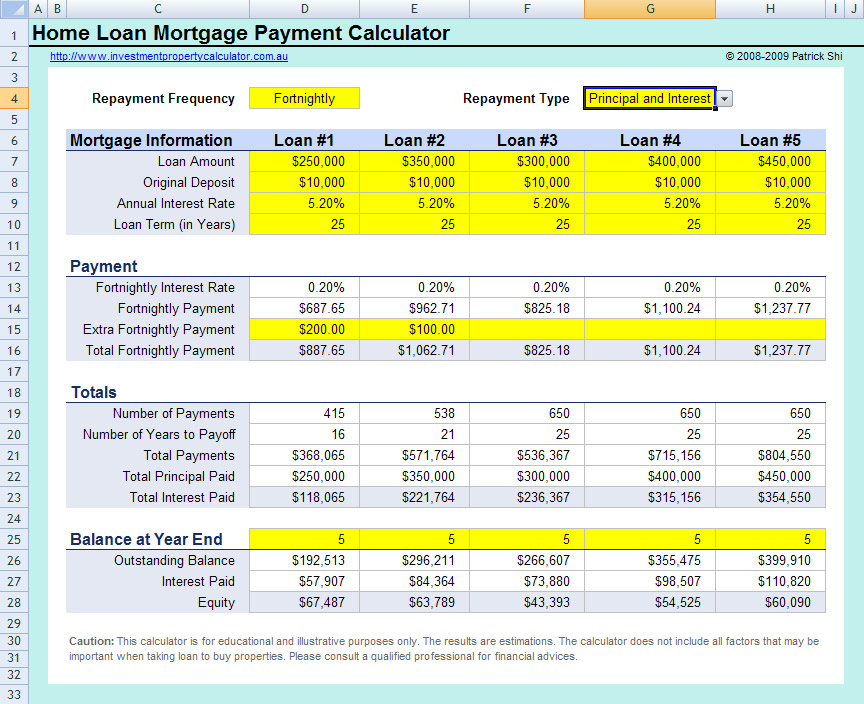
Open a standard calculator. These are free online tools or you can build your own in Excel using the PMT and CUMPRINC functions. You need six inputs at minimum: the original loan amount, the interest rate, the loan term in months, the origination date, the monthly principal-and-interest payment, and whether the loan has any prepayment penalties or cap adjustments if it is an ARM. Enter the origination date first. This matters more than people realize because it determines which year you are in for rate reset windows on adjustable loans and when your escrow shortage or surplus calculations kick in. After that, feed in the current balance, not the original balance. If you have already paid for eighteen months, the amortization schedule has shifted. Plugging the original amount into a calculator that assumes month one will overstate your remaining interest by a noticeable margin. Run the projection. Write down the payoff date the tool gives you. Then check three things before you trust it.
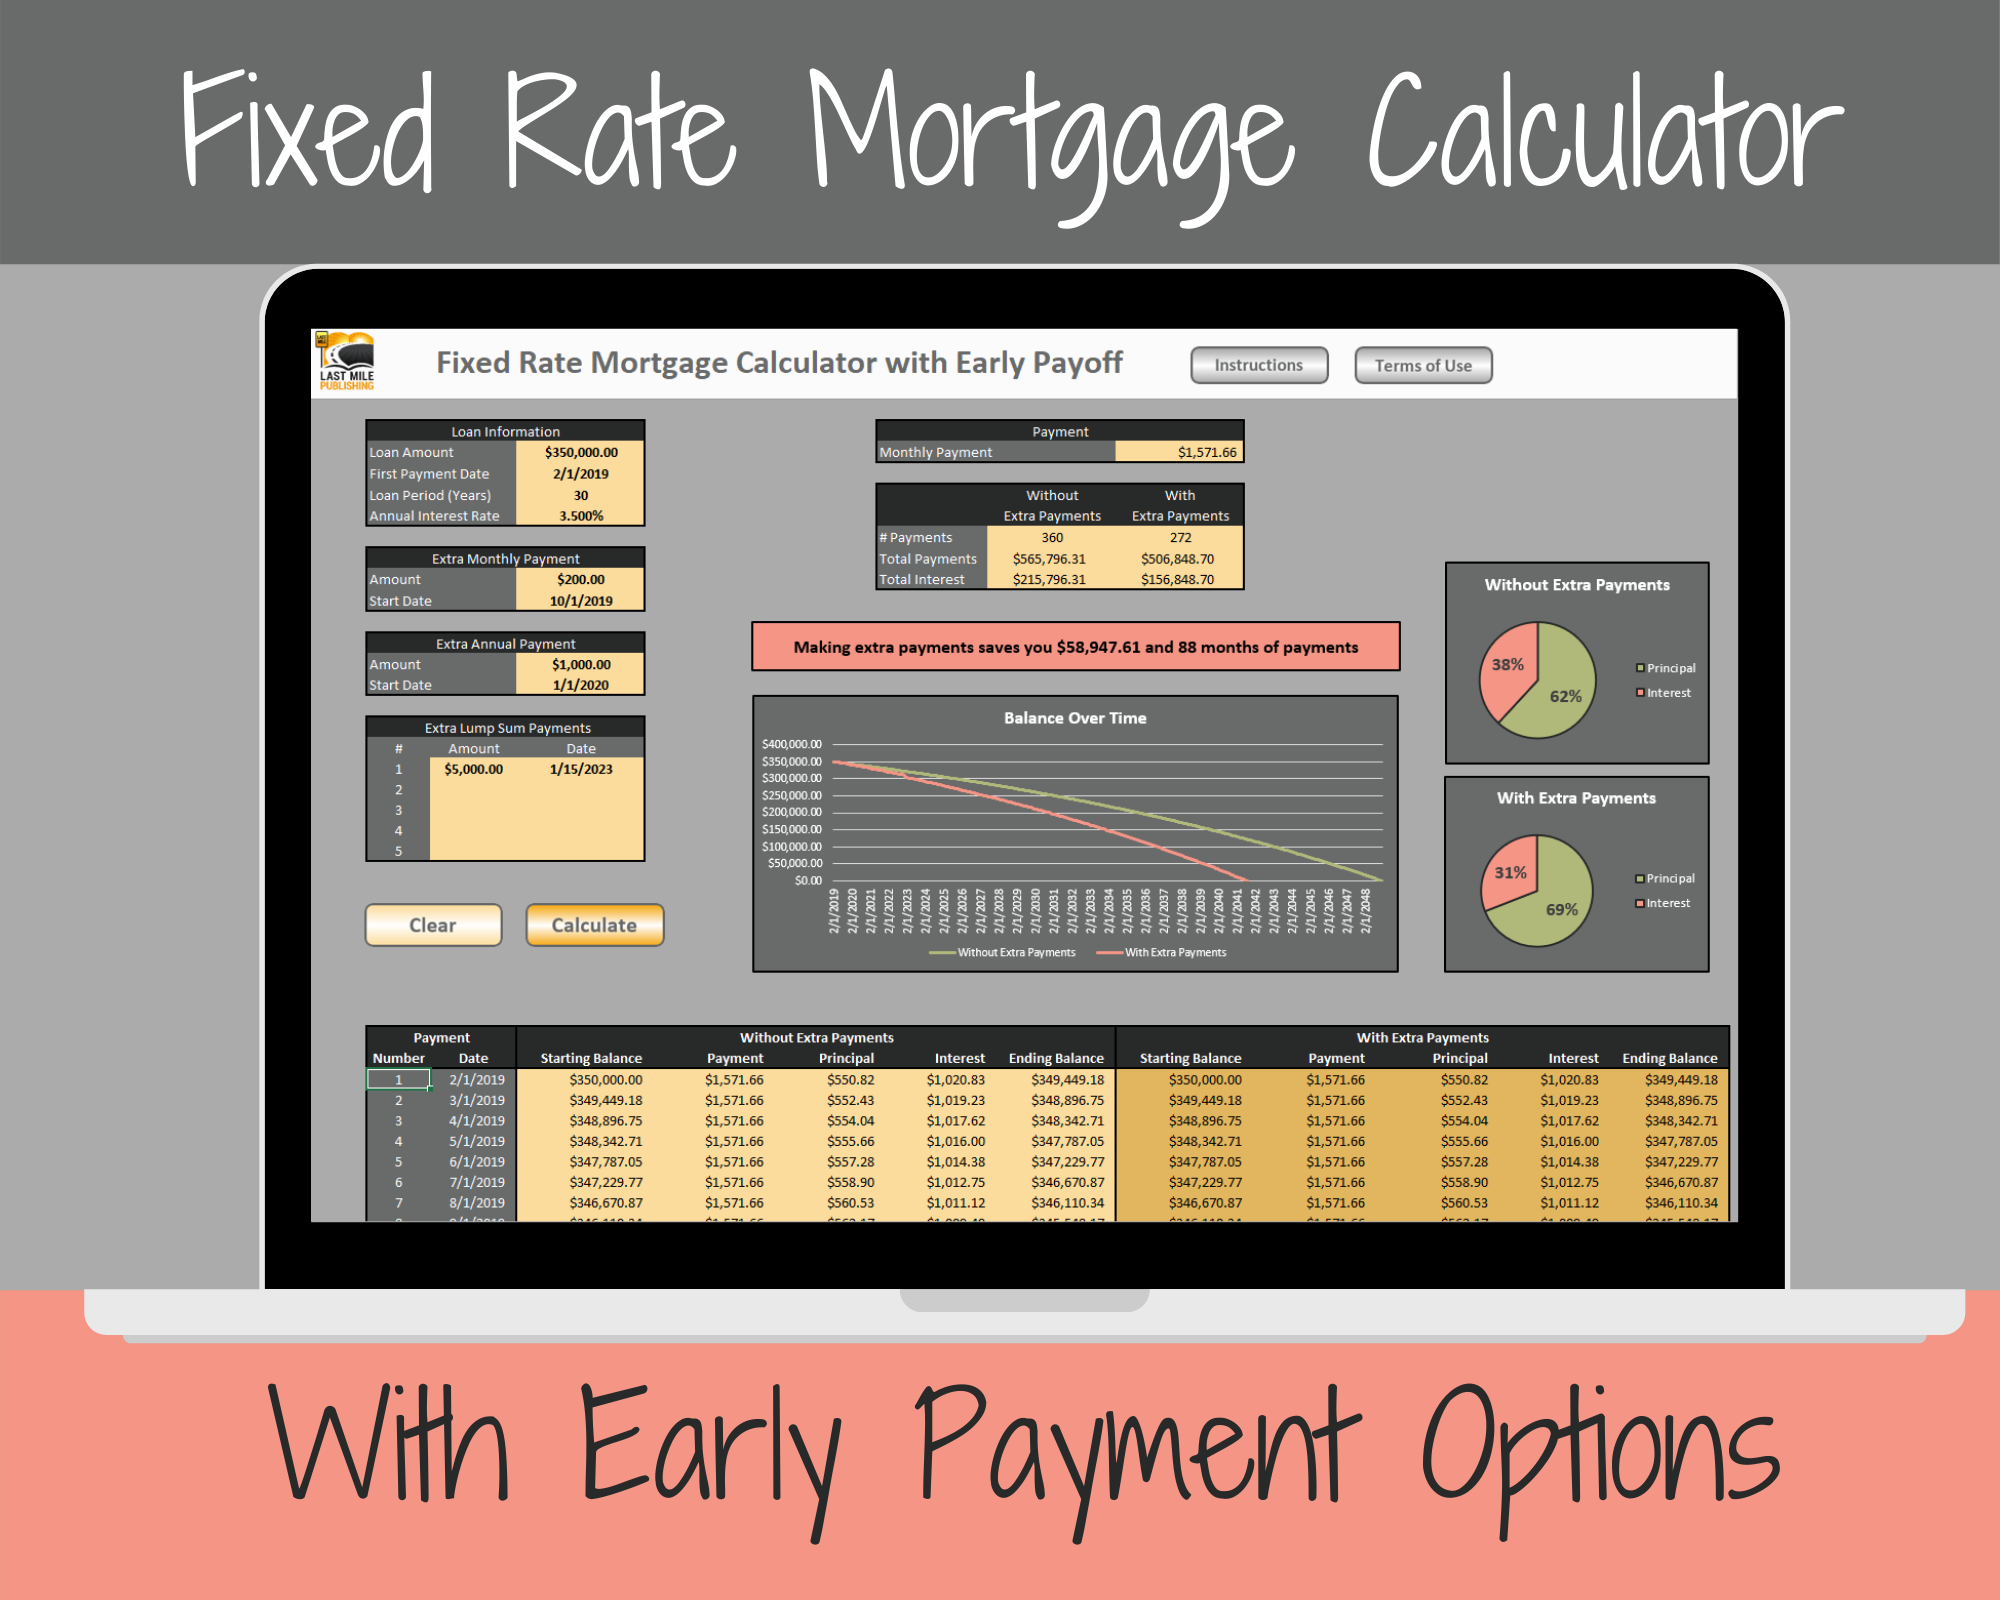
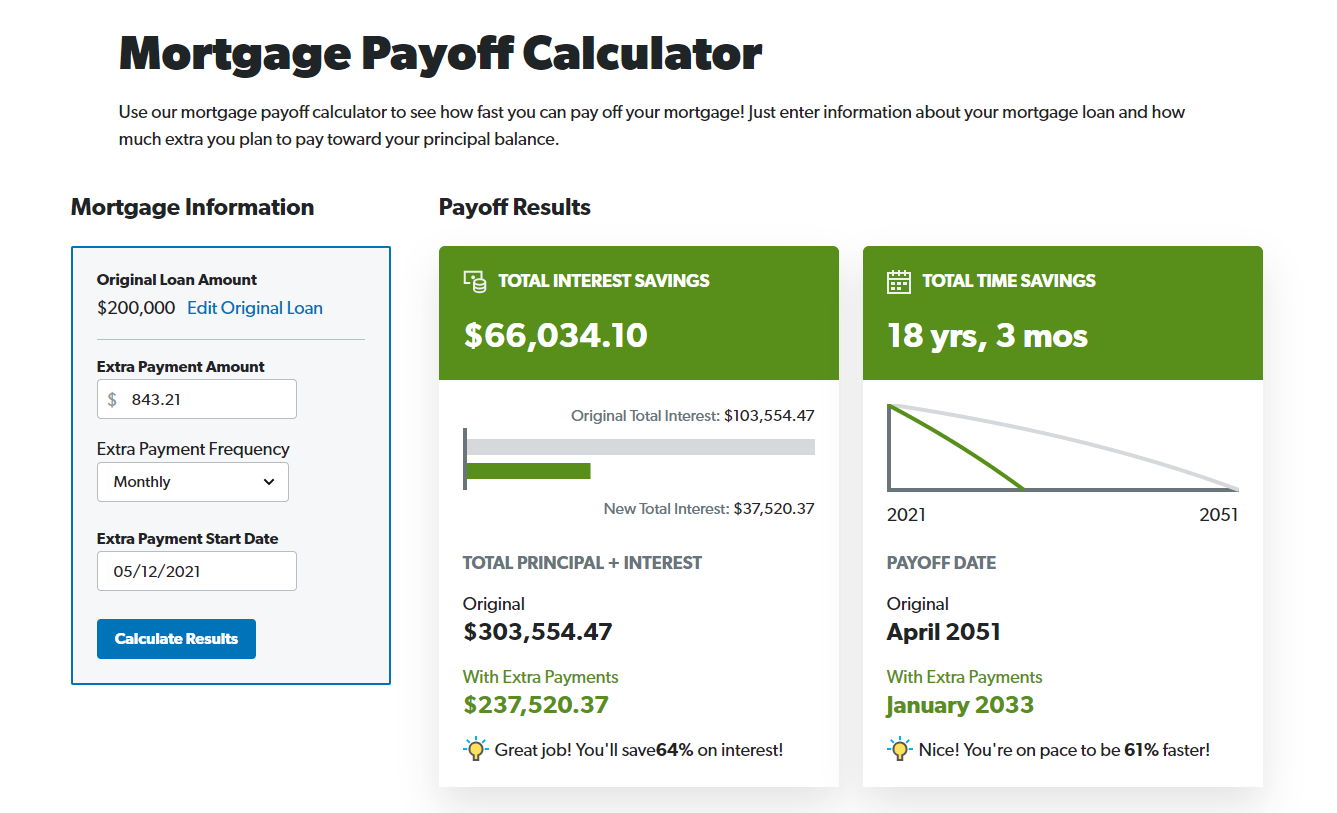
First, verify the payment amount. Some calculators assume your monthly payment covers principal, interest, taxes, and insurance. Others calculate principal and interest only. If your $2,100 monthly payment actually includes $400 for taxes and insurance, feeding that full number into a principal-and-interest-only calculator will make your payoff look years earlier than it will be. I have seen this happen repeatedly. The borrower thinks they are five years from freedom. They are not. Second, confirm whether the calculator applies extra payments correctly. There are two methods: reduction of term and reduction of monthly payment. Most people want term reduction. A few calculators default to the wrong one or present the numbers in a way that obscures which method is active. Check the fine print or the column headers. If the tool does not let you specify, switch to a calculator that does or build your own schedule in a spreadsheet. Third, test a scenario where you accelerate by a fixed amount each month, like an extra $300 going toward principal. Watch how the payoff date shifts. If the shift is negligible, something is off with the interest calculation. On a typical 30-year loan at current rates, an extra $300 a month should cut several years off the term. If the calculator shows only a month or two of savings, the tool is likely compounding incorrectly or treating the extra payment as escrow rather than principal.
Get the Full Details
The Real Mechanics Behind the Output
An amortization schedule works by applying your payment first to accrued interest, then to principal. Early in the loan, the interest portion is large because it is calculated on a large remaining balance. As the balance drops, more of each payment goes to principal. This is basic math, but the nuance people miss is how prepayment behavior interacts with that curve. A single lump-sum payment made in year one has a dramatically different impact than the same lump sum made in year fifteen. In year one, you are reducing the balance that will generate interest for the next twenty-nine years. In year fifteen, you have already paid a substantial portion of the interest, so the same payment saves less total interest over the life of the loan. Calculators that show total interest savings without specifying timing are hiding important information. Always look for the breakdown by year or by payment number. Another thing most online calculators do not handle well is escrow analysis. Lenders require an escrow account for taxes and insurance on most conventional loans. Those payments change. Property taxes increase. Homeowners insurance premiums rise. When your calculator ignores escrow adjustments, your projected payoff date can drift from reality, especially on loans with longer terms where tax assessments have time to compound.
Home Loan Pay Off Calculator: The Edge Case I Still Think About
I worked with a borrower who had a modified government loan with a residual value guarantee and a part-day accrual method. The standard Home Loan Pay Off Calculator online gave a payoff quote that was about $4,200 short. The tool was using a 30/360 day-count convention, which assumes thirty-day months and a thirty-six-day year. The loan was actually on an actual/365 basis, which is common for certain government-backed and some adjustable-rate products. The difference sounds small until you are looking at daily interest accruals over a twelve-month run-off period. The workaround was to pull the loan's note and addendum, identify the day-count method from the disclosure language, and then use a calculator that allowed manual day-count selection or to build a custom schedule in a spreadsheet using the ACT/365 formula. On a $400,000 loan at 6.5 percent, the discrepancy between 30/360 and ACT/365 runs roughly one cent per day per $1,000 of principal. Over a year, that is about $12 in interest variance on that balance. It compounds when you are projecting payoff because the lower accrued interest in the 30/360 model makes the balance appear to drop faster than it actually does. For a precise payoff quote, always request one directly from the servicer rather than relying on a generic calculator.
What These Calculators Miss Completely
They do not model refinance options that might emerge later. They do not account for loan modification outcomes, forbearance periods, or the tax implications of mortgage interest deductions changing under current law. They also cannot tell you whether your loan has a yield-spread premium or broker fee baked into the rate that affects the true cost of borrowing versus the advertised number. If you have an adjustable-rate mortgage, the calculator's static rate projection is almost useless beyond the initial fixed period. ARM wrappers, rate caps, and adjustment floors create situations where the balance trajectory changes dramatically at the first reset. A calculator that holds the rate constant through the entire term will give you a payoff date that is only relevant for the intro period, not for the life of the loan. Some tools let you input adjustment schedules. Use them. If your tool does not, switch tools or model the ARM resets manually in a spreadsheet. There is also the matter of partial payments and skip-pay options. Some lenders allow you to skip one payment per year or make partial payments without applying them to principal immediately. If your loan has these features, the calculator's standard amortization path will not reflect your actual payment behavior. I have seen borrowers plug in a payment amount that included a skip-pay month, then wonder why the projected payoff date did not match their experience.
Practical Ways to Make the Numbers Work for You
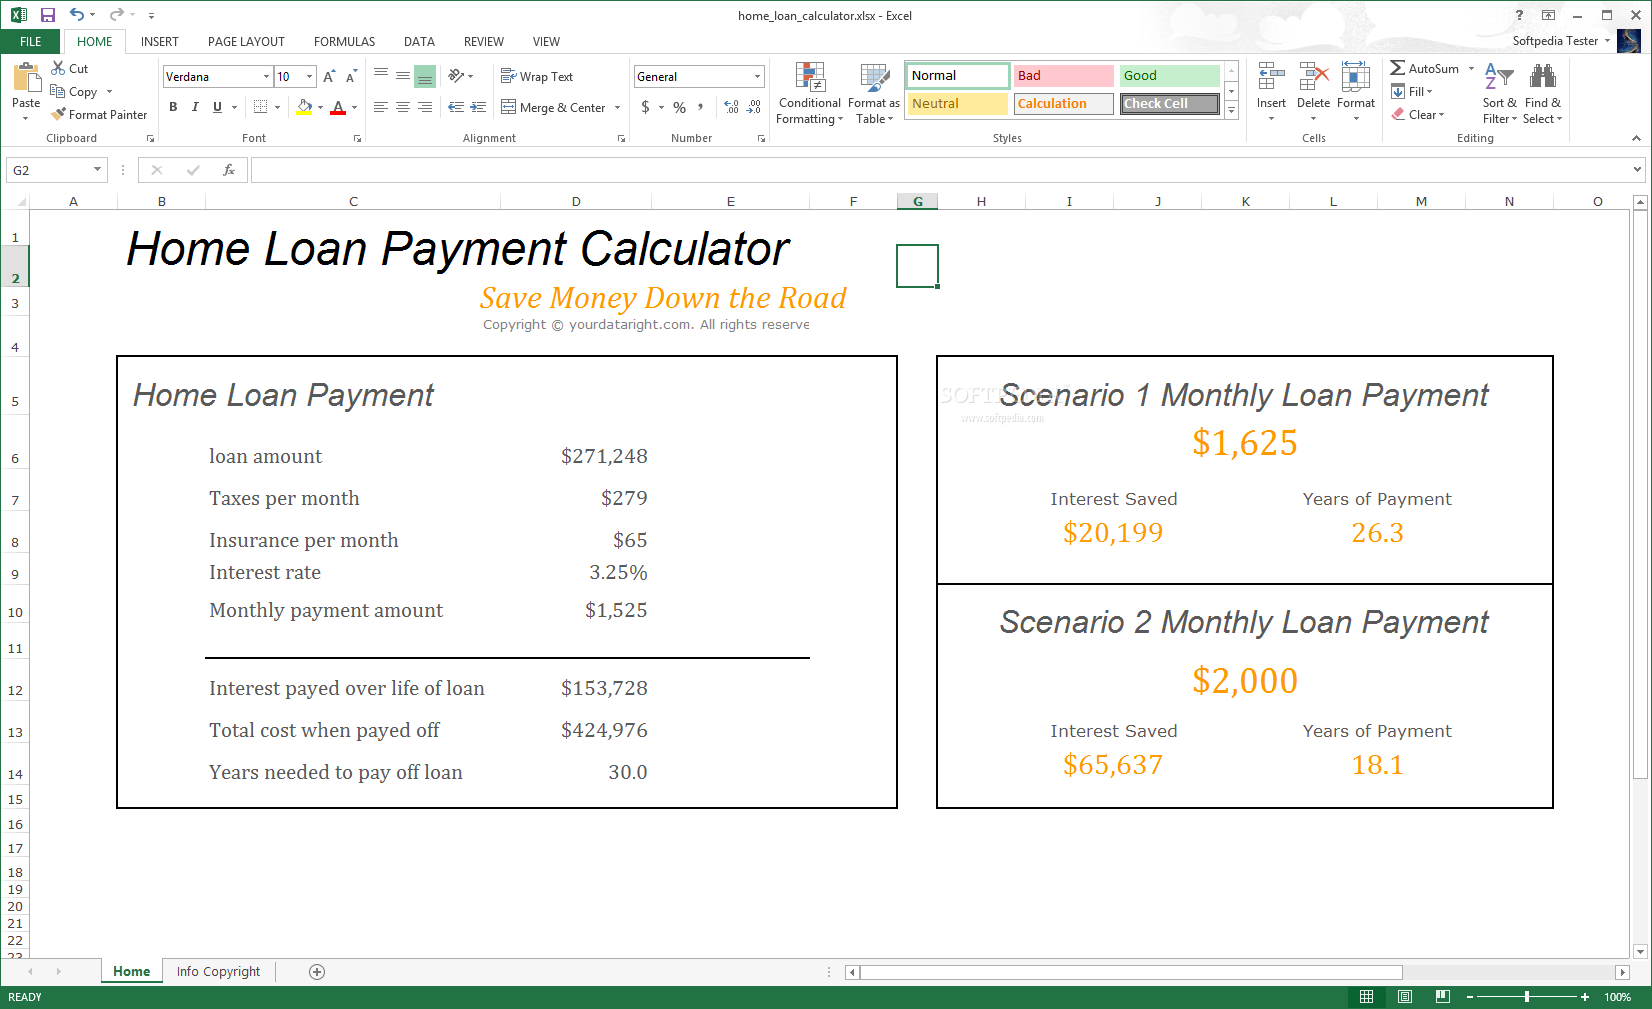
Build a spreadsheet version of your amortization schedule. It takes about twenty minutes and gives you far more control than any web calculator. Use the CUMPRINC function to extract cumulative principal paid between any two payment numbers. Use CUMIPANC to get cumulative interest. When you want to test an acceleration strategy, add a column for extra principal and recalculate the remaining balance row by row. This approach handles edge cases like partial months, varying payment dates, and irregular extra payments without forcing you into a calculator's rigid assumptions. If you want speed over precision, a Home Loan Pay Off Calculator from a reputable lender or mortgage software provider will get you within a reasonable range in two minutes. If you want accuracy for decision-making, invest the time to build or customize the model. The difference between the two approaches is the margin of error, and on a large loan, that margin can equal thousands of dollars. Check your annual mortgage statement. It includes a year-by-year breakdown of principal and interest that most servicers are required to provide. Compare the actual numbers to the calculator's projection after twelve months. If the variance exceeds two percent, something in your assumptions is wrong. Adjust the input and re-run. Repeat annually. Loans shift. Rates reset. Tax assessments change. A calculator you set once and forget becomes less accurate over time, not more.
When to Walk Away From a Calculator
If your loan involves a balloon payment, a shared appreciation mortgage, or a reverse mortgage conversion feature, generic payoff calculators will not serve you. These products have payout formulas that depend on property value changes, age-based factors, or contractual balloon triggers that no standard amortization engine can model. In those cases, request a formal payoff statement from your servicer and use it as the baseline. Treat any online calculator result as an estimate at best, and usually as irrelevant. The same applies if you are considering a short sale or a deed in lieu. A payoff calculator assumes you will pay the full balance. It cannot factor in lender negotiation outcomes, deficiency judgments, or the tax consequences of forgiven debt. Use the calculator to understand your liability, not to predict a resolution path.
Bottom Line
A Home Loan Pay Off Calculator is a projection tool, not a guarantee. It works well when your inputs are accurate and your loan structure is standard. It fails when you ignore day-count methods, escrow variability, ARM adjustments, prepayment penalties, or the difference between P&I-only and P&I+T&I payment assumptions. Verify the calculator's method, cross-check against your actual payment history, and build a custom schedule when the stakes are high. The payoff date you see on screen is a starting point, not the finish line.