How Extra Repayments Actually Work in Practice
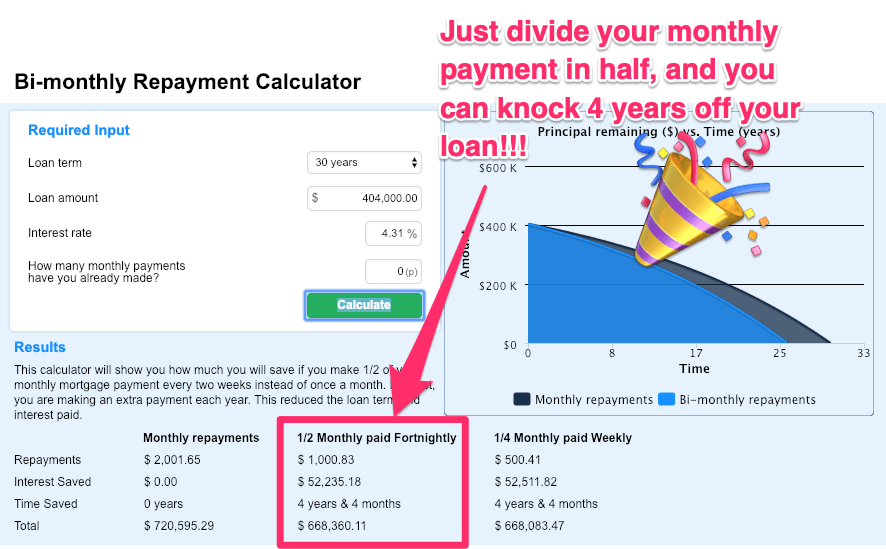
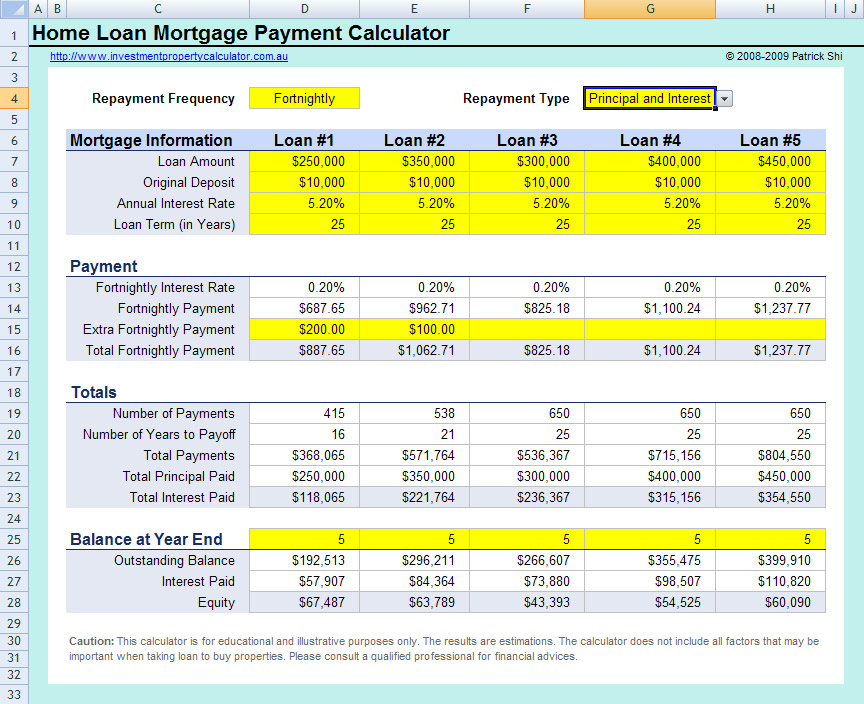
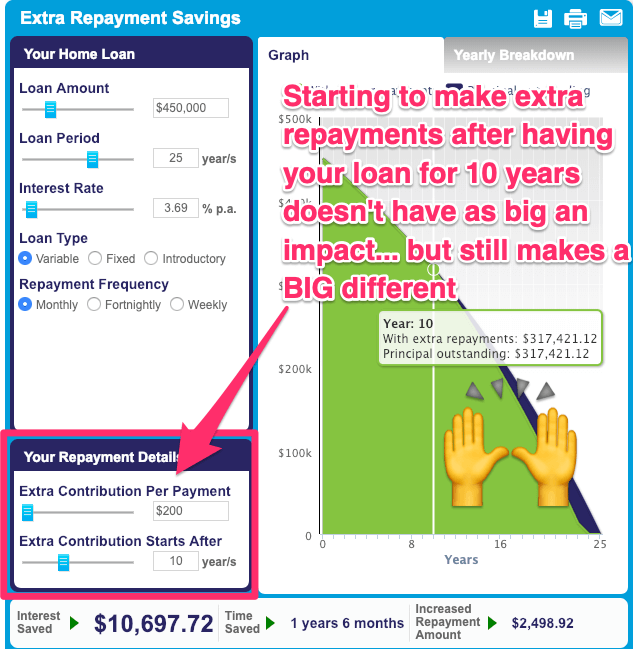
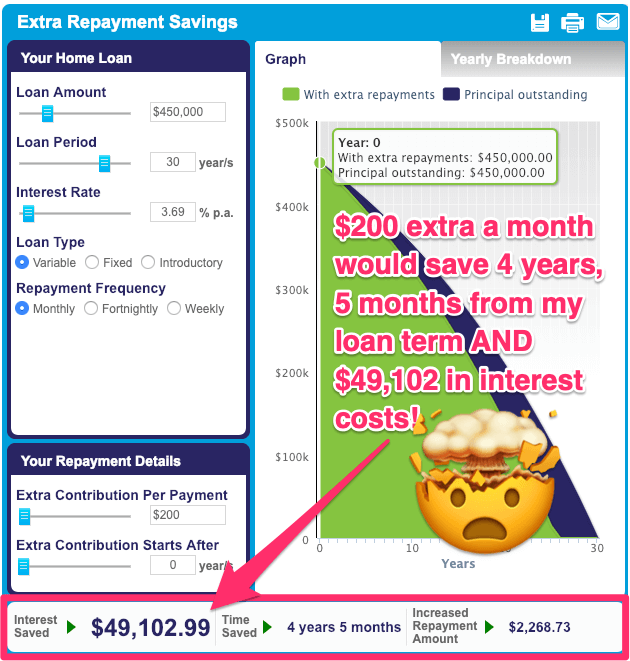
A home loan repayment calculator with extra repayments isn't just a pretty spreadsheet. It's a tool that shows what happens when you throw additional money at your mortgage every month. Most people think it's straightforward — you type in your balance, rate, and extra amount, and boom, you see savings. It's messier than that. The basic flow is simple enough. You enter your current loan balance, interest rate, remaining term, and the extra amount you want to pay each month or year. The calculator then recomputes your amortization schedule. It shows you the new payoff date and total interest saved. That part is standard across every tool on the internet. But here's where most people get tripped up. The calculator assumes your extra payments are applied correctly. In reality, they may not be. I spent months watching clients lose money because their bank applied extra repayments to future scheduled payments instead of reducing principal directly. The interest kept compounding on the full balance while they thought they were making progress.
My workaround was telling every client to request their extra payments go into a redraw account or offset account rather than just paying down the loan directly. With an offset account, your extra funds sit there and reduce the daily interest calculation without technically being a "principal payment." Banks can't misuse that money. It's the single most practical move most borrowers never make. When you run numbers through a proper calculator, make sure it distinguishes between offset and direct principal payments. Some tools lump them together, which gives misleading results. A $500 monthly extra payment into an offset account saves slightly different amounts than $500 going straight to principal, depending on how your bank calculates daily interest. The gap isn't huge but it adds up over ten years.
What Most Calculators Get Wrong
The biggest limitation with free online calculators is that they don't account for your specific loan structure. Variable rates change. Some loans have break fees if you pay off early. Others have monthly or annual contribution caps that restrict how much extra you can throw at the loan without triggering penalties. A generic calculator won't warn you about any of that. I ran into a case last year with a borrower who had a fixed-rate loan with a $10,000 annual extra repayment cap. She was making $800 monthly extras on top of her regular payments. The calculator she used showed her saving nearly $40,000 in interest over five years. The reality was closer to $12,000 because the excess payments got held in suspense and applied inconsistently. She lost confidence in the process and stopped making extras entirely, which ended up costing her more in the long run. Another common pitfall is compound frequency. Some banks compound daily, others monthly, and a few still use quarterly calculations. Your calculator needs to match your bank's method or the projected savings will be off by a few percent. On a $400,000 loan at 5.5% over 25 years, that difference can mean $3,000 to $7,000 in inaccurate projections.
Get the Full Details
There's also the issue of minimum payment requirements. If you start making extra repayments and your bank has a rule about maintaining a certain payment-to-balance ratio, you could accidentally breach your loan covenant. This is rare with modern loans but still happens with older commercial-style residential products. Check your loan contract for any clauses about restructuring or minimum payment amounts before you start. If you're dealing with a complex situation — offset accounts, redraw facilities, fixed and variable components split across multiple loans — the free calculators fall apart. They can't model the interactions between accounts. In those cases, you need either a proper financial planning tool or to ask your lender for a personalized projection. It takes longer but the numbers actually hold up under scrutiny.