Why Most People Build Home Loan Spreadsheets Wrong
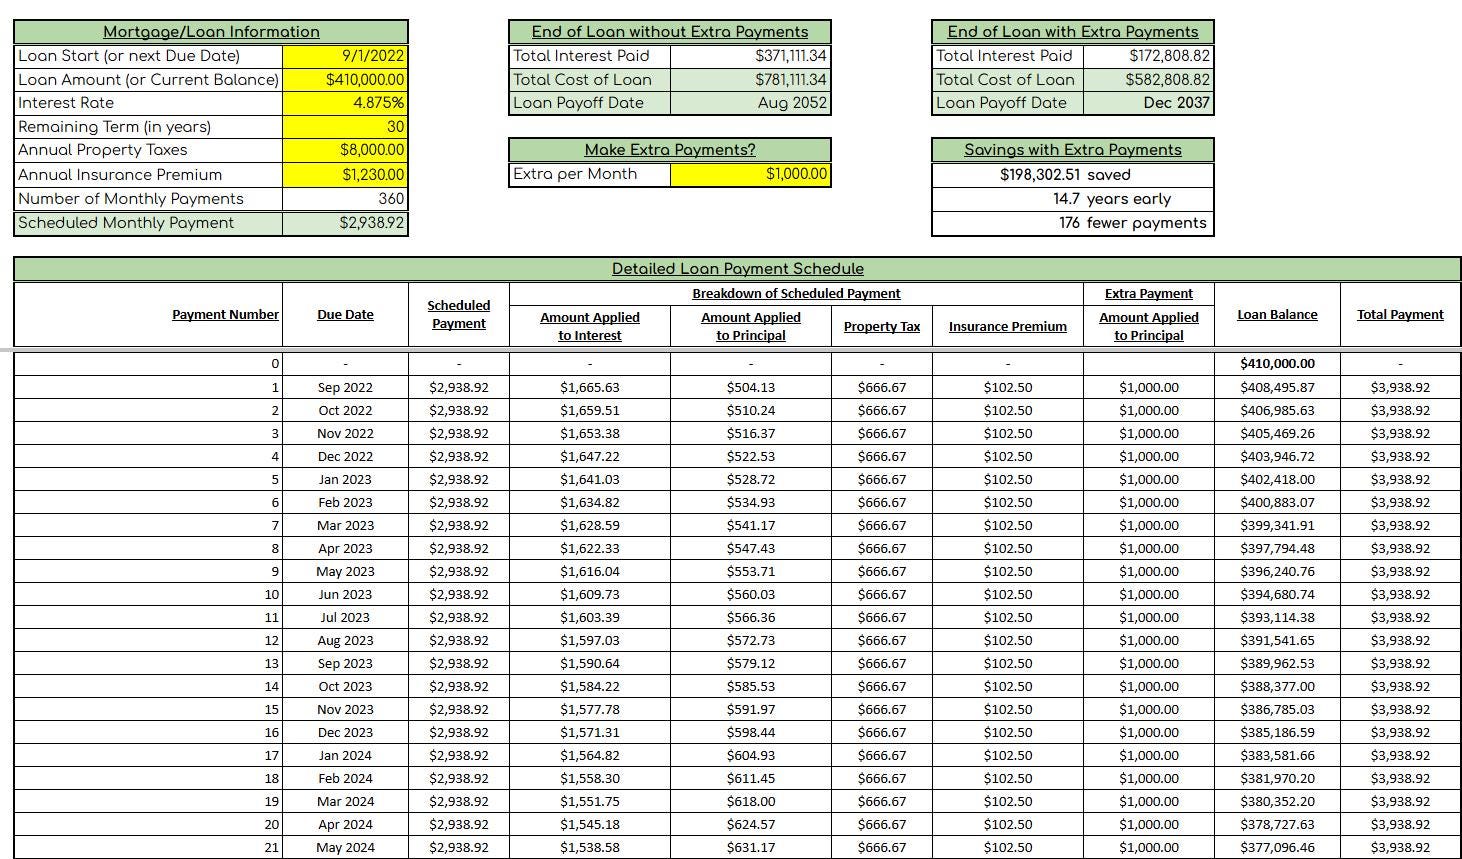
I spent three weeks last year building a custom amortization tracker because the bank's numbers didn't match what my initial spreadsheet showed. Turns out I was using a rounded monthly payment instead of the bank's full decimal precision, which threw off every row by a few cents. Over a 30-year loan that compounded into hundreds of dollars in variance. I rebuilt the whole thing using unrounded calculated values and it took about an hour. This is the kind of thing that bites you if you don't know it. A Home Loan Spreadsheet is a tool that tracks the financial details of a mortgage from origination through payoff. It calculates monthly payments, shows how much goes toward principal versus interest each period, and projects your remaining balance over time. Some people use them for planning before they buy. Others use them to understand the real cost of a loan they already have. The basic version shows a standard amortization schedule. The useful version accounts for extra payments, rate changes, and the actual math banks use. Most free templates you find online are useless past month three. They either round aggressively, ignore escrow entirely, or don't handle the first payment correctly. The first payment is weird because most loans don't start on the first of the month. You'll pay daily interest for the partial first period, and a bad spreadsheet will flat-out lie to you about that.
Building One That Actually Works
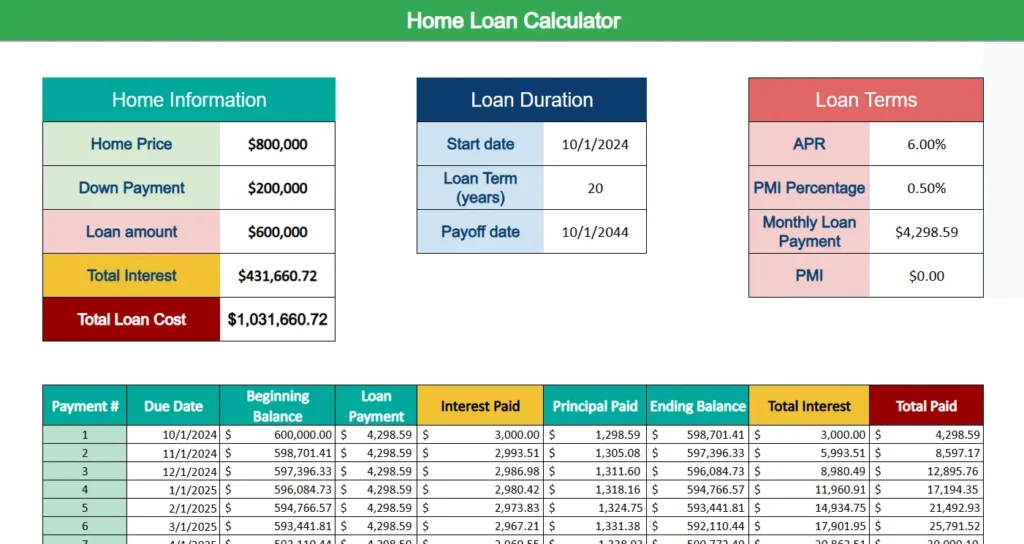
Start with the core loan inputs. You need the principal amount, annual interest rate, loan term in months, and the first payment date. That's it. Everything else derives from those four numbers. I always see people adding extra fields like property tax and insurance into the payment calculation before they even get the base payment right. Don't do that. Get the principal and interest payment working perfectly first, then layer the other costs on top as separate line items. For the monthly payment formula, use the actual annuity formula rather than approximating. In Excel or Google Sheets that's =PMT(rate/12, nper, -principal). The rate needs to be monthly, so divide the annual rate by 12. The negative principal sign makes the payment show as a positive number, which matters less than you'd think until you're summing columns and getting weird negatives everywhere. Now build the amortization table row by row. Each row needs: beginning balance, monthly payment, principal portion, interest portion, and ending balance. The interest for any given month is simply the beginning balance multiplied by the monthly rate. The principal portion is the payment minus the interest. The ending balance is the beginning balance minus the principal portion. Repeat for however many months the loan runs. A 30-year loan is 360 rows. A 15-year is 180. Don't build dynamic ranges that recalculate when you add rows, because that's how you lose track of which rows contain formulas and which contain manually entered numbers. This happened to me on a project where someone had pasted their own payment history into the table and accidentally overwritten a formula. Recovering the original structure took about forty-five minutes of manual reconstruction.
Common Pitfalls That Will Waste Your Time
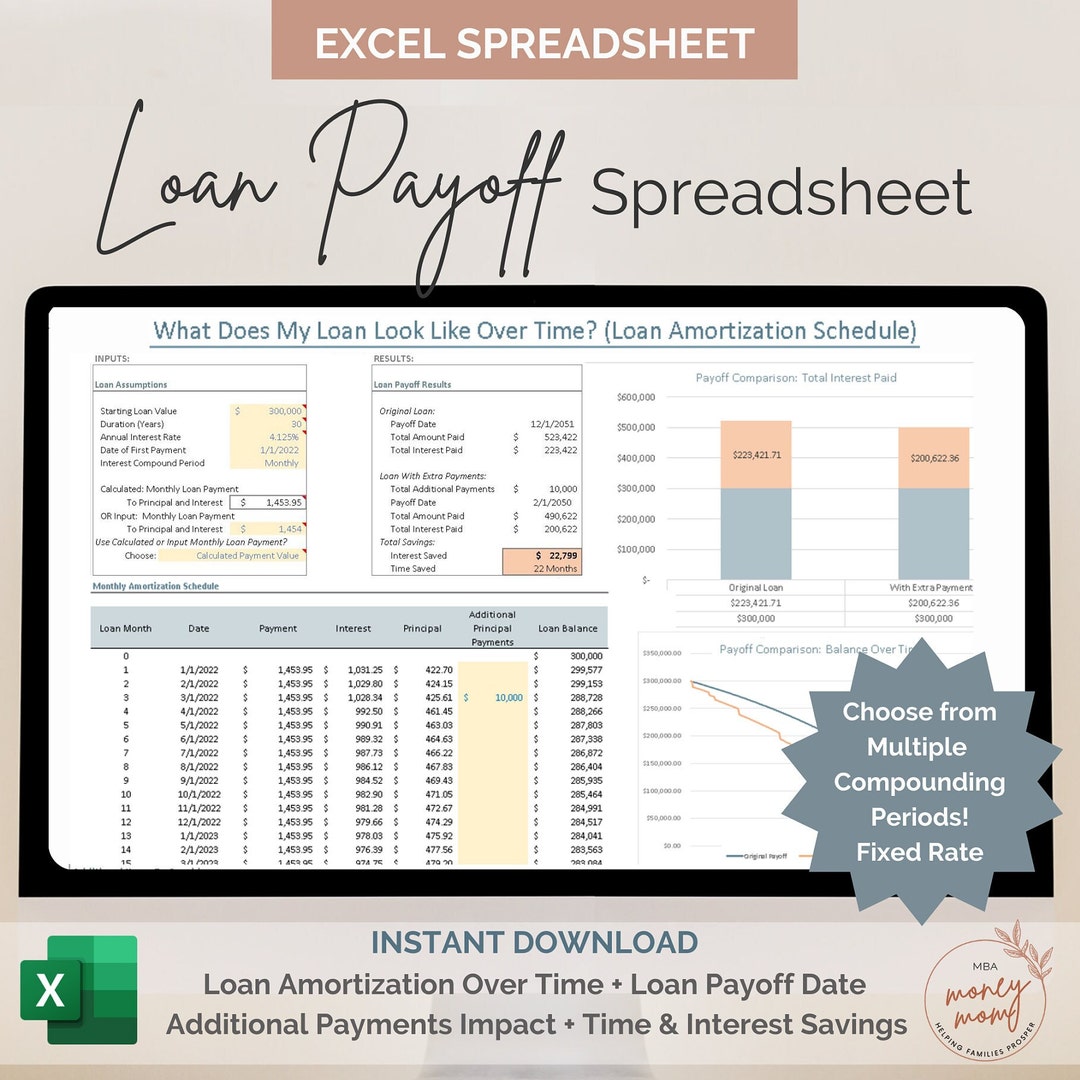
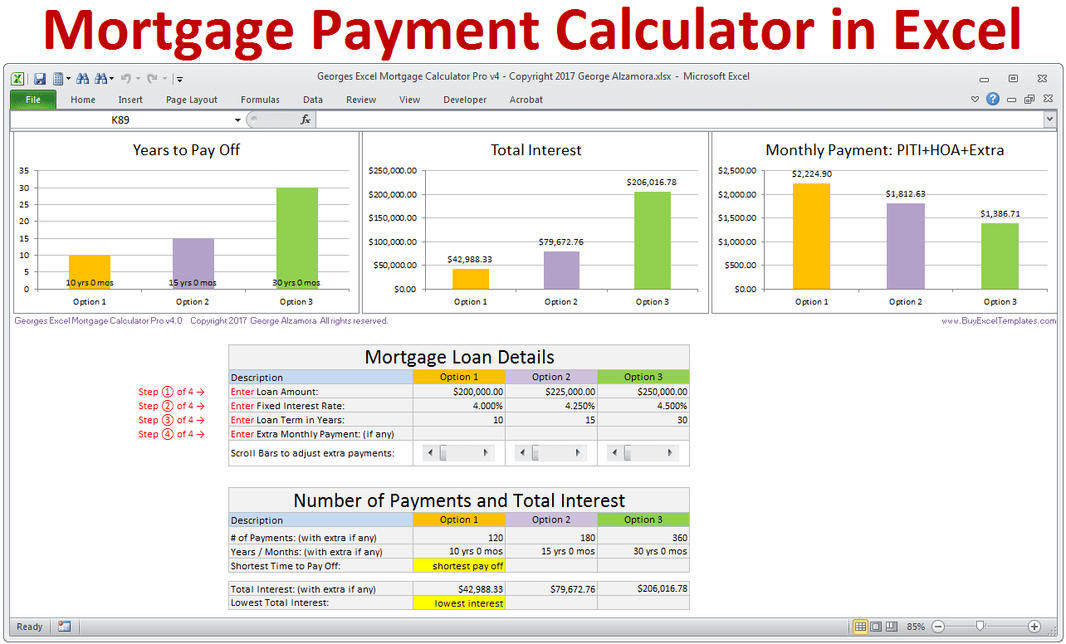
One mistake I see constantly is treating the annual percentage rate the same as the note rate. They're different. The APR includes closing costs and fees amortized over the loan term. If you're building a spreadsheet to compare actual monthly payments, use the note rate. If you're calculating the true cost of borrowing, factor in APR. Mixing the two up will make your totals look correct but your comparison logic broken. Another issue is not accounting for biweekly payments. Some lenders offer biweekly payment plans and your spreadsheet needs to handle the fact that you're making 26 half-payments per year, which equals 13 full payments instead of 12. A standard amortization table won't show this impact correctly unless you build in the extra payment math. I solved this once by adding a separate section that recalculates the schedule assuming biweekly payments and comparing the total interest paid between the two scenarios. It cut a 25-year payoff down to about 22 years on a conventional 30-year loan, which is a real number people can use in decisions.
Get the Full Details
What Your Spreadsheet Shouldn't Do
It shouldn't replace professional advice. Spreadsheets model simplified scenarios. They don't account for tax implications, insurance changes, or the possibility of refinancing mid-loan unless you explicitly build those features in. A spreadsheet showing you'll save $40,000 in interest by making extra payments is accurate within its own assumptions, but those assumptions might not hold if your situation changes. I've seen people lock themselves into rigid payment plans based entirely on spreadsheet projections, then get blindsided when their income dropped and they couldn't maintain the extra payments. The spreadsheet didn't warn them about that because it's not designed to. It also shouldn't be expected to handle adjustable-rate mortgages cleanly. ARMs require tracking rate adjustment dates, caps, margins, and index movements. A basic spreadsheet will give you garbage results for anything beyond the initial fixed period unless you build in scenario testing with different rate paths. This is where most people hit their limit with a DIY approach. If you have an ARM, consider using a dedicated mortgage calculator or consulting with a loan officer instead of trying to force a spreadsheet to do something it's not structured for.
Home Loan Spreadsheet
If you want something functional without building from scratch, the key is finding or building a template that uses unrounded intermediate calculations and clearly separates principal, interest, escrow, and taxes. Look for one that lets you input your actual closing date rather than assuming the first of the month. Test it against your closing disclosure before you trust any numbers it produces. If the spreadsheet's first payment doesn't match your lender's first payment to the penny, walk away and find a better template or rebuild the relevant sections. The math has to be right before anything else matters.