Why Most People Mess Up Their Rental Numbers
I've seen enough investors blow a deal because they punched numbers into a blank spreadsheet and called it analysis. A Home Profit Calculator is just a structured way to track income and expenses on a residential property so you're not guessing whether a rental actually pays for itself after everything gets paid out. That's literally all it is. It doesn't make decisions for you. It doesn't find you a ten-dollar bill in the drywall. It calculates. The most common mistake I see is treating the output as gospel without adjusting for vacancy, turnover costs, and maintenance reserves. A calculator will happily give you a positive cash flow number if you leave those fields at zero. They're not zero. They never are.
What a Home Profit Calculator Actually Does
It takes your expected rental income, subtracts operating expenses, subtracts debt service, and tells you what's left. Simple inputs: purchase price, down payment, interest rate, monthly rent, property taxes, insurance, vacancy rate, maintenance reserve, HOA fees, property management fees, and any other recurring cost. The output is net operating income, cash flow, cap rate, cash-on-cash return, and sometimes ROI across your total time horizon. That's it. I used a basic version back when I was doing turnkey flips in 2018, then migrated to a more detailed calculator once the deals got bigger and the line items multiplied. The ones that matter let you override defaults and save scenarios. If yours doesn't, you're stuck rewriting the same inputs six times to compare two neighborhoods.
How to Use One Without Getting Misleading Numbers
Enter the purchase price first. Then the down payment. The interest rate should match your actual rate, not the current average on a homepage banner. If you're running numbers at 6.5 percent and you actually close at 7.8, your monthly payment jumps roughly two hundred dollars and your cash flow drops with it. That gap alone kills half the deals I reviewed in 2020. Set vacancy to at least ten percent for a single-family rental. Ten percent is conservative if you're managing it yourself and the market isn't extremely tight. If you're in a high-turnover area like Tampa or Phoenix during seasonal migration months, bump it to twelve or fifteen. The calculator will punish you later if you set it at zero and then wonder where the money went every March. Maintenance reserve is where people lie to themselves. Put eight percent of gross rent as a floor. Some calculators call this CAPEX reserve. Same idea. Roof, HVAC, water heater, appliance replacements, patch work, tenant turnover painting, leak cleanup. All of that happens. I learned this the hard way in 2019 when a tenant trashed a unit in Atlanta, the AC failed two months later, and my vacancy line was already eating the cushion. The deal still worked but barely, and only because I hadn't financed the repair costs into the initial underwriting.
Get the Full Details

Include property management if you're not living within thirty miles. Even if you manage it yourself right now, include it at five to ten percent so you can compare the real deal to the one where you hire help next year. It changes the picture, usually not fatally.
The Edge Case That Broke My Spreadsheet
I had a Duplex in Columbus where one side was owner-occupied and the other was rented. I also had a short-term rental permit on the back unit, which meant nightly income, higher utility costs, cleaning fees, and a completely different tax treatment than a standard long-term rental. My generic Home Profit Calculator couldn't handle split income streams and different occupancy models in one tab. I tried to fake it by averaging monthly rent, and the output was useless. I ended up building a second sheet just for the STR portion, merged the two cash flows manually, and flagged the higher short-term tax bracket separately. The workaround was straightforward: track each income source and expense category individually in columns, then sum them at the bottom. Most decent calculators let you add custom line items. If yours doesn't, you're better off using a simple grid in Google Sheets and building formulas instead of fighting a rigid tool.
Which Metrics Actually Matter
Cash flow is what keeps the lights on. Cap rate tells you how efficient the asset is relative to its value without debt. Cash-on-cash return shows you how your actual down payment and closing costs perform. Net profit margin gives you the percentage of revenue that survives all expenses and debt. These four numbers answer different questions and none of them are sufficient alone. If you only look at cap rate, you'll buy a property that looks great on paper and can't cover the mortgage after insurance spikes. If you only look at cash flow, you might miss that a $20,000 roof replacement wipes out three years of profit. I used to chase fifty-dollar-a-month cash flow and then wonder why I was still broke. The fix was to require a minimum cash-on-cash of eight percent and a cap rate above the local average by at least one point.
Download and Setup
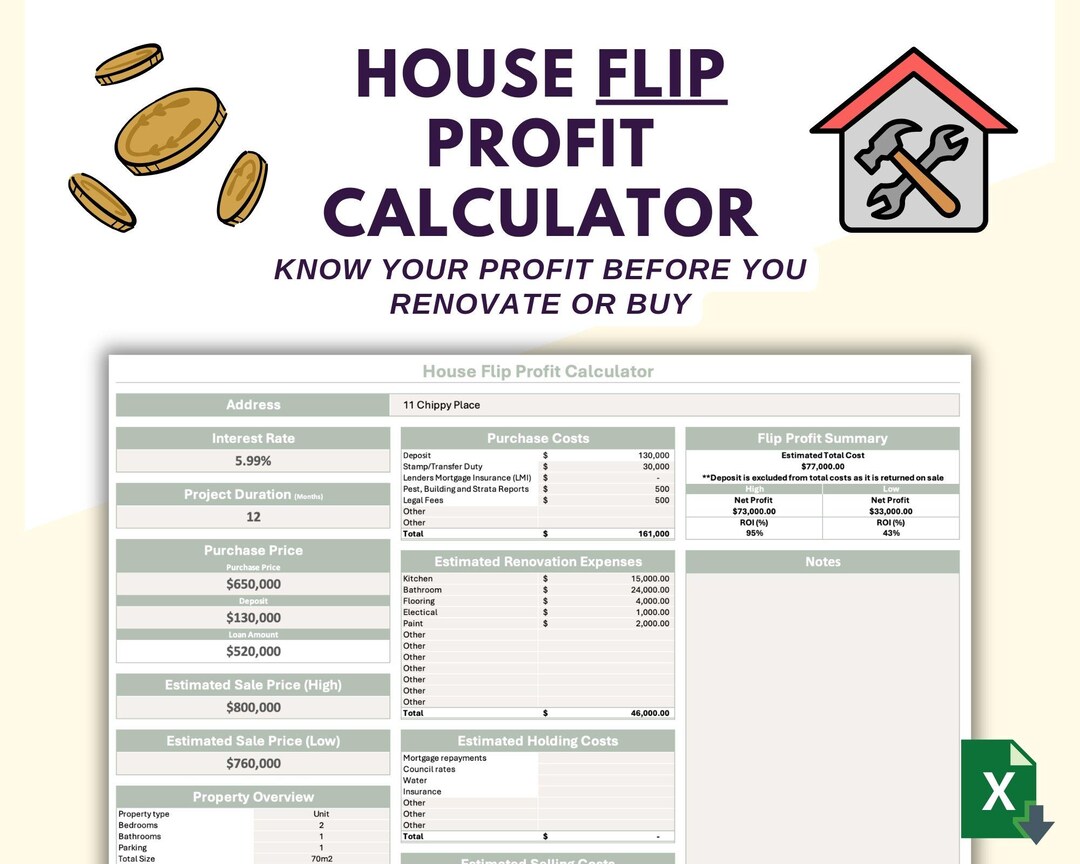
There are several free calculators online. The type you want is one that lets you edit every input, save multiple deals, and export the results. I keep a shared Google Sheet with twenty rows, one per active deal, linked to a Home Profit Calculator template I built over three years. It calculates monthly cash flow, annual cash flow, cap rate, cash-on-cash return, and break-even rent in one pass. You can download a similar template from most real estate investing forums or build one yourself in about an hour. Spend the hour. Prebuilt tools vary wildly in how they handle insurance estimates and tax assumptions, and you'll spend more time correcting their defaults than fixing your own. It fails when the input data is wrong. There's no formula that fixes garbage inputs. It also fails when you ignore financing changes mid-hold, refinance terms that weren't modeled, or special assessments and Mello-Roos in certain California and Florida communities. Those line items show up late and they're nasty. I learned that in 2022 when a newly built property in Orange County hit me with a Mello-Roos charge I hadn't accounted for because it was buried in the disclosure packet and labeled differently from a standard HOA fee. If you're comparing multiple properties, run them all through the same calculator with identical assumptions. Otherwise you're comparing apples to oranges disguised as numbers. I once picked a deal that looked better on paper only because I had accidentally entered a lower insurance estimate from a previous year's quote. The corrected calculator showed it was a month behind the other property, not ahead.
A Few Practical Rules
Always run a downside scenario with vacancy at fifteen percent and maintenance at twelve percent. If the deal still works, you're likely fine. If it doesn't, you just avoided buying a house that would have required a second job to service. Keep your calculator versioned. Rename it with the date and the property address. When you revisit a deal six months later, you'll thank yourself for not trying to remember which assumption you changed last time. Never treat the output as a final decision. It's a screening tool. The property still needs inspection, appraisal, title work, and market validation. The calculator filters deals. It doesn't validate them.