What a Home Renovation Loan Calculator Actually Does
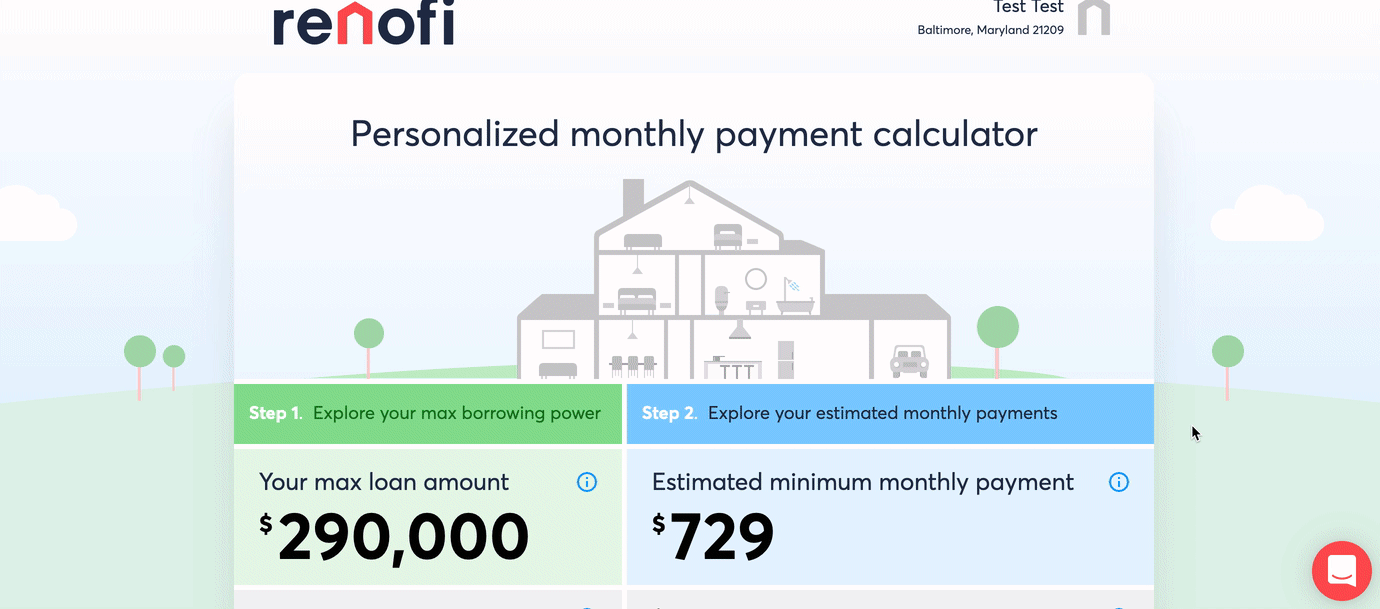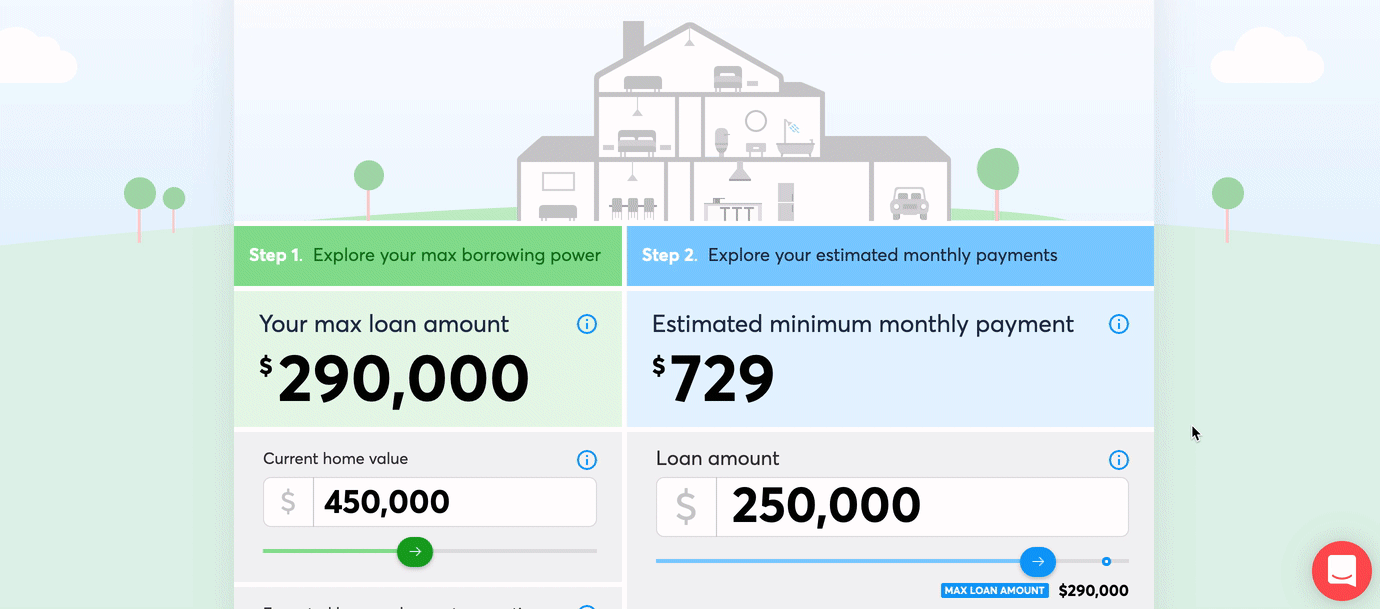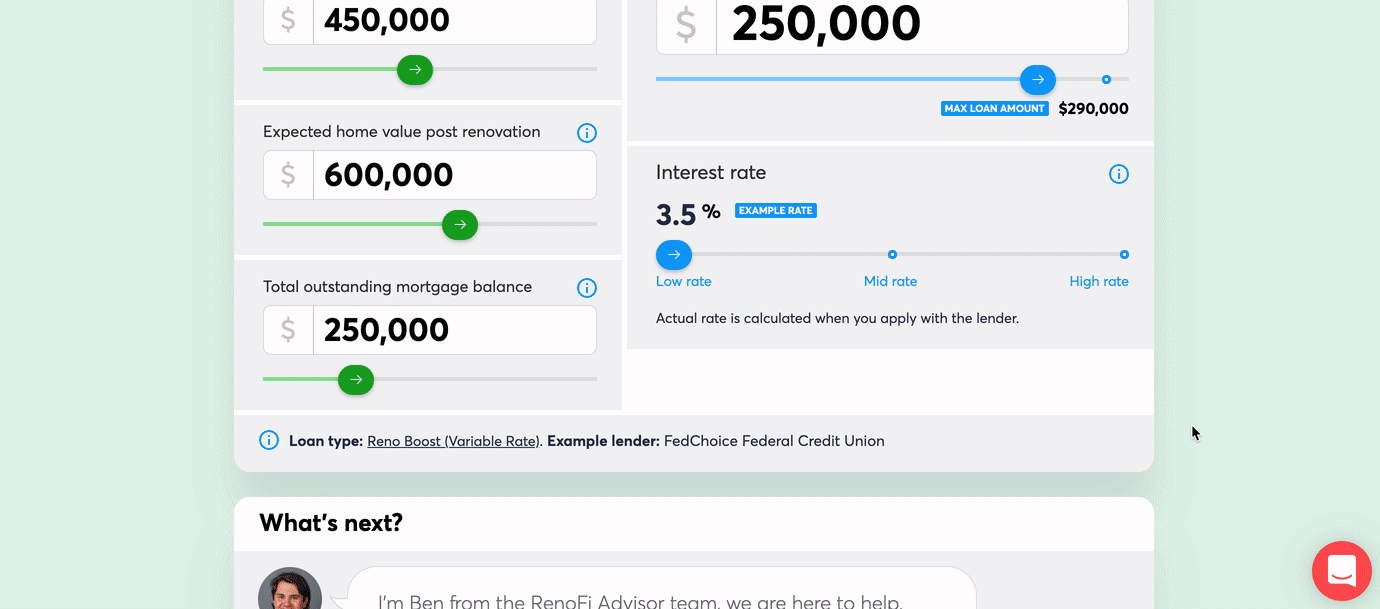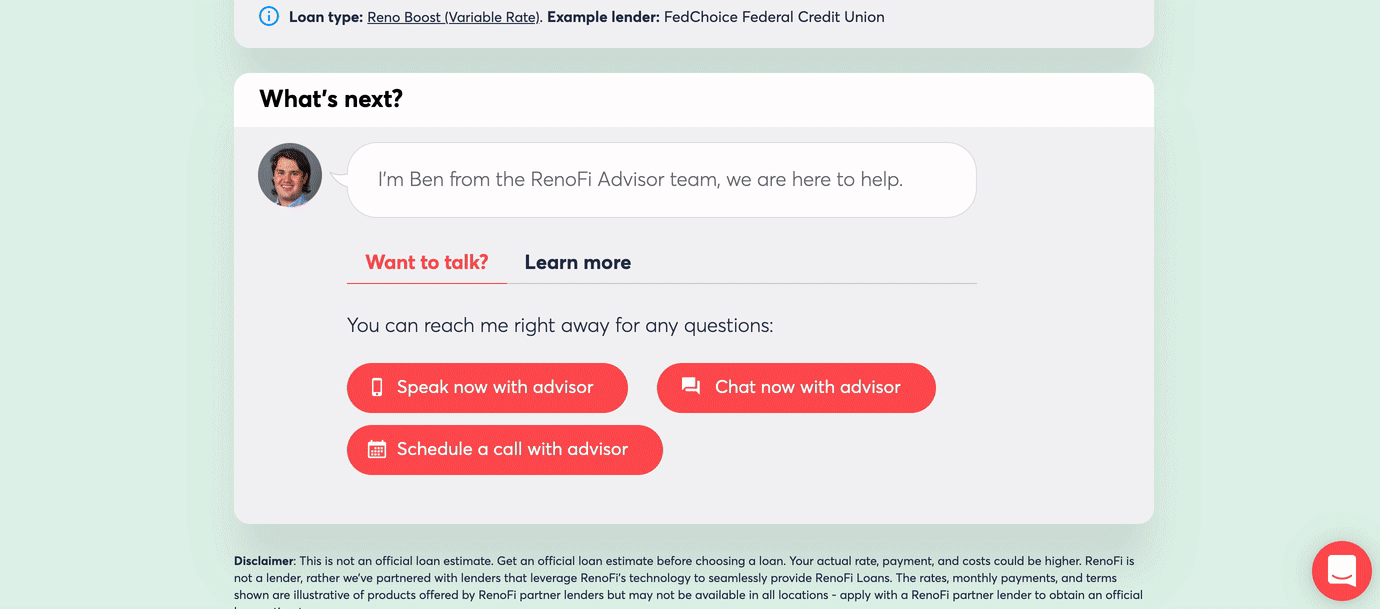
A Home Renovation Loan Calculator is a tool that estimates your monthly payments based on the loan amount, interest rate, and repayment term. Most people assume it gives them a single fixed number, but that is not quite right. The output is more of a starting point than a final answer. You plug in your numbers and get a range that tells you roughly what the lender will likely offer you, but the exact payment depends on fees, points, and how your credit profile gets priced in. I used to think these calculators were just simple math engines. That changed after I ran into a situation where my calculator showed a payment of $1,420 per month on a $60,000 renovation loan at 7.5% over 15 years, but the actual lender quote came out to $1,587. The difference was not rounding error. It was lender fees baked into the amortization. Origination charges, document prep fees, and a discount point I had not factored in pushed the real number higher. The calculator had shown the principal and interest only. Everything else was sitting outside the box.
How to Use a Home Renovation Loan Calculator Correctly
The best approach is to treat the calculator as your first rough estimate, then adjust it manually for the costs that standard tools ignore. Here is how I walk through it now. First, figure out your total project cost. Not the contractor's lowest bid. The realistic cost including permits, inspections, contingency, and design fees. I once entered $45,000 as my project cost when the actual budget was $62,000 because I forgot about the electrical upgrade permit that came with a full kitchen remodel. That missing $17,000 created a huge gap between what the calculator predicted and what I actually needed to borrow. The loan amount drives everything downstream, so getting it right matters more than anything else. Next, enter that loan amount into the calculator along with the interest rate and term length. Make sure you are using the rate you were actually quoted, not the promotional rate from a bank ad. Lenders show one rate to get your attention and another rate to close the deal. I learned this the hard way when a lender quoted 6.25% in their marketing material but my actual rate came in at 7.875% once the application went through. The calculator output changed by nearly $200 per month between those two rates on a 20-year term.
After you have the monthly payment number, add the lender fees separately. Origination fees typically run between 0.5% and 1% of the loan amount. That is $300 to $600 on a $60,000 loan. Document fees, appraisal fees, and title work add another $500 to $1,200 depending on your region. Some lenders roll these into the loan balance, which increases your monthly payment further. Others want them paid at closing, which changes your cash-out requirement. If your lender offers discount points, calculate what those cost you upfront versus what they save you in interest over the life of the loan. One point equals 1% of the loan amount and typically drops your rate by about 0.25%. On a $60,000 loan, one point costs $600 and might save you roughly $40 per month. That is a breakeven at about 15 months. If you plan to stay in the home beyond that, it makes sense. If you are renovating to sell within a few years, it does not. Run the numbers through the calculator again with the adjusted loan balance if fees are being rolled in. Then compare the total cost across different scenarios: shorter term with higher payment, longer term with lower payment, paying points upfront versus financing them. I usually set up three or four variations side by side before I talk to a lender.
Get the Full Details
Where These Calculators Break Down
The biggest blind spot is that most calculators assume a fixed-rate loan with no variable components. HELOCs, which are very common for renovations, operate on a completely different model. The calculator cannot accurately model a HELOC because the draw period and repayment period have different rate structures, and the minimum payment during the draw period is often interest-only. I have seen people use a standard calculator for a HELOC scenario and end up surprised when their actual payment jumped from $380 during the draw phase to $890 once the repayment phase kicked in. Another issue is that calculators do not account for lender-specific pricing tiers. Your credit score range, debt-to-income ratio, and loan-to-value ratio all affect the rate you get, but the calculator shows a single rate input. You have to manually adjust for your own profile. A borrower with a 740 credit score might get 7.25%, while someone with a 660 score gets 8.5% on the same product from the same lender. The calculator treats them identically unless you manually change the rate input for each scenario. Renovation-specific loans like FHA 203k or Fannie Mae HomeStyle have additional requirements that affect the loan amount and payment structure. These loans require a consultant to outline the work, and the loan amount includes both the existing mortgage balance and the renovation costs in some cases. A standard calculator will not model this properly because it does not know about the rehab scope or the after-improved value cap. I had to switch to a specialized calculator for a 203k project and manually adjust the numbers for the consultant fee and the minimum renovation threshold of $5,000.
The calculators also tend to ignore prepayment penalties. Some renovation loans carry a yield spread premium or a prepayment penalty if you pay off the loan within the first three years. If you are renovating to flip or move within a short timeframe, that penalty can add several thousand dollars to your actual cost. The calculator never shows this, so you have to read the loan estimate documents carefully to find it.
Practical Numbers to Keep in Mind
On a typical mid-range renovation loan of $50,000 at 7.75% over 15 years, you are looking at approximately $489 per month in principal and interest. Add origination and closing fees of roughly $900 to $1,500 depending on the lender. If you finance the fees into the loan, the payment climbs to about $515. Over 15 years, the total interest paid on the base loan is roughly $38,000. If you include the financed fees, the total interest rises to around $41,000 because you are paying interest on top of interest from day one. For a 30-year term on the same $50,000 at 7.75%, the payment drops to about $358 per month, but the total interest climbs to roughly $78,800. The shorter term costs more each month but saves you about $40,000 in interest over the life of the loan. That is a significant difference, and the calculator will show it clearly if you run both scenarios. Most people pick the longer term because the monthly payment feels more comfortable, but the total cost is nearly double. If you are comparing a conventional renovation loan against a HELOC, run the calculator for both. A HELOC at 8.5% on a $50,000 balance with interest-only payments during a 10-year draw period would show $354 per month in the calculator, but that payment only covers interest. After the draw period ends, the repayment calculation changes entirely and could push your payment well above $500 depending on the remaining term and rate.
The calculator is useful for giving you a baseline understanding of what you are working with. It will not tell you exactly what a lender will offer you, but it will prevent you from walking into a conversation completely unprepared. I usually spend about 20 minutes filling in the numbers across three or four scenarios before I ever call a lender. That preparation saves time on both sides and keeps you from accepting the first offer you hear.