Why most people skip this step and lose money anyway
Most people buying a house to flip think they can eyeball the numbers. They walk through a property, guess what repairs might cost, check Zillow for similar sales, and throw together a rough profit estimate in their head. Then they buy the house, discover three things they missed, and pray they still come out ahead. This works fine when you have maybe five deals a year and a tight circle of contractors who give you straight answers. It stops working when market conditions shift even slightly. A proper House Flipping Market Analysis is just a systematic way of confirming whether a deal actually makes sense before you put any money down. The goal isn't to predict the future perfectly. It is to reduce the number of variables you are guessing about to something manageable.
House Flipping Market Analysis: The Practical Method
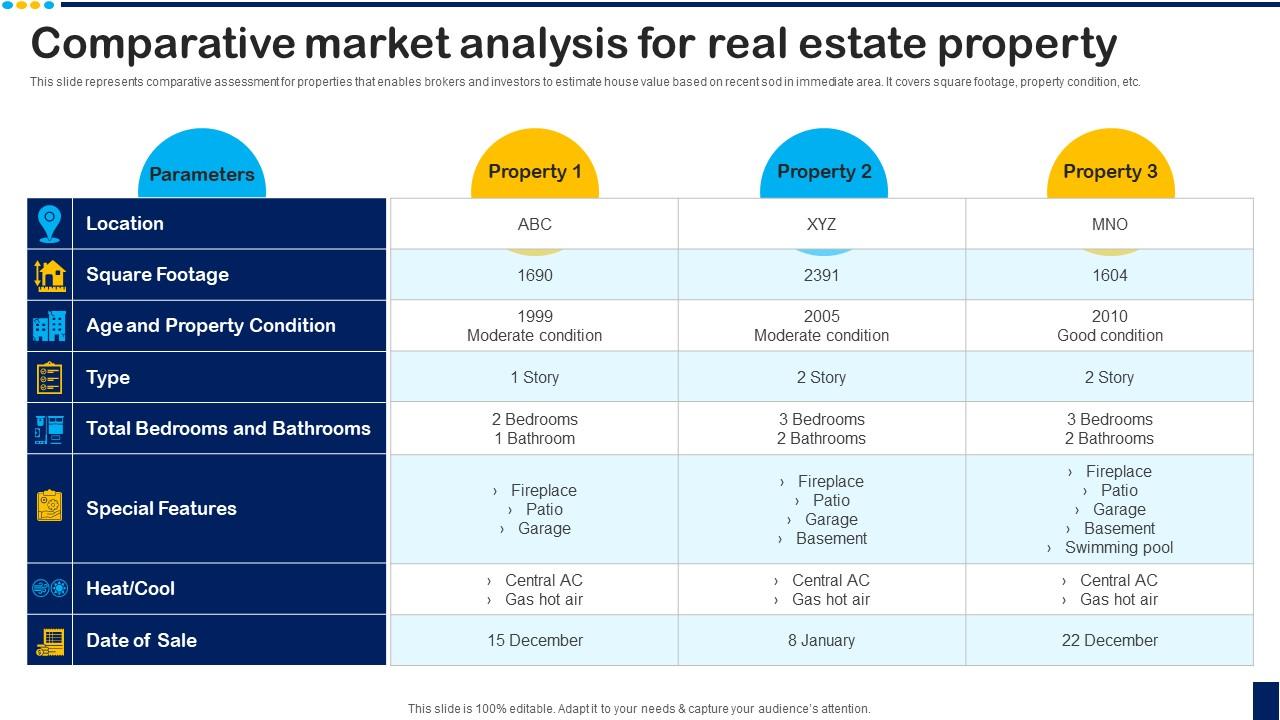
Here is how I actually run through the process these days. Start with a target neighborhood or zip code where you have bought before. Pull the last twelve months of comparable sales from your local MLS, not Zillow. Zillow gets the timing wrong on some listings and misses off-market sales that move at very different price points. I run a CSV export from my realtor's system and filter for properties sold in the last year that are within a quarter mile, built within ten years of your subject property, and have similar square footage and lot size. You want at least eight comps. Fewer than eight and the data set is too thin to trust. Next, figure out what a finished version of your target property would likely sell for. Take the median of those comp sales and call it your after repair value. Now work backward. The standard formula most people learn is purchase price plus repairs plus holding and closing costs, and you need to leave a margin of twenty to twenty five percent on top of that total. That margin covers your profit and the risk of something going sideways, which it always does. I track three numbers per deal instead of two. The first is the ARV. The second is the total project cost including the purchase price. The third is my exit strategy. If the numbers work for a resale but not a rental, I note that. Some suburbs have terrible cash flow for investors but strong appreciation, and others go the opposite direction. Knowing which one you are dealing with changes how aggressively you should bid.
One tool I use is a spreadsheet called the deal screener. I built it years ago and updated it after the rate environment changed in 2022. It takes your purchase price, estimated repairs, estimated closing costs on the buy side and sell side, monthly holding costs, and an assumed rehab timeline. The spreadsheet spits out the maximum allowable offer and the projected profit under two exit scenarios. It usually takes about fifteen minutes to fill out once you have your comps loaded in. Without it, I was spending closer to two hours per deal on manual calculations, and I was making math errors I did not catch until it was too late. Repairs are where most people get tripped up. Contractors give you a range, not a number. A kitchen remodel can be fifteen thousand or forty thousand depending on whether you change cabinets or just refinish them. My workaround has been to run two rehab budgets for every deal. A minimum viable version that gets the house marketable, and a realistic version based on what I have actually spent on similar properties in that neighborhood. I use the realistic number for my MAO calculation and the minimum viable version only as a stress test to see how much cushion I have if things go cheap.
Get the Full Details
What nobody tells you about comps
The most useful piece of advice I have learned is that comps can lie to you if you take them at face value. A house selling for a high price does not automatically mean the neighborhood supports higher prices. Sometimes the comp was a fire sale that dragged the average down. Sometimes it was an emotional overbid from a buyer who could not resist a corner lot. Sometimes the sale was between relatives. You need to read the listing history and the days on market for each comp. If a comp sat for sixty days and then sold, that tells you something different than a comp that went under contract in eight days. Fast sales with prices above list usually signal a hot submarket. Slow sales at or near list suggest the pricing was fair but demand was weak. If you use a fast sale as your primary comp, your ARV estimate will be optimistic. If you use a slow sale, it will be pessimistic. The truth is somewhere in between, and the spread between those two numbers is your risk buffer. I also look at the price per square foot across my comp set. When that number jumps around a lot, the neighborhood is inconsistent, and it is harder to value a specific property. When it clusters tightly, you can be more confident in your ARV. This single check catches problems that raw sale prices hide.
Another thing beginners miss is that you should weight your comps by recency. A sale from three months ago matters more than a sale from eleven months ago, especially in a market where interest rates have shifted. My spreadsheet applies a simple decay factor that reduces the influence of older comps by about ten percent per quarter. It is not perfectly scientific, but it keeps stale data from dragging your estimate in the wrong direction.
When this method breaks down
House Flipping Market Analysis works best in stable suburban markets with active MLS systems and consistent sales volume. It is less reliable in rural areas where there are few recent sales, in unique properties where comparables do not exist, and in markets experiencing rapid price swings because your data is already stale by the time you pull it. I ran into this exact problem last spring. I was evaluating a property in a transitioning neighborhood where three new builds had recently sold at high prices, but the surrounding area still had older homes selling well below those numbers. The raw comp set was split almost in half, and the median sat right in the middle of nowhere. If I had used the median as my ARV, I would have overpaid for the property. The newer builds were priced for buyers who wanted custom finishes and a different lifestyle than what the rest of the neighborhood could support. My workaround was to ignore the median and treat the two groups as separate comps. The property I was looking at was an older home that needed significant work, so I anchored my ARV to the older group but gave a modest upward adjustment for the improvement scope. I also pulled permit data from the city to see how many of the new builds were actually selling to owner occupants versus investors. A lot of them were investor purchases, which meant the high prices were partly artificial. Once I stripped that out, the real ARV dropped by about eight percent, and I adjusted my bid accordingly. I still made the deal, but the analysis changed enough that it mattered.

The part that actually saves deals
The single most practical step in any House Flipping Market Analysis is the hold cost calculation. People focus on purchase price and repairs and forget that money bleeds while the house sits unsold. In a typical six month flip, that includes property taxes, insurance, utilities, HOA fees, loan interest, and opportunity cost. On a hundred and fifty thousand dollar deal with a ninety day hold, interest alone can eat three to four thousand dollars depending on your financing terms. If the rehab runs two months longer than planned, which it frequently does, you are looking at another six to eight thousand in holding costs. I always budget eight percent longer than my gut says the rehab will take. That number comes from watching my own projects. If I think a kitchen and bath update will take six weeks, it takes seven. If I think the whole project will take four months, it takes four and a half. Adding that buffer into the hold cost model changes the profit projection in a way that is easy to ignore but painful to overlook later. If you want the spreadsheet I mentioned, I put a copy on my site along with a guide to reading MLS exports. The download link is in my profile. The spreadsheet is formatted for Google Sheets and Excel. It has a tab for pulling comp data, a tab for running the deal math, and a tab that shows you the sensitivity of your profit to changes in ARV, rehab cost, and hold time. I find that last tab useful for explaining to partners or lenders why a deal has a narrow margin even when the numbers look fine on the surface.
How to avoid the most common mistake
The mistake is using a single exit strategy when the market can support either resale or rental. I have seen investors lock into a flip plan and then realize the neighborhood is actually better suited as a rental market. By the time they notice, they have already closed on the purchase. The fix is to run both scenarios before you bid. Calculate the projected profit from a resale using your rehab costs and estimated sell time. Then calculate the cash flow from a rental using a conservative vacancy rate and management fee. If either scenario works, you have flexibility. If only one works, you need to commit to that path from the start. Running both numbers takes another ten minutes in the spreadsheet. It prevents the situation where you are holding a property for nine months and then cutting your losses because the resale math stopped working when rates moved against you. I prefer having the option to rent when the sale path looks thin, but that only works if I knew in advance that the rental path was viable.


