How to Actually Use a House Loan Payoff Calculator Without Losing Your Mind
I spent three years building mortgage payoff spreadsheets for people who didn't want to think about their debt. Most of them used calculators wrong, or trusted numbers they shouldn't have. Here's what actually works. A House Loan Payoff Calculator is a tool—usually digital—that takes your remaining principal, your interest rate, and your monthly payment to estimate how long it will take to pay off a home loan. It can also project extra payments, lump-sum reductions, and the total interest you'll save by accelerating payoff. Some versions factor in taxes and insurance, but the core engine is just amortization math. The standard formula behind these calculators is straightforward:
n = -log(1 - (r × P) / A) / log(1 + r) Where n is the number of payments, r is the monthly interest rate (annual rate divided by 12), P is the remaining principal, and A is the monthly payment amount. If you're making extra payments, you subtract them from A or treat them as periodic principal reductions. The calculator handles the log functions for you. You provide the inputs. I built my first reliable version in 2018 because every free online calculator I found either ignored tax escrow or gave garbage results when you input a balloon payment. The version I still use now runs on a modified Excel template that cross-checks against a Python script using the numpy financial functions. Cross-checking matters. Excel's NPER function returns slightly different results than hand-calculated amortization tables due to rounding at each period. The difference is usually cents, but over 30 years it adds up to hundreds of dollars if you're not tracking it.
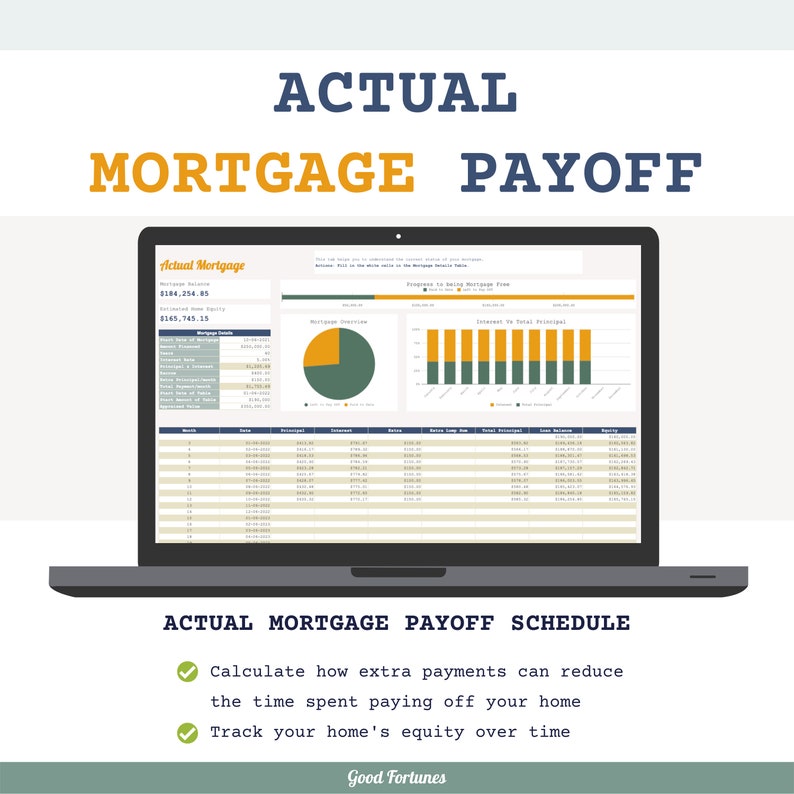
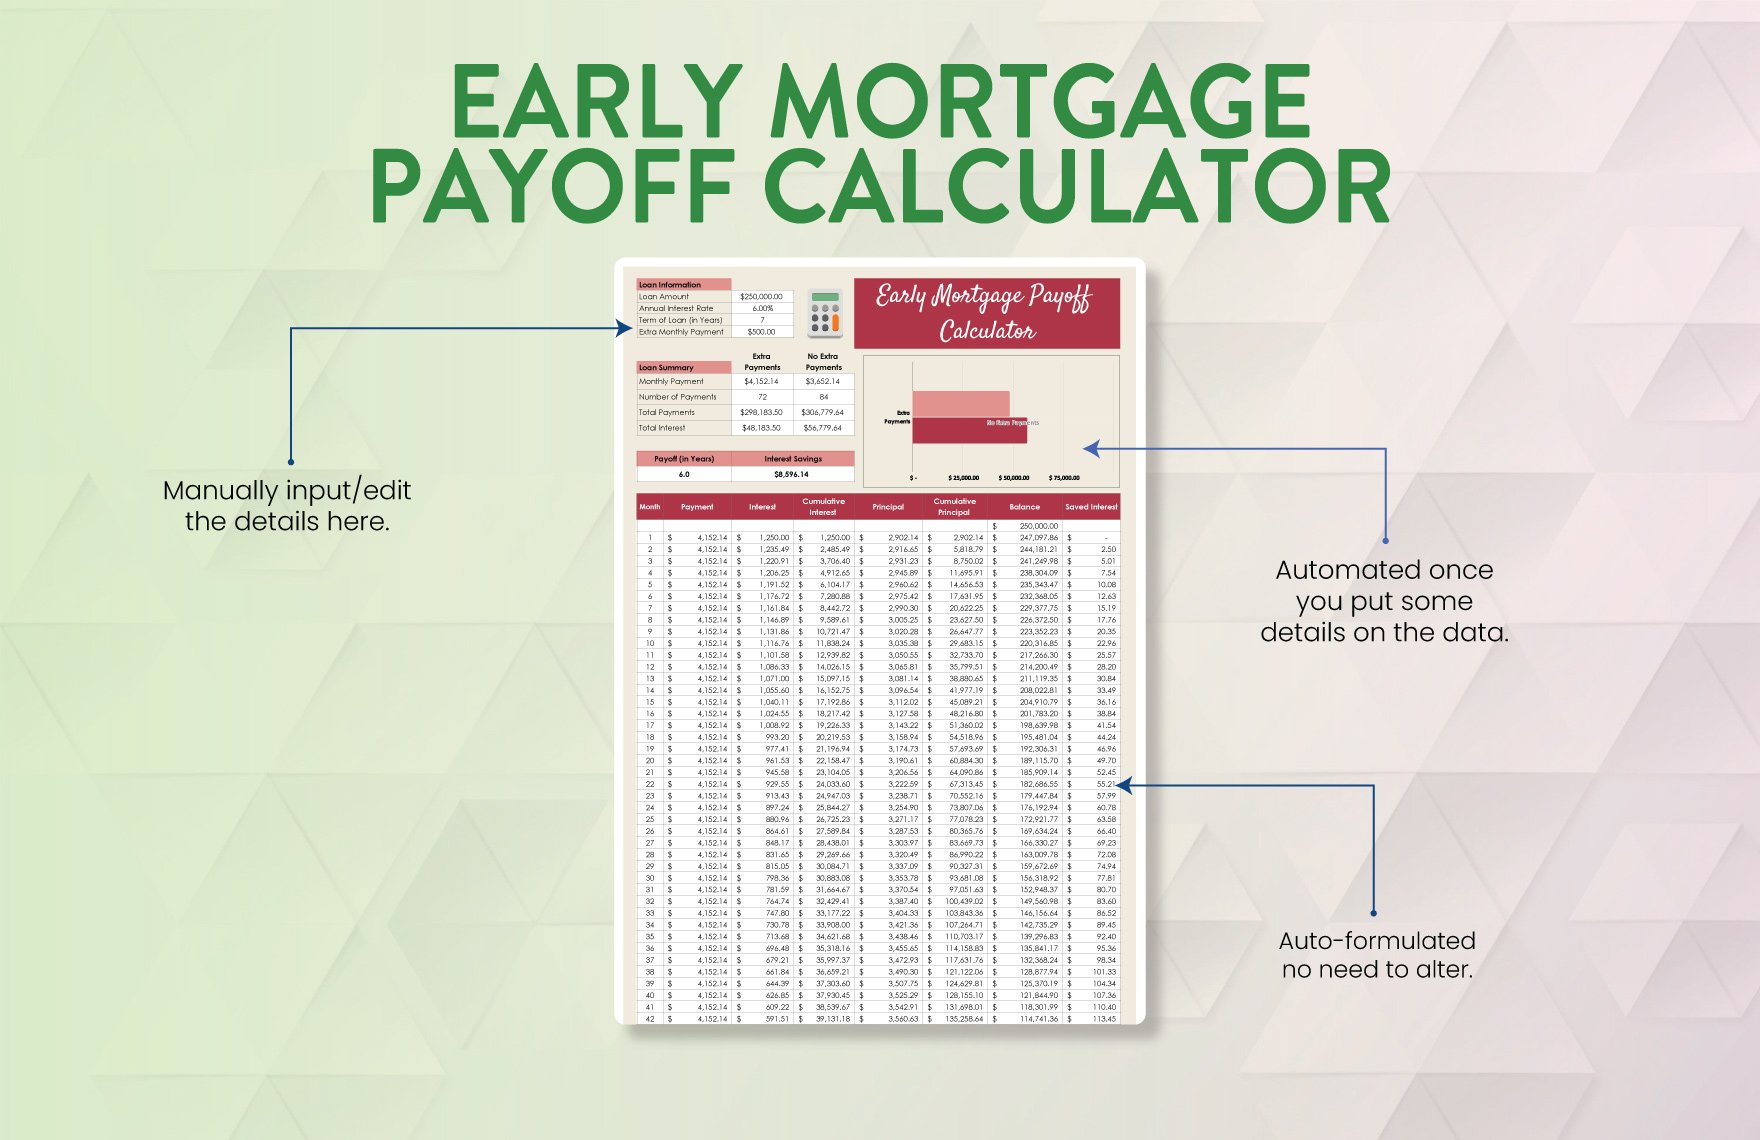
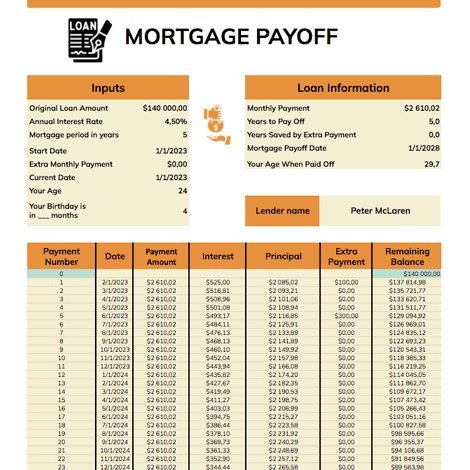
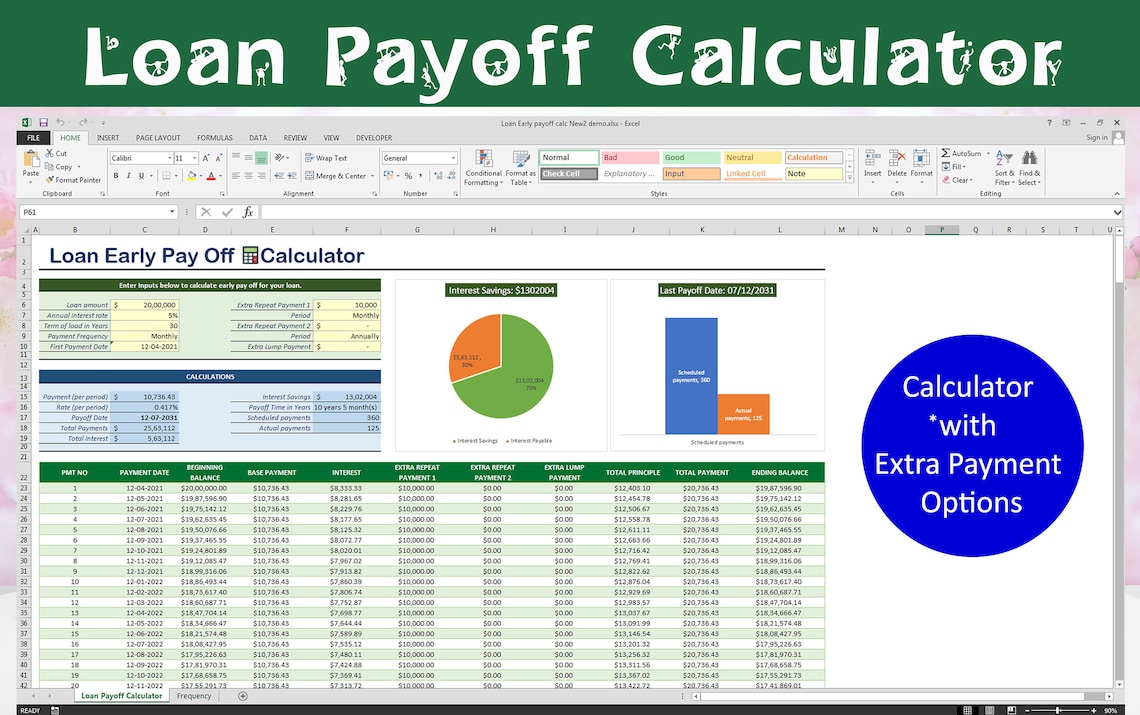
Here's the honest part most calculators won't tell you: payoff calculators assume your interest rate is fixed. If you have an adjustable-rate mortgage, the calculator's output is a guess, not a projection. I had a client in 2022 who used a static calculator for her ARM and couldn't understand why the payoff date kept shifting every time the rate adjusted. She ended up refinancing into a 15-year fixed and ignored the ARM calculator entirely. Good call on her part, but she'd been staring at wrong numbers for eight months. Another thing that trips people up: some calculators treat your monthly payment as a flat number regardless of whether it includes escrow. If your payment is $1,800 and $400 goes to taxes and insurance, the calculator needs to know that only $1,400 goes toward principal and interest. Feed it the full $1,800 and you'll get a payoff date that's wildly optimistic. I've seen people think they'd be debt-free in 18 years when the real answer was 26. The mistake is always the same—entering the total monthly obligation instead of the principal-and-interest portion. If you want to download a working template, I keep a version on Google Sheets that handles principal-only extra payments, annual escrow adjustments, and rate changes. It's not fancy. It shows the remaining balance after each payment, the cumulative interest paid, and the accelerated payoff date. You can find it by searching for my Sheets library under the name "Agnes Mortgage Tools"—the payoff sheet is the second one listed. The link is free, no email gate, no premium tier. That's unusual for this kind of thing, but I don't monetize templates.
Get the Full Details
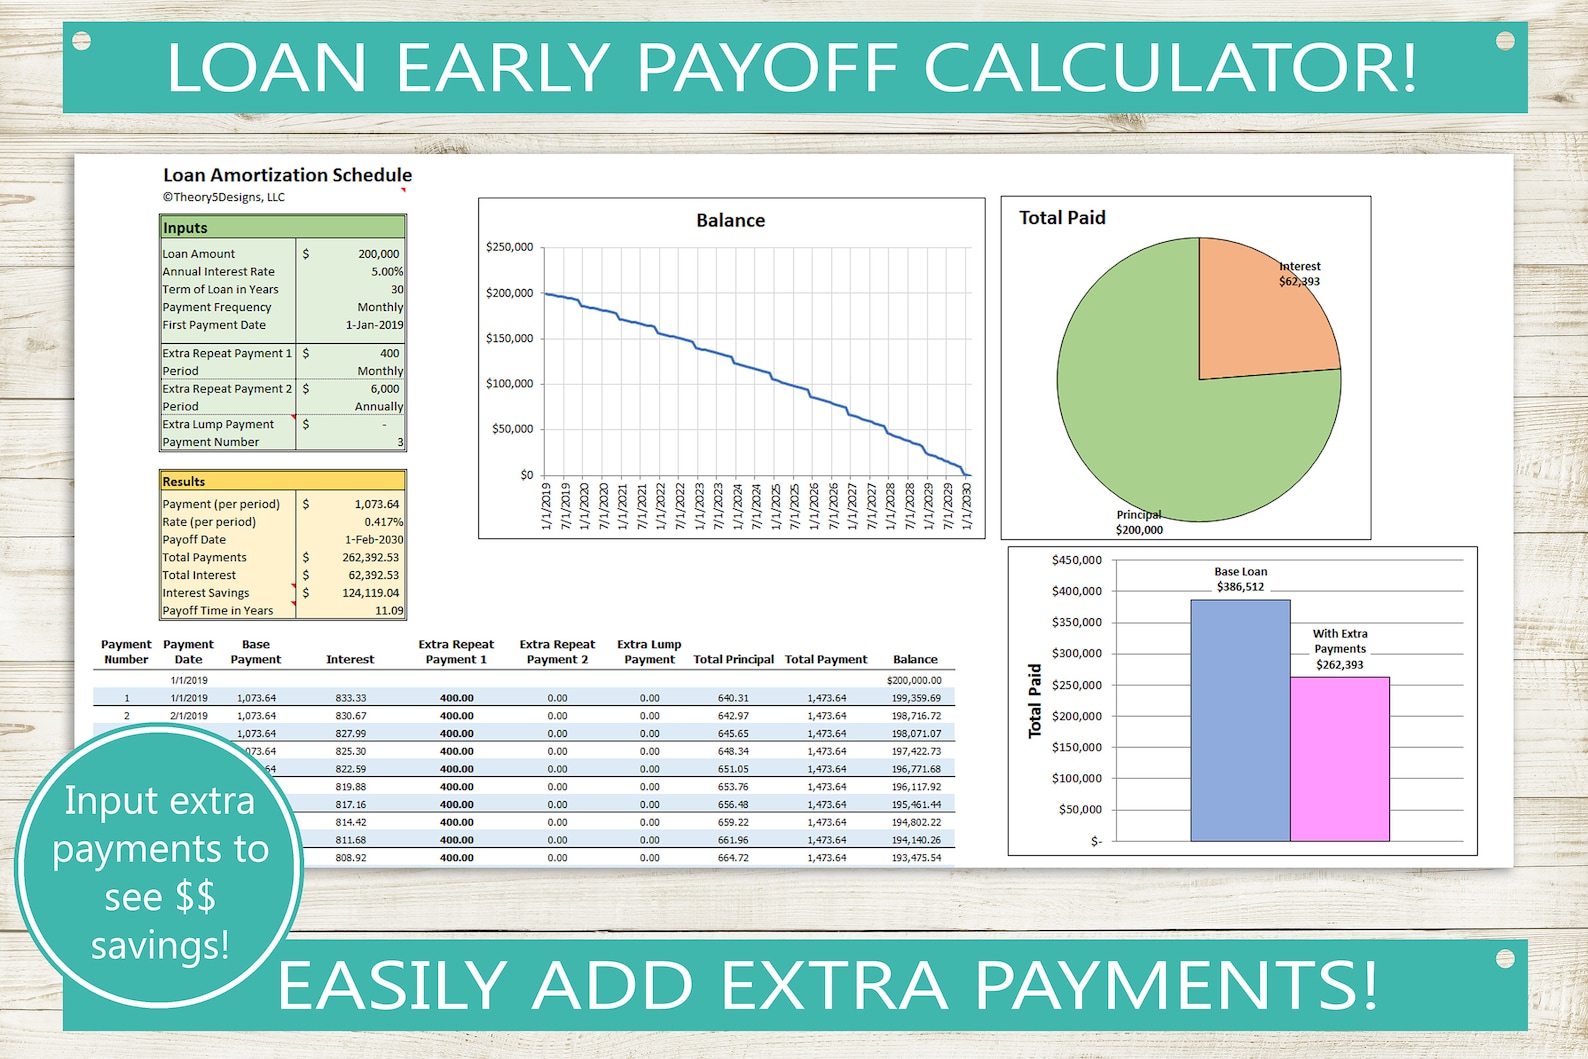
There are real limitations to what any House Loan Payoff Calculator can do. The biggest one is prepayment penalties. Some loans charge a fee if you pay down principal faster than a certain threshold in a given year. Calculators almost never model this correctly. If your loan has a prepayment penalty clause, run the numbers through the calculator first, then subtract the penalty cost from your projected savings. The penalty is usually a percentage of the prepaid principal during the penalty window—typically 2% in year one, 1% in year two, zero after that. I once calculated a $47,000 interest saving for a client, then discovered her loan had a 3% prepayment penalty on the first $50,000 of extra principal paid in year one. The penalty ate $1,500 of her projected benefit. Not catastrophic, but it mattered. A second blind spot is refinancing. Some payoff calculators let you model a refinance mid-loan, but most don't recalculate the old loan's payoff amount correctly. When you refinance, you don't just swap rates—you reset the term, and the remaining balance from the old loan becomes the new principal. I've seen calculators that kept the original amortization schedule running in the background, which produced nonsense. Always verify that a refinance model resets the amortization clock from the payoff date of the original loan. The best way to use a payoff calculator is to treat it as a directional tool, not a precision instrument. Run three scenarios: current payment only, current payment plus a fixed extra amount each month, and current payment with a larger lump sum every six months. Compare the three. The differences between them will show you where extra money actually moves the needle. Usually it's in the first five years, when the interest portion of your payment is largest. After year ten, extra payments still help, but the marginal benefit drops significantly because most of your payment is already going toward principal.
If you're doing this for a real loan and need absolute accuracy, export your amortization schedule directly from your lender's portal. They have the exact payoff accrual dates, any escrow adjustments on file, and the precise principal balance as of today. A calculator will always be an estimate because it doesn't know your lender's day-count convention. Some lenders use 30/360. Some use actual/365. The difference is small but measurable over a full loan term. Most people don't need perfect accuracy. They need to know whether paying an extra $300 a month shortens their loan by two years or twelve. The calculator gets that right almost every time. The rest is just reading the output without panicking at the total interest column.