
How to Use a House Payment Calculator for Indiana Properties
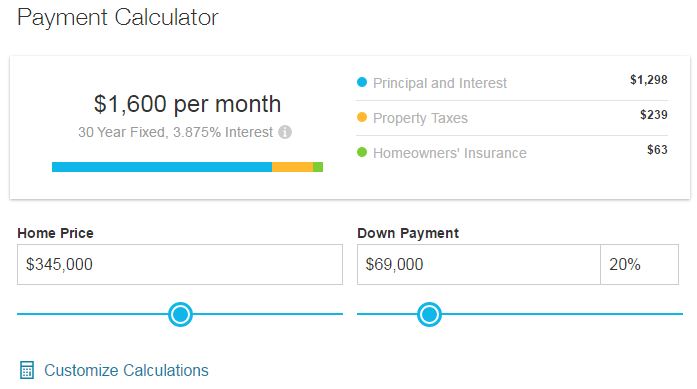
Most people who pull up a House Payment Calculator Indiana don't realize how much the numbers shift once you start factoring in property taxes, homeowner's insurance, and the specific mortgage products available in this state. I've been working with residential mortgages in Indiana for over a decade now, and I can tell you that the biggest mistake buyers make is plugging in a generic number and calling it done. Indiana property tax rates vary wildly from county to county, and that alone can throw your monthly payment off by a few hundred dollars. A basic calculator takes your home price, down payment, interest rate, and loan term, then spits out a monthly figure. That part is straightforward. The problem is that the output rarely includes everything that goes into your actual payment. In Indiana, you're looking at principal and interest, property taxes, homeowner's insurance, and possibly HOA fees or PMI if your down payment is under twenty percent. Let me give you a real example from my own practice. A client came to me last year wanting to buy a home in Marion County. She ran the numbers on a free online calculator and thought she could afford a forty thousand dollar higher price point than she actually could. The calculator didn't include property taxes because her search was filtered to national averages, not Indiana-specific rates. Marion County property taxes run around zero point eight two percent of assessed value, which translates to roughly three hundred thirty three dollars per month on a two hundred fifty thousand dollar home. That changed her qualifying amount significantly.
The Indiana-Specific Factors That Break Generic Calculators
Indiana has some quirks that most generic mortgage tools don't account for. Property assessment ratios differ by county. Some counties assess at one hundred percent of market value, while others use lower ratios. This affects your annual tax bill and therefore your monthly escrow payment. I learned this the hard way when a buyer in Jefferson County thought his taxes would be half what they actually ended up being. Another thing most calculators miss is Indiana's homestead exemption. If you own and occupy the home as your primary residence, you can reduce the assessed value by up to twenty five thousand dollars for school corporation taxes. That's a real savings, but it only applies if you meet the eligibility requirements. First-time homebuyers sometimes miss this entirely because the calculator doesn't ask about residency status. You also need to consider whether your property is in a flood zone. Indiana has a lot of areas along the Ohio River and various tributaries that qualify for mandatory flood insurance. This can add three to eight hundred dollars annually to your costs. A calculator that ignores flood zone status will give you a deceptively low payment estimate.
How I Run an Indiana House Payment Analysis Myself
When I help clients evaluate a home in Indiana, I don't rely on a single online calculator. I pull the actual property tax rate for the specific county, check the assessed value history over the past three years, and verify whether the home qualifies for any homestead exemptions. This usually takes about ten minutes and catches issues that a generic tool completely misses. I use a spreadsheet with separate columns for principal and interest, property taxes, insurance, PMI if applicable, and any HOA fees. Then I add a buffer for future tax increases, which in Indiana have averaged around three to five percent annually in recent years. This gives us a more realistic payment range than any single calculator output. Here's a practical tip that most people don't know about. Indiana allows property tax appeals if you think your assessed value is too high. The deadline is usually March first, and you need to file with your county auditor's office. I've seen clients reduce their annual taxes by fifteen to twenty-five percent after a successful appeal. A calculator that uses the current assessed value without considering a potential appeal will show you a higher payment than you might actually owe.
Get the Full Details
Common Pitfalls When Using a House Payment Calculator Indiana
The biggest issue I see is that people forget about PMI. If your down payment is less than twenty percent, you'll likely pay private mortgage insurance until you reach twenty percent equity. In Indiana, this typically costs around zero point five to one percent of the loan amount annually. On a two hundred thousand dollar loan, that's one thousand to two thousand dollars per year, or about eighty-three to one hundred sixty-seven dollars per month. Another pitfall is assuming the interest rate will stay constant. Most calculators show a fixed-rate scenario, but adjustable-rate mortgages are becoming more common in Indiana's current market. If you're considering an ARM, the initial rate might be lower, but it can adjust significantly after the fixed period ends. I recommend running both scenarios and comparing the long-term costs. You also need to factor in closing costs, which in Indiana average around two to five percent of the home price. These include origination fees, appraisal costs, title insurance, and recording fees. A calculator that only shows monthly payments without considering closing costs gives you an incomplete picture of your total investment.
When a Calculator Won't Help You
Sometimes a simple House Payment Calculator Indiana won't give you accurate results. If you're buying a manufactured home, the rules change significantly. Manufactured homes are often classified as personal property rather than real estate, which means different financing terms, higher interest rates, and shorter loan durations. I had a client in Allen County who thought she could get a thirty-year fixed mortgage for her manufactured home. She couldn't. The loan was fifteen years at a rate three percentage points higher than conventional mortgages. Another situation where calculators fail is new construction. Builders in Indiana often offer incentives like rate buydowns or closing cost credits, but these affect the numbers in ways that standard calculators don't capture. I recommend talking to your lender directly about these programs rather than relying on online tools. If you're buying a home in an Indiana county with unique tax structures, like those near major cities with separate school corporation rates, the calculations get more complex. Indianapolis Public Schools and other urban districts have different tax rates than suburban counties. A generic calculator that uses state averages will miss these differences.
Alternative Approaches for Indiana Homebuyers
Instead of relying solely on a House Payment Calculator Indiana, consider working with a local mortgage professional who understands the specific market conditions. They can run actual loan estimates using current rates and account for Indiana-specific factors like property tax assessments, homestead exemptions, and county variations. You can also use the Indiana Housing and Community Development Authority's resources. They offer first-time homebuyer programs with down payment assistance and favorable loan terms. These programs can significantly change your monthly payment compared to a conventional mortgage. A calculator that doesn't account for these programs will show you a higher payment than you might actually qualify for. Another option is to check with individual counties for their property tax information. Most Indiana counties publish their assessed values and tax rates online. This data can help you verify the numbers a calculator gives you and catch any discrepancies before you commit to a purchase.
The Bottom Line for Indiana Buyers
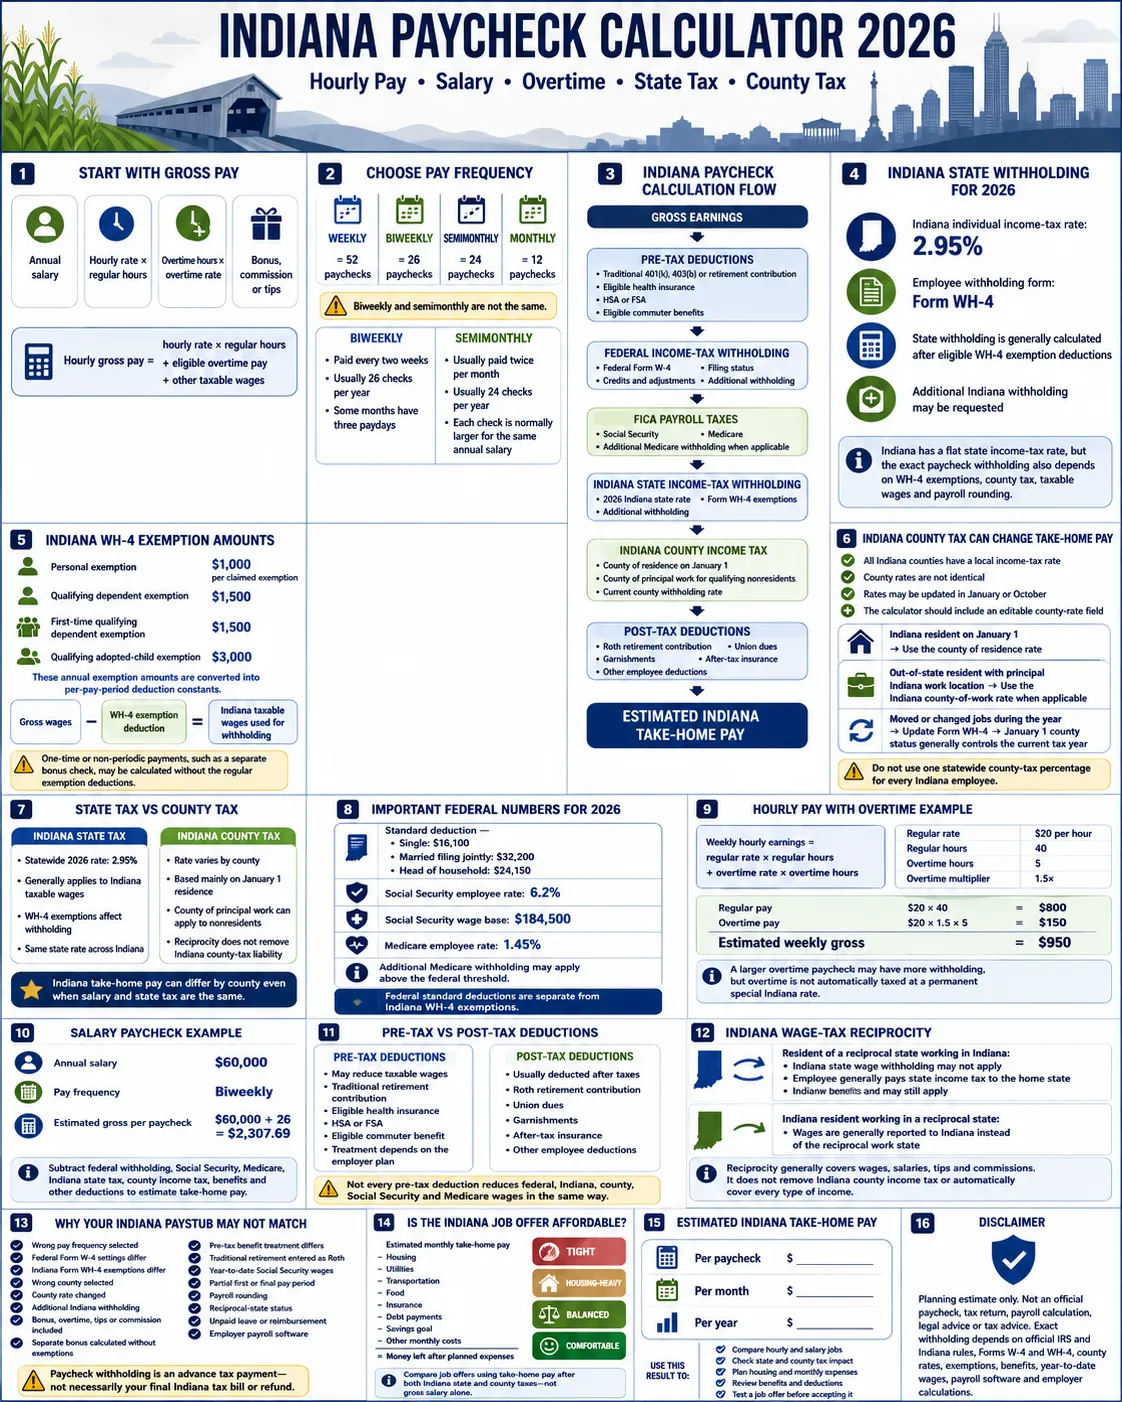
A House Payment Calculator Indiana can give you a rough estimate, but it won't replace actual due diligence. Indiana's property tax system, assessment variations, and homestead exemptions create enough complexity that a generic tool will miss important details. I recommend running the numbers through a calculator, then verifying each component with actual county data and a local lender. The process usually takes about twenty to thirty minutes total, but it can save you thousands of dollars in unexpected costs. Don't skip the verification step just because the calculator output looks appealing. Indiana markets have enough variation that what works in one county might not apply in another. If you're in a rush and need quick estimates, use multiple calculators and compare the results. Look for ones that let you input specific county tax rates rather than relying on national averages. The more detail you can add, the closer your estimate will be to the actual payment you'll owe each month.


