Why Most Free Budget Templates Fail Within Two Months
I spent roughly forty minutes last Tuesday trying to understand why someone's monthly budget kept showing a $312 surplus that didn't exist. The spreadsheet had circular references, SUMIFS formulas pointing at deleted rows, and a category labeled "Miscellaneous" that was doing far too much work. This is the problem with downloadable Household Budget Worksheet Excel Template files from random blogs. They look clean. They have color coding. They have data validation dropdowns that feel impressive when you first open them. Then you actually try to use them for three months and the formulas break, the categories don't fit your life, and you abandon it. That said, a well-structured template is genuinely useful if you build it correctly or choose one that doesn't try to solve every problem at once. Let me walk through what actually works, what doesn't, and the specific approach I ended up using after three years of rebuilding spreadsheets that fell apart.
Building a Household Budget Worksheet Excel Template That Doesn't Break
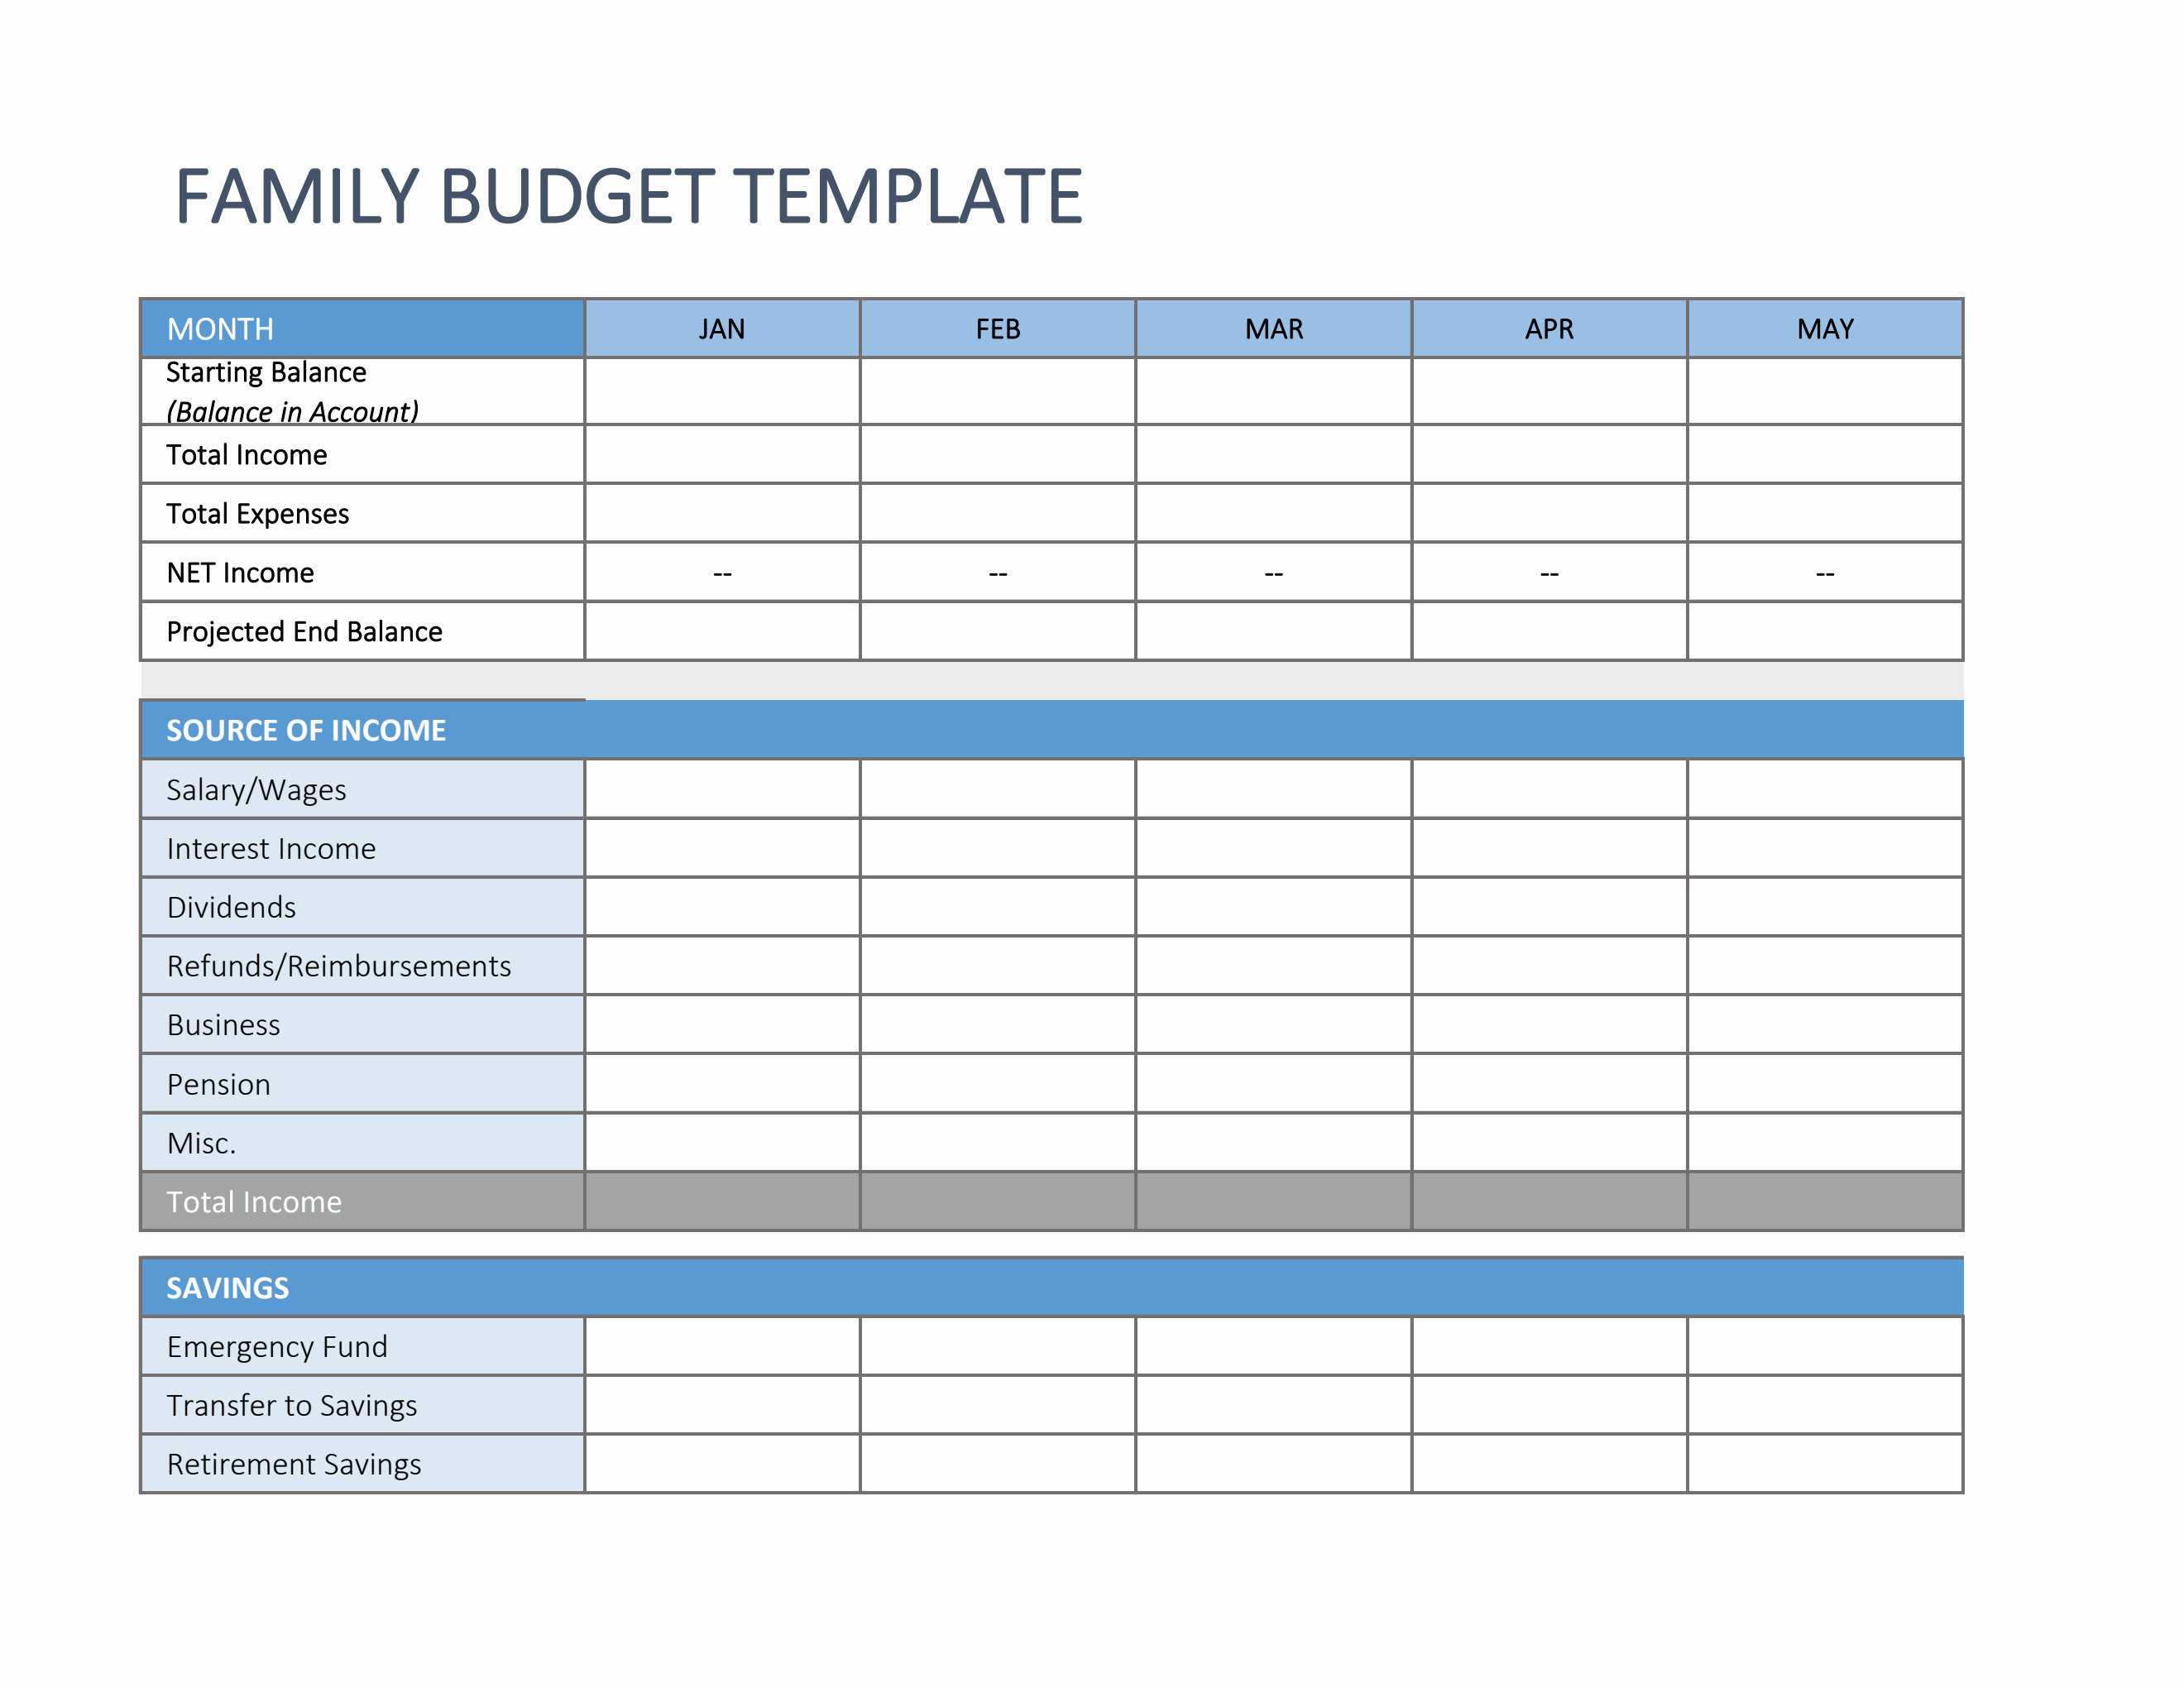
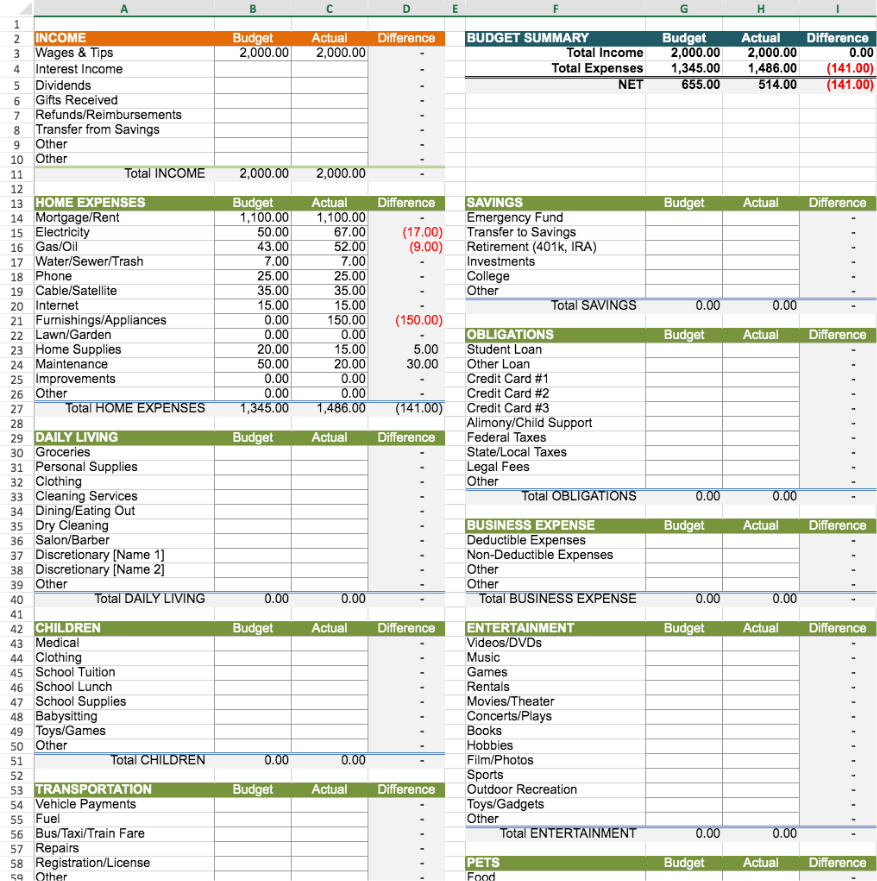
Start with the simplest possible structure. I've found that the effective limit for a personal or household budget spreadsheet is roughly seven to nine expense categories before the thing becomes unmanageable. Everything beyond that is administrative overhead, not financial planning. Your columns should be: Category, Budgeted Amount, Actual Spent, Difference, and Year-to-Date Running Total. That's it. Seven columns across twelve rows. Twelve months on the side if you want monthly granularity, or just stick to monthly with a yearly summary column. The mistake people make is adding too many subcategories. Groceries, Dining Out, Coffee Shops, Snacks, Meal Kits, Takeout. That's six categories where two would do. The cognitive load of tracking six separate lines every month means you'll stop tracking at least one of them by October. I learned this the hard way with a template that had forty-seven line items. I stopped entering data after eight months because reviewing forty-seven rows was exhausting. My actual spending patterns were perfectly captured with fourteen lines. For the formulas, keep everything as simple as possible. Use SUMIF rather than SUMIFS when you can, because SUMIF is easier to debug when something goes wrong. Put your category labels in a separate range so you can reference them cleanly. Use absolute references sparingly. The biggest source of broken templates I see is people locking cell references like $B$4 everywhere when they only need them in a couple of places.
Here's a specific edge case I ran into recently that took me a while to resolve. I was working with a template that used conditional formatting to highlight any category where spending exceeded the budget. The rule was straightforward: =Actual>Budget. But one household had a variable income structure where some months they received a bonus that they allocated entirely to a discretionary fund, and the conditional formatting was flagging that entire category red every single month even though they were under budget when you accounted for the bonus allocation. The workaround was adding a second row underneath each budget line labeled "Adjustment" with a SUMIF that pulled in any bonus allocations tied to that category, then changing the comparison formula to =Actual>(Budget-Adjustment). It added one row per category but eliminated the false alarms. It's a small detail that most templates don't account for, and it's the kind of thing that makes the difference between a spreadsheet you keep using and one you delete.
Get the Full Details
The Setup Process
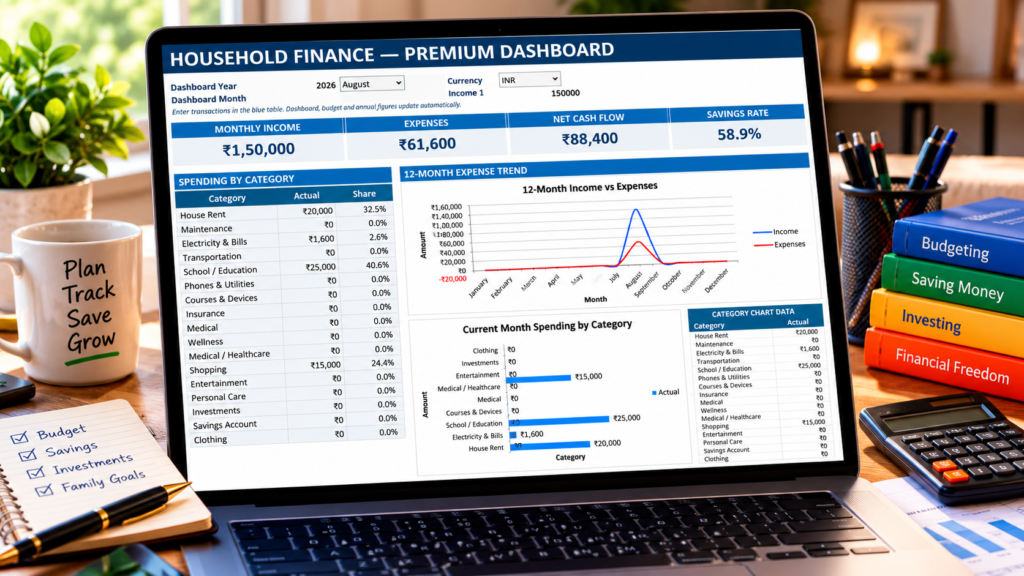
Open a blank workbook. Create a sheet called Categories. List every expense category you actually have in column A and put a budgeted monthly amount in column B. Don't guess. Look at your bank and credit card statements from the last three months, average the spending for each category, and use that as your starting point. If you don't have three months of history, use two. If you're just starting out, pull a month and plan to adjust after you've seen the next two. Create a second sheet called Transactions. Columns are Date, Category, Description, Amount, and Type. Type is either Income or Expense. This sheet does the heavy lifting. Your summary sheet pulls from it. You never manually enter numbers into the summary. If you can't trace every number back to a transaction row, your template has a structural problem. On the summary sheet, use PivotTables rather than SUMIF formulas. I know that sounds excessive for something this small, but PivotTables handle category changes without breaking, they auto-refresh when you add transactions, and they make it trivial to switch between monthly and quarterly views without rebuilding anything. The learning curve is roughly twenty minutes. The time savings over six months of use is measured in hours.
Color coding should serve a function, not an aesthetic. Red for over budget, green for under budget, gray for categories you haven't hit yet in the current month. Don't add gradient scales, data bars, or icon sets. They add processing overhead and they make the spreadsheet harder to read when printed or shared. Keep the visual language utilitarian.
Common Pitfalls and How to Avoid Them
The most common issue I see is people setting budgets that are too tight from the start. A budget of $350 on groceries when you've been spending $480 monthly will fail within three weeks. You'll either abandon the spreadsheet or start fudging numbers to make it work, which defeats the whole purpose. Set your initial budgets at your actual recent spending level, then reduce by 5 to 10 percent per month until you reach your target. It's slower but it sticks. Another problem is mixing personal and business expenses in the same sheet. I've seen it constantly. A freelance writer who tracks client supplies alongside household groceries in one template. The moment you need to separate them for tax purposes, you're rebuilding the entire structure. Keep them in separate workbooks from day one. The extra tab management is negligible compared to the pain of untangling mixed data later. Data entry inconsistency is a silent killer. One month you write "Amazon", the next "AMZN.com", the next "Online Shopping". Your PivotTable treats those as three different categories and your budget looks terrible even though you're actually on track. Standardize your category names from the start and use data validation dropdowns on the transaction sheet to prevent manual entry variations. This takes about five minutes to set up and saves hours of cleanup over a year.

The other counter-intuitive thing most people miss is that zero-based budgeting doesn't require every single dollar to be assigned before the month starts. What it actually requires is that your income minus your expenses equals zero at the end of the month, with the remainder going to savings or debt payment. If you budget $3,200 against $3,000 in income, you've got a $200 problem. If you budget $2,800 against $3,000, you've got a $200 opportunity. The framework is about intentionality, not perfection. Most templates push for perfect assignment on day one, which is why people quit. They miss one $4 coffee and the whole month feels ruined.
Household Budget Worksheet Excel Template Download and Selection
If you're looking for a starting point rather than building from scratch, there are reliable sources. Microsoft's own template gallery has a Basic Monthly Budget that's adequate for straightforward households. Google Sheets also offers a solid Budget Template that syncs across devices, which matters if you want to update transactions from your phone without opening a desktop application. For more detailed needs, personal finance professionals like Dave Ramsey's envelope system templates or the Mad Money spreadsheet from The Budget Mom work well, though both have assumptions baked in that may not match your situation. When evaluating any downloadable template, check these three things before you invest time in it: Are the formulas visible and readable, or are they hidden behind protected sheets? Can you add a new category without breaking the structure? Does it handle negative numbers (overspending) without displaying errors? If the answer to any of those is no, move to a different template. A good template should let you modify it without becoming a maintenance project.
When This Approach Won't Work
Excel templates are not the right tool for everyone. If you have irregular income with large month-to-month variation, like commission-based work or seasonal employment, the spreadsheet model starts to feel punitive because the comparison against a fixed monthly budget creates constant red flags. In those cases, a percentage-of-income model or a rolling average system works better, and those are harder to build in a standard template. You'd need a custom setup with dynamic budget formulas that adjust based on income received that month. If you have multiple earners with shared and separate accounts, the template can handle it but the data entry burden doubles and the risk of missed transactions increases significantly. Some couples find that maintaining one shared spreadsheet while each person records their own transactions leads to more conflict than the budgeting itself solves. A dedicated app with shared access might be cleaner in that scenario, even if it costs money monthly. And if your household income exceeds roughly $20,000 per month, the complexity of categorizing every transaction across multiple accounts and investment vehicles tends to exceed what a simple spreadsheet can reasonably manage. At that level, you're usually better off working with a financial planner who uses actual planning software, because the marginal benefit of tracking every coffee purchase diminishes while the time cost continues to rise.
The honest assessment is that a well-made Household Budget Worksheet Excel Template will serve most middle-income households adequately for twelve to eighteen months before either the structure becomes limiting or your financial situation changes enough that you need something different. That's not a failure. It's the normal lifecycle. The people who keep using spreadsheets successfully are the ones who revise them annually rather than treating the first version as permanent.