Building a Housing Loan Calculator Excel Tool That Actually Works
Most people building a housing loan calculator in Excel make the same basic mistake. They throw the PMT formula into a cell and call it done. The result looks right on the surface, but the moment you introduce any real-world complication — extra payments, variable rates, irregular amortization — the whole thing falls apart. I've reviewed probably two dozen versions of this across different teams and property companies. The ones that survive contact with actual underwriting data share one trait: they're built as schedules, not single-cell formulas. Here's how to do it properly.
Why a Simple PMT Formula Falls Short
The PMT function in Excel calculates a fixed monthly payment based on a constant interest rate and a fixed number of periods. For a standard 30-year mortgage at a fixed rate, it works fine. But housing loans in practice involve things like bi-weekly payments, principal-only prepayments, rate changes after an initial period, and fees that don't fit neatly into the PMT structure. When I was working on a portfolio analysis project last year, our team used a simple PMT-based Housing Loan Calculator Excel model. It returned a monthly payment of $1,847 for a $320,000 loan at 6.5% over 30 years. That number was correct. What it wasn't capturing was the fact that the borrower was making an extra $200 per month toward principal. The model showed a remaining balance of $298,000 after five years when the actual balance should have been closer to $271,000. That's a $27,000 discrepancy, and it matters when you're assessing refinancing options or doing cash flow projections. The fix is straightforward. You build an amortization schedule row by row instead of relying on a single formula output.
Setting Up the Amortization Schedule
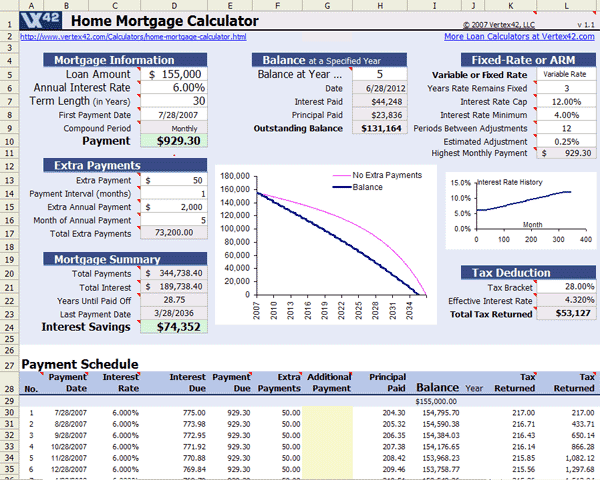
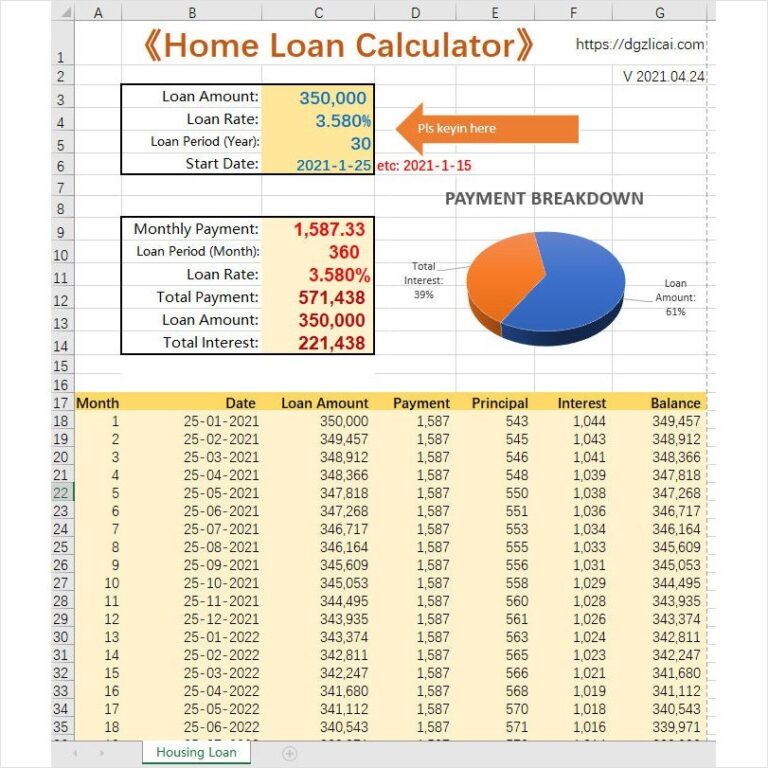
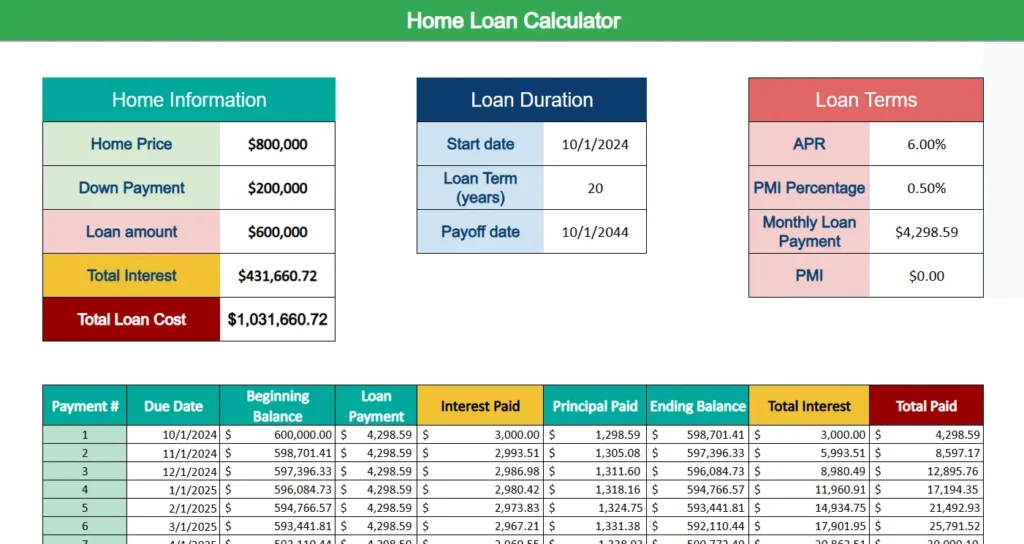
Start with your input section. Keep it clean. Principal amount, annual interest rate, loan term in years, payment frequency, and an optional column for extra payments. Use named ranges or a clearly marked input block so you're not hunting through cells later. I like to put inputs in a separate area from the schedule itself. Makes it easier to swap between scenarios without breaking references. Then build the schedule. Column A gets the payment number. Column B is the payment date — use the EDATE function to advance by the appropriate interval. Column C holds the beginning balance. Column D is the interest portion, calculated as the beginning balance multiplied by the periodic rate. Column E is the principal portion, which is the total payment minus the interest. Column F is the ending balance, beginning balance minus principal paid. Repeat until the balance hits zero or near zero. The key insight most people miss is that the periodic rate needs to match the payment frequency. If you're doing bi-weekly payments on an annual 6.5% rate, you divide by 26, not 12. If you're doing monthly, you divide by 12. Get this wrong and your entire schedule drifts. I once saw a calculator that used 6.5%/12 for a bi-weekly schedule. The borrower ended up paying about four months extra over the life of the loan because the model underestimated the principal reduction each period.
Get the Full Details
Handling Common Complications
Once the basic schedule is working, you add the complications. Extra payments go in their own column and get subtracted from the principal balance each period. Variable rates require you to track which period the rate changes and adjust the interest calculation accordingly. Some loans have points or origination fees that affect the effective yield but not the monthly payment — those belong in a separate analysis, not the payment schedule itself. Here's a specific edge case that bit me recently. A borrower had an ARM with a 5/1 structure — fixed rate for five years, then adjustable. The first five years were at 5.75%. After that, the rate adjusted to the index plus a margin, and the contract specified a 2% cap on the first adjustment. The calculator I was reviewing had hardcoded the initial rate across the entire term. When the rate adjusted to 7.25%, the monthly payment jumped from $1,743 to $2,241. The model didn't reflect that change at all. It kept showing $1,743 for years six through thirty. That's an $498-per-month error, compounding over 240 remaining payments. The fix was adding a rate adjustment column that pulled from a separate input range and recalculated the payment using PPMT and IPMT functions for the new rate, while keeping the original amortization period intact.
Adding Summary Metrics
After the schedule, add a summary section. Total interest paid over the life of the loan. Total principal paid. The actual loan payoff date if there were extra payments. Total cost including any upfront fees. These metrics give you the numbers you actually need to compare loan scenarios or explain the deal to a client. For the Housing Loan Calculator Excel, I recommend pulling the total interest from SUMIF or SUMIFS based on the interest column, rather than trying to derive it from a single formula. It's more transparent and easier to audit. When someone questions a number, you can point to the underlying schedule instead of explaining a complex nested formula.
Pitfalls to Watch For
Rounding is a silent killer in these models. Excel stores numbers with 15 digits of precision, but your payment schedule should round the interest portion to the nearest cent each period. If you don't, the final payment might be off by a few dollars, or worse, the balance might not reach zero cleanly. Use the ROUND function on each interest calculation. It adds a line of complexity but prevents the kind of error where your schedule ends with a balance of $0.03 instead of $0.00. Another common issue is the leap year problem. If your loan starts on February 29 and you're calculating monthly payments, EDATE handles it fine, but if you're doing daily interest accrual with actual/360 or actual/365 day count conventions, you need to be careful about which convention the loan documents specify. Most residential mortgages use 30/360, which avoids this entirely. Commercial loans sometimes use actual/360, and that's where things get messy. Perhaps the most important limitation to understand: an Excel amortization schedule is a static tool. It shows you what happens under the assumptions you build in. It doesn't account for tax implications, insurance escrow, PMI requirements, or the opportunity cost of extra payments. If someone is using this to make a final decision about whether to refinance or prepay, they need to run those considerations separately. The calculator gives you the payment mechanics. It doesn't give you the financial advice.

When Excel Isn't the Right Tool
There are scenarios where a Housing Loan Calculator Excel model becomes impractical. If you're analyzing a portfolio of 200+ loans with different terms, rates, and prepayment patterns, the spreadsheet gets slow and fragile. File size balloons, recalculation times stretch, and one misplaced reference can cascade through the entire model. In those cases, moving to a database-driven approach or a specialized mortgage analytics tool is worth the investment. But for individual loan analysis, scenario comparison, or client presentations, a well-built Excel schedule is fast, accessible, and flexible enough for most purposes. The core principle is simple: build the schedule row by row, round your interest calculations, handle rate changes explicitly, and don't confuse a payment calculator with a financial decision engine. Everything else is just detail.