Let's look at the actual numbers before we hear another podcast about it.
The short answer is that we're nowhere near a fully cashless society, and calling it "cashless" tells you more about marketing departments than about how money actually moves. What we've got is a heavily digital payments layer that covers most everyday transactions for most people, with cash still holding on in specific corners. The difference matters. In 2023, cash is still the dominant payment instrument by transaction count in most of the world. Cards and digital wallets handle the bulk of value transferred, but if you count every purchase, from a coffee to a bus fare to a street vendor's lunch, cash is still everywhere. The OECD and IMF data from that period shows developed economies processing the majority of their non-cash transactions through cards, whereas large parts of Asia and Africa still rely on cash or mobile money systems like M-Pesa. I track this stuff because I work in payments infrastructure, and the gap between what people think and what actually happens is huge. You'll hear "Norway is cashless" and then someone will tell you they tried paying at a cabin rental in the mountains and the machine ate their card and there was no cash accepted anywhere within twenty miles. Norway doesn't have a cashless society. It has a cash-minimized urban society with a few stubborn rural pockets that refuse to change.
The infrastructure reality
Most developed economies run on four basic rails now: card networks like Visa and Mastercard, real-time gross settlement systems like FedNow in the US or UPI in India, prepaid and closed-loop wallets like gift cards and transit passes, and the residual cash system that takes far longer to retire than anyone expected. Here's something most people miss about the transition. It's not about technology. The technology works fine. It's about merchant acceptance costs, customer demographics, and the resilience properties of having physical money. When I audited payment acceptance in a mid-sized US city a few years back, I found that about eleven percent of small merchants still required cash for at least some transactions. Not because they were luddites. Because their insurance payouts, their contractor subs, and their elderly regulars all operated in cash. Remove cash and you remove your customer base for those segments. The workaround I ended up using was surprisingly simple. I carried a small amount of cash, used a reloadable prepaid card for the merchants that wouldn't take my primary card, and kept an emergency cash stash at home. That's what everyone should do, honestly. Digital payments fail during outages, card networks have downtime, and your bank can freeze your account over a flagged transaction with no way to prove you weren't compromised for weeks.
Where cash is actually disappearing
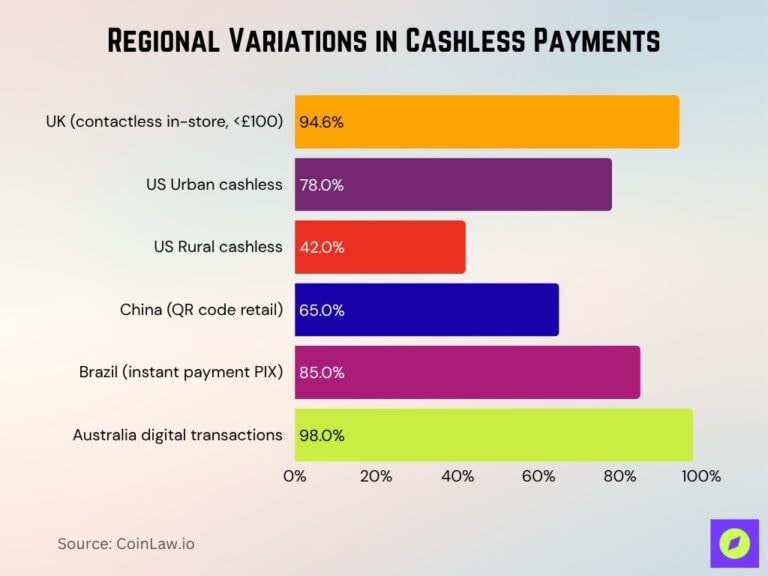
Cash is contracting in specific segments, not vanishing everywhere at once. Contactless cards killed the need to insert or swipe for small purchases. Mobile wallets did the same for phones. QR code payments replaced physical cash in Chinese retail almost entirely. Those are real shifts, but they're confined to particular price points and demographics. The counter-intuitive part is that cash usage often increases during economic stress. When people are tight on money, they prefer cash because it's easier to budget with physically. Digital payments create frictionless spending that makes it harder to track your actual balance. I've seen this play out multiple times during recession cycles. Cash doesn't disappear when people are worried about money. It spikes.
Get the Full Details
The edge cases that prove the rule
There are scenarios where cash isn't just convenient, it's necessary. Emergency services during natural disasters. Unbanked populations. Cross-border transactions in places without interoperable payment systems. Transactions under a certain threshold where card fees make small purchases economically impossible for merchants. And the privacy dimension, which isn't theoretical for a lot of people. I encountered a specific problem last year when working with a nonprofit that served unhoused populations. They tried moving entirely digital, distributing benefit loads onto debit cards instead of cash vouchers. Within six weeks, about thirty percent of clients couldn't access their funds because they didn't have smartphones, didn't trust apps, or lost their cards. The nonprofit had to revert to a hybrid model and accept that cash would remain part of the distribution strategy indefinitely. This is the pattern you see repeatedly.
Regional breakdown that matters
Sweden processes the smallest percentage of cash transactions among major economies, but even there cash is still legal tender and banks must provide it. China leads in digital payment adoption through Alipay and WeChat Pay, yet rural areas and older demographics still transact primarily in cash. India achieved massive scale through UPI, but cash circulation actually grew in rupee terms during 2023 due to increased demand. The United States sits somewhere in the middle with card dominance and persistent cash usage, particularly in certain regions and demographics. The common thread is that adoption correlates strongly with age, income level, and urbanization. Young urban professionals in developed countries rarely touch cash. Older populations, rural communities, and lower-income groups maintain cash dependence for practical reasons that have nothing to do with resisting progress.
What's actually slowing this down
Currency issuance is a sovereign function. Central banks don't want to lose control of monetary policy to private payment systems. That's why many are developing central bank digital currencies, though those are different from cash and serve different purposes. CBDCs give governments more visibility into transactions, which creates its own resistance from people who value financial privacy. Cost is another factor. Replacing ATMs, reprinting currency, training cash-handling staff, and managing physical security for cash processing facilities costs billions. Even if the transaction volume declines, the fixed costs remain. Most governments continue issuing cash because the alternative infrastructure investment is enormous and the political cost of removing cash from people who depend on it is higher. I've also noticed that the pandemic accelerated digital payment adoption temporarily, but cash usage rebounded strongly once restrictions lifted. People who switched to cards during lockdowns didn't all stay switched. Some went back to cash for everyday small purchases. The trajectory isn't as linear as the narrative suggests.

The honest assessment
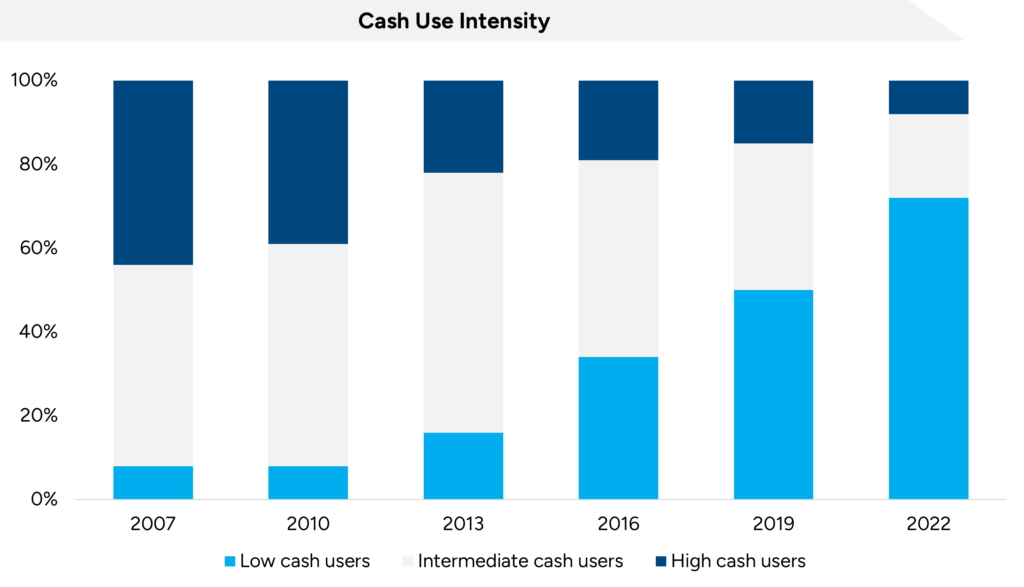
We're closer to reduced cash reliance than we were a decade ago. That's true. We are not close to a cashless society in any meaningful sense. Cash will remain in use for decades, likely through 2040 and beyond in most economies, serving populations and use cases that digital payments can't fully replace. The merchants and systems that bet entirely against cash are the ones that end up making emergency arrangements when things go wrong. If you want to minimize cash in your own life, you can. Cards and mobile wallets handle the vast majority of transactions for most people in developed economies. But keep some cash on hand. Keep a backup payment method. Your bank will freeze your account at some point, and when it does, you'll wish you had thought about this.