The Actual Method for Stripping Inflation Out of GDP Numbers
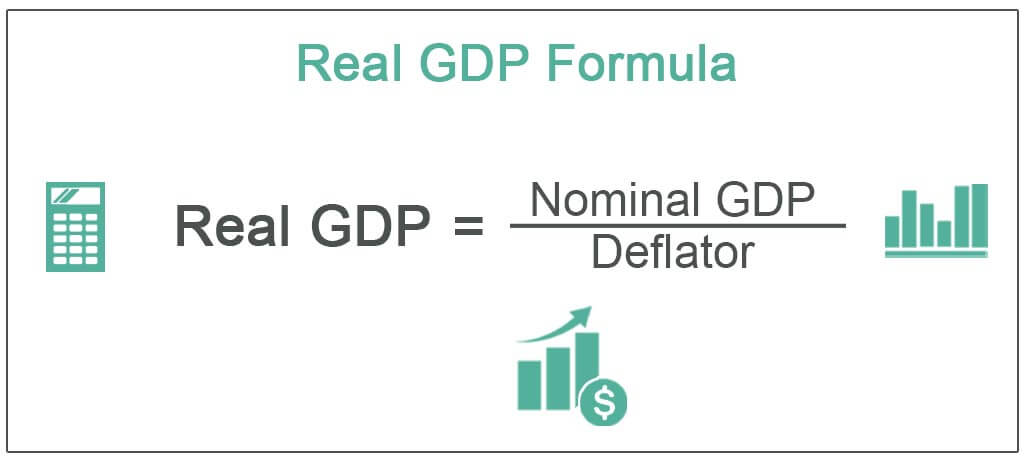
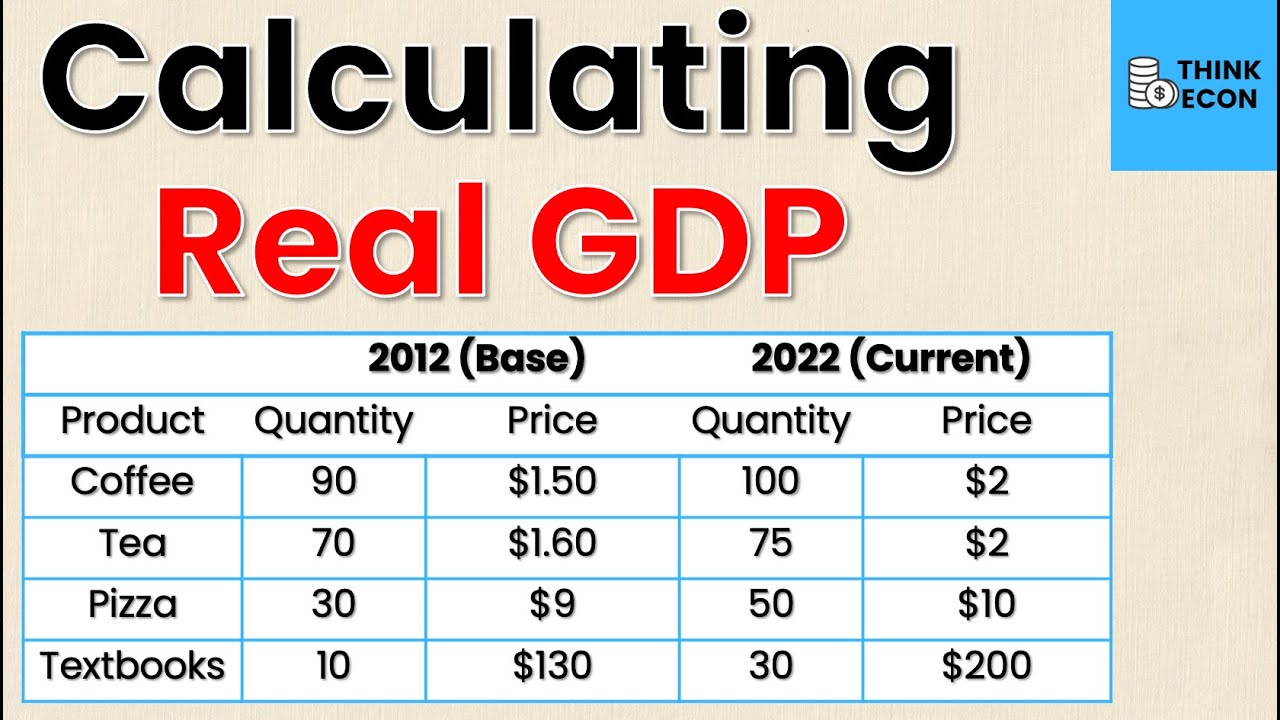
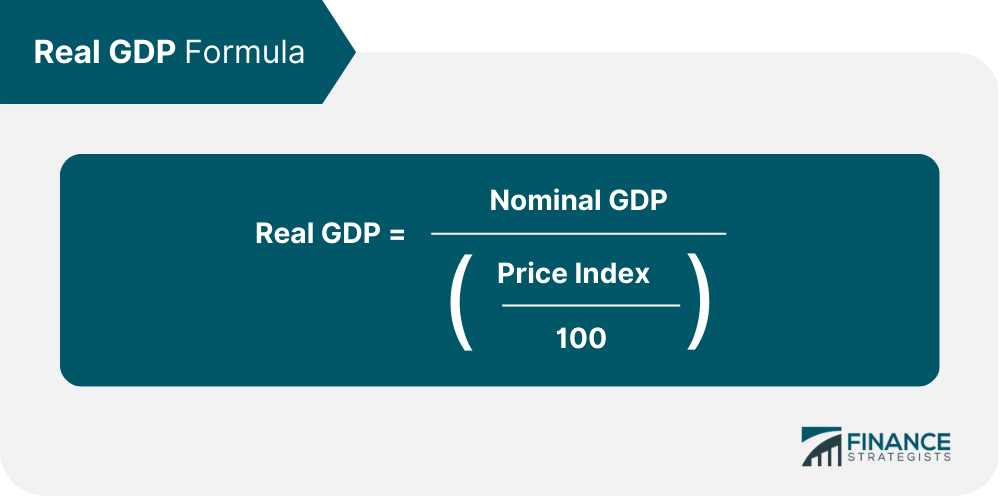
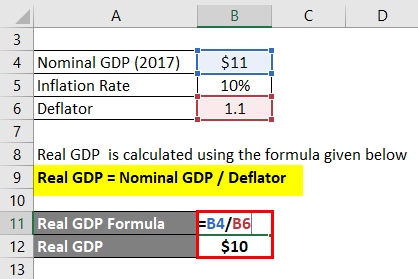
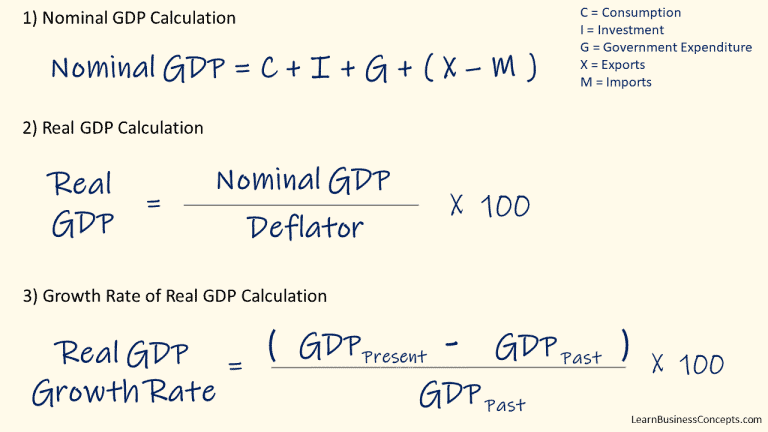
The core calculation is straightforward. You divide nominal GDP by the GDP deflator and multiply by 100. That's it. Nominal GDP is just total output measured at current prices—no adjustment for inflation. The deflator acts as a price conversion factor that lets you compare output across years without the noise of changing price levels. The formula looks like this: Real GDP equals nominal GDP divided by the GDP deflator, times 100. The deflator itself is calculated by taking nominal GDP divided by real GDP, times 100. These two equations are inverses of each other, so you can work backwards from either one depending on which numbers you actually have available. Here is a concrete example that should make it stick. Say an economy produces only three things: cars, haircuts, and coffee. In 2022, they produce 10 cars at $20,000 each, 100 haircuts at $30 each, and 1,000 coffees at $3 each. Nominal GDP for 2022 comes to $200,000 plus $3,000 plus $3,000, which is $206,000. Now in 2023, production stays exactly the same—still 10 cars, 100 haircuts, 1,000 coffees—but prices shift. Cars go to $21,000, haircuts to $32, and coffee to $3.20. Nominal GDP for 2023 is $210,000 plus $3,200 plus $3,200, totaling $216,400. That looks like a big jump, but let's strip out the price change.
Since 2022 is the base year, real GDP for both years equals the 2022 quantities valued at 2022 prices. So real GDP for 2022 is $206,000 and real GDP for 2023 is also $206,000 because quantities didn't change at all. The GDP deflator for 2023 is 216,400 divided by 206,000 times 100, which gives you 105.05. That tells you prices rose roughly 5% between those two years. This economy produced nothing more in real terms, even though the dollar figures look bigger. People who only look at nominal GDP would have concluded the economy grew by about 5%, which is wrong. It didn't grow at all. The trick most people miss is which deflator you should use. The GDP deflator covers every good and service produced domestically, including capital equipment, government purchases, and exports. The CPI only tracks consumer goods and is based on a fixed basket that doesn't update fast enough. When you're comparing real GDP across decades, these two measures will diverge significantly. The CPI tends to overstate inflation because it doesn't account for substitution effects—the fact that consumers switch to cheaper alternatives when prices shift. The GDP deflator is theoretically cleaner for this purpose, but it lags behind current data by a few months because it requires compiling detailed price indices across all sectors. I ran into a specific problem last year working with state-level economic data. A midwestern state reported that its manufacturing sector had grown 4% in real terms between 2019 and 2022. But when I pulled the BEA's chain-type quantity indexes and recalculated using current-dollar values alongside the implicit price indexes, the real growth was closer to 1.3%. The state had been using a simplified CPI-based adjustment rather than the chain-weighted deflator that the federal government uses. The gap widened over time because the CPI basket doesn't capture the specific industrial goods that dominate that state's economy. Switching to the proper chain-type price index brought the numbers in line with national benchmarks. It took about an hour to redo the calculations once I identified the discrepancy, but catching it before publication saved a serious credibility problem.
Another thing that trips people up is the relationship between base years and comparability. When the Bureau of Economic Analysis switched from fixed-base-year calculations to chain-weighted methods in 1996, real GDP estimates changed retroactively across all prior years. You cannot directly compare real GDP figures expressed in 1992 dollars with those expressed in 2017 dollars without converting them. The chain-weighted approach updates the relative prices used in the calculation every year, which reduces substitution bias. It also means the reference year shifts regularly, which is why BEA publishes data in constant dollars relative to a specific anchor year but reminds you that the underlying methodology chains from year to year. If you are doing this manually and don't have access to BEA tables, you can approximate the deflator by using the price index for the components you care about. But that approximation breaks down quickly. The BEA releases both current-dollar and constant-dollar GDP data quarterly, along with the implicit price deflator for personal consumption expenditures and fixed investment. Downloading the raw data from FRED and running the division yourself is faster than trying to reconstruct anything. The chain-type real GDP series is already calculated for you, but understanding the mechanics behind it matters when someone asks why two sources show different growth rates for the same period. The main limitation of real GDP as a measure is that it captures output volume but not quality changes, environmental costs, or unpaid household production. It also doesn't distinguish between production that improves welfare and production that compensates for damage—like spending on disaster cleanup counting as positive GDP. None of that is a flaw in the calculation itself, but it is a flaw in treating real GDP as a complete measure of economic well-being. If you need a broader picture, pair it with measures like the Genuine Progress Indicator or simply supplement it with productivity data and income distribution statistics.
Get the Full Details

For the actual calculation steps, grab the nominal GDP number and the GDP deflator from the BEA table 1.1.6 or the chain-type real GDP series from table 1.1.5. Divide nominal by the deflator and multiply by 100. If the deflator isn't directly available for your time frame, back it out from the ratio of nominal to real GDP that the BEA publishes. Keep the base year consistent across all comparisons. And if you are working with subnational data, verify which price index the source agency used before trusting the real growth figures they report.