The paperwork is worse than you think
Most people launch a nonprofit because they want to do good. That is noble and also completely irrelevant to the filing process. The IRS does not care about your mission statement's passion. It cares about whether you can fill out 990-N forms without accidentally disqualifying yourself from tax exemption. The gap between intention and legal reality is where most organizations die before they ever open their doors. I spent three weeks in 2019 helping a local food rescue group incorporate. They had a functioning distribution network already running out of a church parking lot. They had donors willing to write checks. What they did not have was a clear understanding that "nonprofit" is not a business model — it is a tax status you apply for after you have already formed a legal entity. They had operated for eight months before filing Articles of Incorporation. Eight months of bank accounts held in a personal name. Eight months of every donation being treated as a gift rather than revenue for a recognized 501(c)(3). That is a compliance nightmare that took another four months and two amendment filings to clean up.
How Do You Start A Nonprofit Business
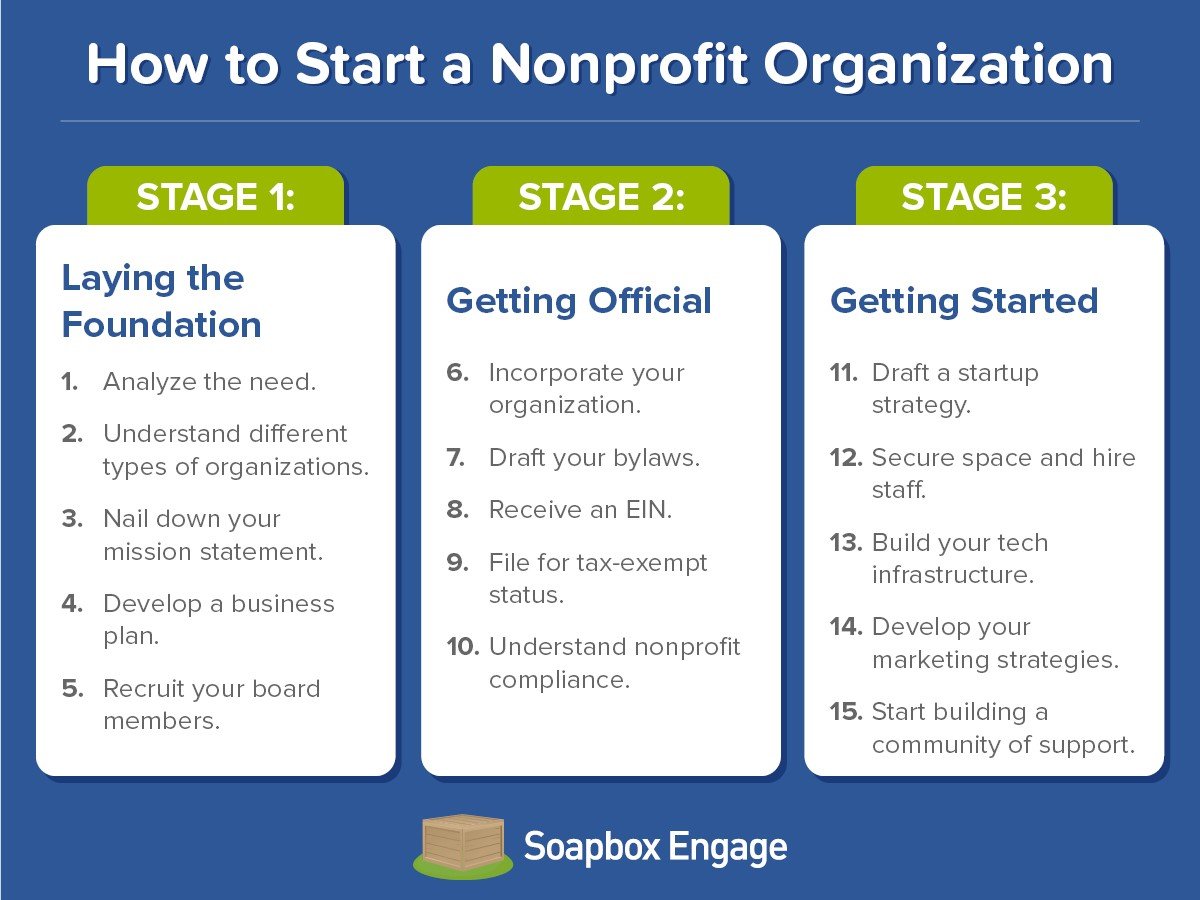
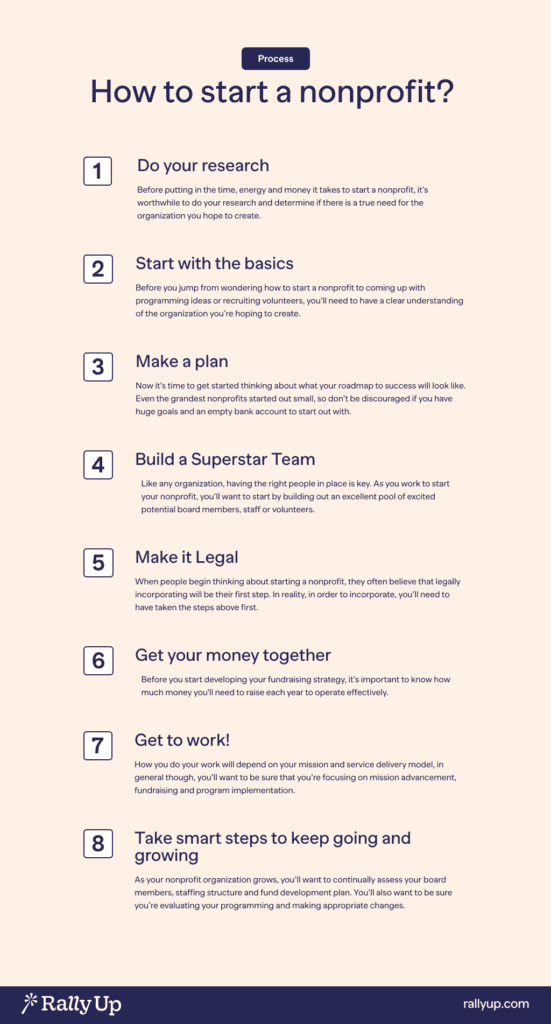
The first step is not writing a grant proposal or renting office space. It is choosing a state and filing Articles of Incorporation with that state's Secretary of State office. This creates your legal entity. Cost ranges from $50 to $200 depending on jurisdiction. Processing time is anywhere from same-day to six weeks, though expedited filing usually exists for an additional fee. Most people pick their home state. If you plan to operate across multiple states or raise significant funds, consulting a attorney about domestication versus registration in additional states matters more than you would expect. Once the state recognizes your corporation, you need a board of directors. Minimum is three people in most states, though some allow two. This board meets at least once per year. Not as a formality. Actually meeting, taking minutes, and filing those minutes internally. I have seen nonprofit boards that treated annual meetings like Christmas parties — social gatherings with no recorded business conducted. When a donor or grantor asked for proof of governance, those organizations could not produce anything. Grant applications increasingly require evidence of active board oversight. Missing it will cost you funding opportunities. After incorporation comes the Employer Identification Number from the IRS. This is free, takes about ten minutes online, and is something you need before you can open a bank account. Do not skip this. I watched a small environmental nonprofit try to open a checking account with just their state incorporation papers. The bank rejected it twice. The owner was frustrated. The process took an extra week. It is not complicated but it is a hard stop if you omit it.
The 501(c)(3) application itself is Form 1023 or the shorter Form 1023-EZ depending on your projected annual revenue. Form 1023-EZ is available if you expect to bring in less than $50,000 annually for the first three years and have assets under $250,000. Processing times for EZ have climbed to roughly three to five months as of 2025. Standard Form 1023 takes longer — often six to eight months. The application fee is $275 for EZ and $600 for the full form. You get a determination letter when approved, which is the document you will need to show donors, grantees, and vendors that your organization qualifies for tax-exempt status. Without that letter, contributions you receive are not tax-deductible for the donors, which significantly reduces your fundraising ability. State-level registration is another requirement most people forget. You generally need to register with your state's charity regulator before soliciting donations there. Some states require annual reports and financial statements filed separately from the federal side. California's annual Statement of Information, New York's Charities Registration Bureau filings, Texas's casual solicitation rules — each state has its own quirks. A nonprofit operating in five states might face five different annual compliance calendars. Tracking these manually usually fails. I use a simple shared spreadsheet with color-coded due dates and set calendar reminders ninety days before each deadline. This cut our missed filing incidents from once per year to zero over three years. Bank accounts should be opened in the organization's name using your EIN and determination letter. Commingling personal and organizational funds is the fastest way to pierce the corporate veil and potentially trigger personal liability. I had a client who paid a vendor from his personal account because the nonprofit account had a hold. The vendor sued when the payment bounced three weeks later. The court found him personally liable because the accounts were not clearly separated. That is a fifty-thousand-dollar lesson that sounds extreme but happens more often than you would believe.
Get the Full Details
What nobody tells you about running a nonprofit
Being tax-exempt does not mean you are free from taxes. Unrelated business income — revenue from activities not substantially related to your mission — is taxable. A museum that sells merchandise in its gift shop? That is unrelated business income if the merchandise is not educational in nature. A religious organization running a cafeteria open to the public? Potentially taxable. The IRS tracks this through Form 990-T. If your unrelated business income exceeds $1,000 in a year, you must file that form. Many small nonprofits ignore this until an audit catches them. Another counter-intuitive reality: nonprofits can fail at fundraising just as easily as for-profit companies fail at sales. The difference is that nonprofit failure looks like an empty mailbox instead of an empty bank account, and the emotional impact on the founder is worse. I worked with a literacy nonprofit that had a compelling program and passionate staff. They raised $12,000 in their first year. Their operating costs were $48,000. They closed within eighteen months. The problem was not their mission. It was that they treated fundraising as an afterthought rather than a core operational function. Revenue generation requires the same discipline as any business. The tools differ — grants, individual donors, events, corporate partnerships — but the principle is identical: you need a pipeline. Payroll for nonprofit employees is another area where people get tripped up. Even if you pay yourself a salary, you still need to handle payroll taxes, W-2s, and potentially state unemployment insurance. Using a payroll service like Gusto or QuickBooks Payroll costs about $40 to $100 per month and eliminates most of the compliance risk. Doing payroll yourself saves money but introduces error. A missed quarterly withholding can trigger penalties that dwarf the cost of the service.
The annual reporting burden
Every year, regardless of revenue size, you must file Form 990 with the IRS. Organizations with gross receipts under $50,000 file the 990-N e-Postcard, which is five fields and two minutes. Between $50,000 and $200,000, you file Form 990-EZ. Above that, the full Form 990. Failure to file for three consecutive years results in automatic revocation of your 501(c)(3) status. I have seen this happen to organizations that simply forgot. The IRS sends notice, but if you are not actively monitoring mail or your account, you miss it. Setting an annual reminder on January 1st to begin preparation gives you the full year. The deadline is the 15th day of the 5th month after your fiscal year ends, which for calendar-year nonprofits is May 15th. The determination letter you receive from the IRS is not permanent protection. Changes to your purpose, substantial changes to your operations, or acquiring a for-profit subsidiary without proper structuring can all jeopardize your status. If your board ever votes to change your mission significantly, consult a nonprofit attorney before implementing. The cost of advice is negligible compared to the cost of losing exemption and having to reapply, which resets your donor deductibility clock and requires another determination letter process. Insurance is another practical necessity. General liability, directors and officers coverage, and possibly cyber liability if you handle donor data. A single lawsuit from a volunteer injury or a data breach can wipe out a small nonprofit's reserves. Annual premiums for basic coverage run $1,000 to $3,000 for a small organization. Skipping insurance to save money is a gamble most organizations cannot afford to win.