What a Business Partnership Actually Is
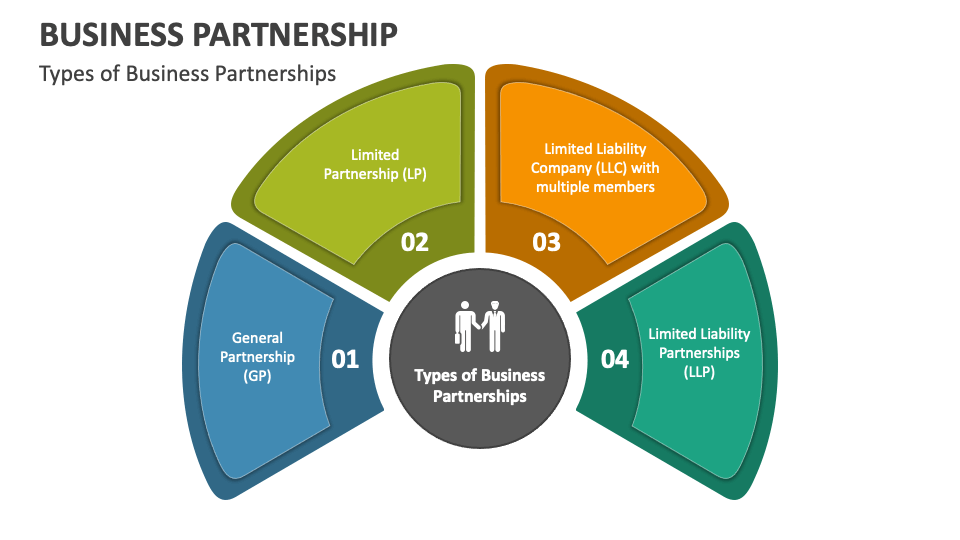
A business partnership is a legal arrangement where two or more people share ownership of a company and split responsibilities, profits, and losses. It sounds straightforward, but the devil is in the documentation. Most people skip that part and just shake hands, which tends to end badly. The mechanics are relatively simple on paper. Partners contribute capital, labor, or both to the enterprise. Profits and losses flow through to individual tax returns rather than being taxed at the business level. That pass-through treatment is one of the main reasons people choose this structure instead of incorporating. You file a Form 1065, issue Schedule K-1s to each partner, and everyone reports their share on their personal return. The IRS gets its information, but the entity itself doesn't pay income tax. There are different flavors of partnership though, and picking the wrong one can cost you dearly. A general partnership means every partner has unlimited personal liability for the business's debts. If your partner signs a lease or takes on a loan, you're on the hook too. A limited partnership adds LPs who have liability capped at their investment but can't participate in management. A limited liability partnership, or LLP, shields partners from each other's malpractice and some liabilities but rules vary significantly by state. California, for instance, charges an $800 annual franchise tax even if you make zero revenue. Texas doesn't have that same hit. Know what jurisdiction you're operating under before you file anything.
I learned this the hard way back in 2019. I was in a three-way partnership on a small consulting operation. We had a handshake agreement about profit splits and decision-making authority. Nothing written down. One partner started bringing in subcontractors without consulting the rest of us and charging those costs against the partnership's operating account. We didn't find out until tax season when the K-1 showed significantly less profit than we'd all been expecting. By then he'd also taken on a vendor contract in the partnership's name that ballooned into a $40,000 liability. Since it was a general partnership, that debt landed on all of us equally regardless of who approved it. We ended up splitting the legal bill to get him buyout terms sorted out, which ran another $12,000 between the three of us. All because we never wrote an operating agreement.
The Partnership Agreement You Actually Need
Before you incorporate or file any paperwork, you should have a written partnership agreement. This is non-negotiable and most people treat it like paperwork for a wedding rehearsal nobody attends. A solid agreement covers profit and loss allocation, voting thresholds, admission and exit of new partners, dispute resolution, buy-sell provisions, and what happens if someone dies or becomes disabled. Without an exit clause, you could end up locked into a partnership with someone who wants out or can't contribute anymore and has no mechanism to leave cleanly. The buy-sell provision is especially important. It should specify how a departing partner's interest gets valued. Fixed price, formula-based, or appraisal-driven methods each have tradeoffs. A fixed price set at the beginning will be wildly inaccurate five years later. A formula using EBITDA multiples works better but requires clear accounting. I've seen partnerships use a simple agreed-upon formula tied to a percentage of annual revenue, which at least gives a baseline number without needing a full forensic audit every time someone wants out.
Get the Full Details
Tax Implications and Compliance
Partnerships file informational returns but don't pay entity-level tax in most cases. That's the main advantage. However, there are nuances that catch people off guard. Self-employment tax applies to general partners on their full distributive share of income, not just what they withdraw. Limited partners generally don't pay SE tax on their share unless they receive guaranteed payments. Guaranteed payments themselves are deductible to the partnership and taxable as ordinary income to the recipient, similar to a salary but without payroll tax withholding. You also need to track partner basis carefully. Your basis starts with your capital contribution plus your share of partnership liabilities and increases with income allocations and decreases with distributions and losses. If you distribute more than your basis, you've got a capital gain. I worked with a partner who took a distribution in year two that exceeded his basis because the partnership had taken depreciation deductions on equipment that reduced his taxable share. He owed capital gains tax on top of having already paid self-employment tax on income he'd never actually received in cash. The partnership should have flagged that he was running close to his basis limit before issuing the distribution.
Liability and Risk Management
Unlimited liability in a general partnership is the biggest structural weakness. Creditors can go after personal assets, not just partnership property. A joint venture with a bank or a landlord almost always requires personal guarantees from general partners anyway, so the protection is more theoretical than real in many commercial contexts. Forming an LLP or LP shifts some of that exposure but introduces its own complications around management rights and state-specific compliance. The realistic approach is to carry adequate insurance and keep partnership affairs documented. General liability insurance, professional liability if applicable, and key person coverage can mitigate some risks. But insurance doesn't prevent disputes between partners, and it definitely doesn't cover fraud or breach of fiduciary duty. Those are legal matters, not insurance matters. Partners also owe each other fiduciary duties, primarily loyalty and care. That means no competing business interests, no self-dealing without disclosure, and no misappropriation of partnership opportunities. Breaching those duties gives other partners grounds for litigation and potentially damages. I've seen a partner quietly redirect client work to a side LLC while still drawing from the partnership. When the other partners discovered it, the fiduciary breach claim was straightforward, but recovering the diverted revenue took two years and about $30,000 in legal fees. The partnership was technically solvent but the cash flow damage from the distraction was the real cost.
When a Partnership Makes Sense and When It Doesn't
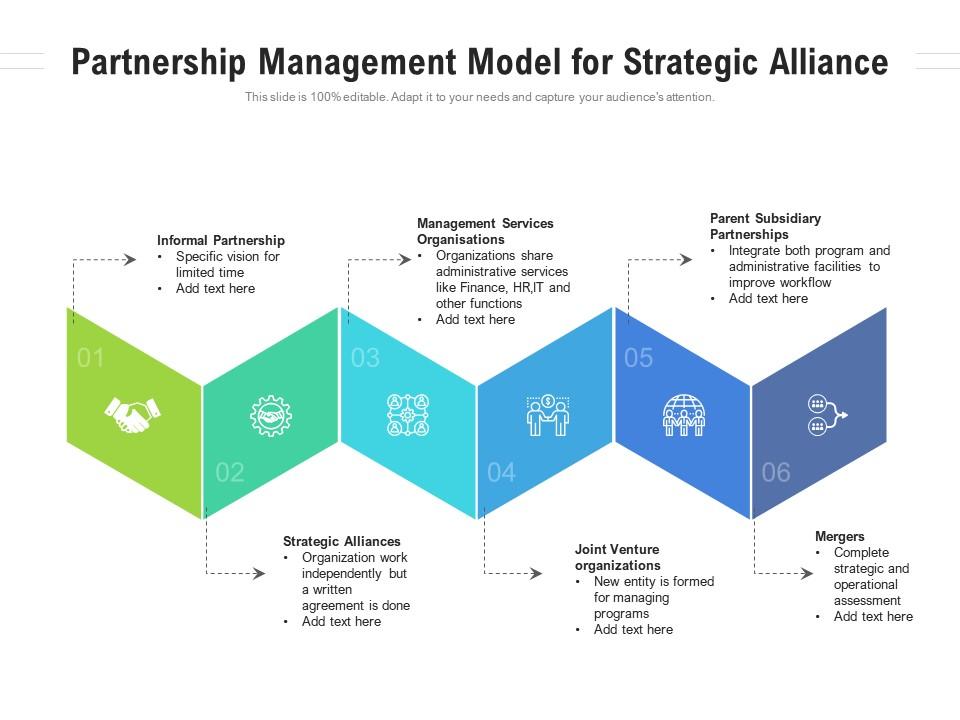
Partnerships work well for professional services firms, small manufacturing operations, and ventures where the owners want pass-through taxation and flexible profit sharing. They're less ideal when you need to raise capital from outside investors, when liability exposure is high, or when the partners have fundamentally different risk tolerances. Venture-backed startups rarely stay partnerships for long precisely because of the liability and fundraising limitations. There's also the issue of continuity. A partnership dissolves on the withdrawal or death of a partner unless the agreement says otherwise. An LLC or corporation doesn't have that vulnerability. If your partnership agreement doesn't address succession, you're looking at a messy dissolution process every time someone leaves or dies, which is not a great foundation for a business that's supposed to last. The bottom line is that a partnership is a tool, not a default setting. It has real tax advantages and structural simplicity, but it also has real liability exposure and governance risks that only a well-drafted agreement can mitigate. If you're considering one, spend the money on a lawyer who actually understands partnership law rather than downloading a template from the internet. The $2,000 to $4,000 you'll spend on a proper agreement saves far more than that in the inevitable disputes that follow when nothing is written down.