Business Credit Runs on Three Things: Paying Bills, Not Overextending, and Waiting
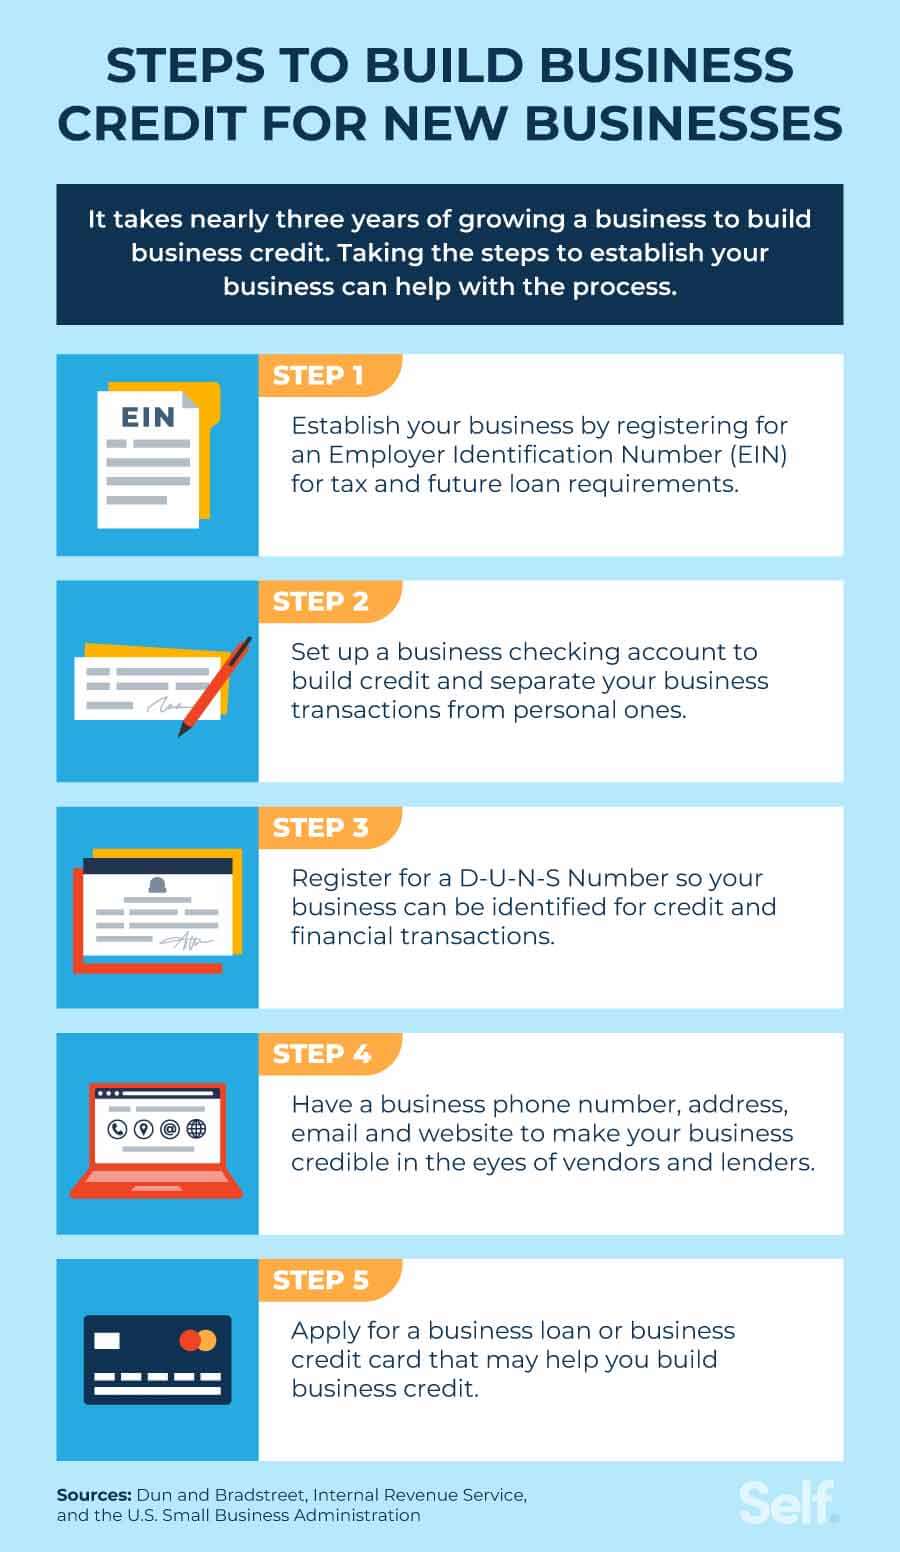
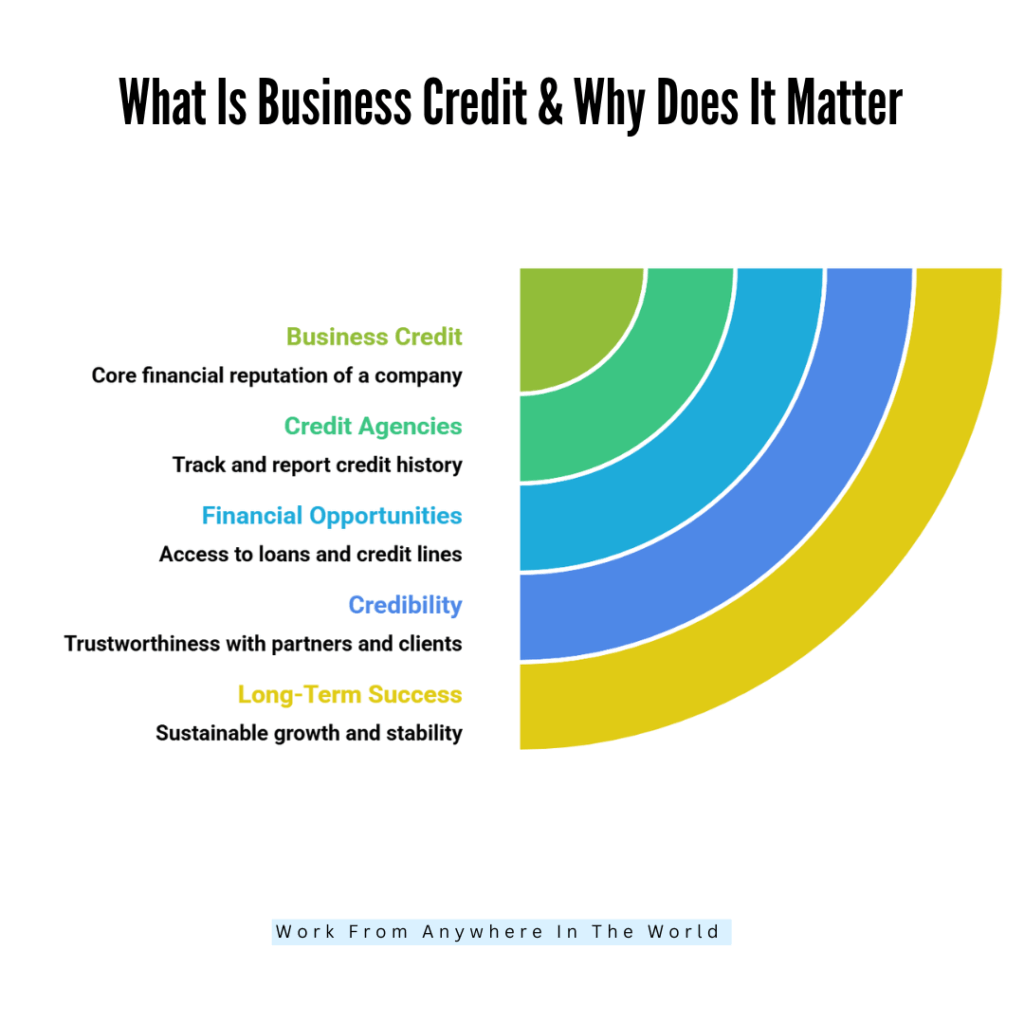
I spent six years watching small contractors tank their credit lines because they treated business credit like a personal card with a different name. The core mistake is assuming a business entity can borrow immediately upon formation. It cannot. Lenders need to see that the business actually exists as a separate financial actor before they will touch it. That separation is what makes the entire system interesting and annoying at the same time. Business credit is built when a company establishes a track record of repaying obligations on time, using trade credit accounts, line of credit products, and term loans reported to commercial credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Small Business. Each trade line becomes a data point. Payment history carries the most weight, usually around 35 percent of the score, followed by credit utilization, length of credit history, and public records like liens or judgments. The structure looks clean on paper but the reality is messier. A brand-new LLC with an EIN shows up as a credit blank slate. You need a D&B D-U-N-S number before most lenders will even attempt a hard pull. Getting that D-U-N-S number takes three to five business days if the application goes smoothly, longer if the address on file does not match the IRS record exactly. I learned that the hard way when my first client was rejected from a Revolut Business account because the state filing address had a Suite 4 and the D&B file listed just the street number without the suite. Took eleven days to get it corrected. Eleven days where the whole pipeline sat idle.
Building It From Scratch
Start with a clean business entity. The paperwork has to be current — articles of organization filed, annual reports paid, registered agent in place. Lenders cross-reference state database information against the credit file. If the files do not align, the application either gets delayed or denied outright. This is not theoretical. I had a food truck operator whose credit file showed the business address as a residential home because the Secretary of State office had recorded it that way during formation. The lender flagged it as a red flag, required a utility bill proving commercial presence, and added forty-eight hours to processing. Open a Net-30 trade account first. Suppliers like Uline, Grainger, Quill, and many wholesale distributors offer Net-30 terms with no personal guarantee for a newly formed business. These accounts report to the commercial bureaus. The strategy is straightforward: make purchases you would have made anyway, pay the invoice before the due date, and let the positive payment history accumulate. Net-30 accounts build credit history slowly. Expect three to six months of consistent on-time payments before a meaningful score improvement shows up across the major bureaus. After you have three or four active Net-30 accounts reporting, apply for a small business credit card with a low limit. Capital One Business Platinum, RBC Bank Business Edge, or a local credit union card work fine. Do not max it. Keep utilization below thirty percent, ideally under fifteen percent. Utilization spikes cause the biggest score drops, not missed payments. A 98 percent utilization month can knock twenty to forty points off a Dun & Bradstreet PAYDEX score depending on the rest of the profile.
Score Interpretation and What Matters Most
Commercial scores differ from personal ones, and people keep confusing them. PAYDEX ranges from zero to one hundred. Eighty or above means you pay on or before terms. Sixty to seventy-nine suggests late payments. Below sixty is a warning signal. Dun & Bradstreet also uses an Risk Indicator from one to five, with one being lowest risk. Experian offers a Business Credit Score from zero to one hundred, and Equifax has a similar range. Each bureau weighs data differently, so your scores will vary across them. They rarely match perfectly. The counter-intuitive part: lenders do not care equally about all three bureaus. Industry matters. A manufacturer applying for equipment financing with Dun & Bradstreet data gets weighted differently than a restaurant looking at a line of credit through Experian Business. Niche lenders pull from the bureau that has the deepest file for your sector. If you are in construction, expect Dun & Bradstreet to dominate your profile because trade suppliers have reported there for decades. If you are a service business with mostly card-based revenue, Experian may have more complete payment data.
Get the Full Details
Trade Lines and Reporting Nuances
Not every vendor reports to commercial bureaus. Some do, some do not, and some only report negative data. This gap is why the early Net-30 strategy matters. Companies that report positive payment history build your profile faster. Uline, Quill, Summa, Wayfair Business, and certain fuel cards with reporting are reliable choices. Vendors like Amazon Business or Shopify POS accounts generally do not report to Dun & Bradstreet or the other commercial bureaus in a way that helps credit building. Do not waste time opening accounts that do not report. A detail most guides miss: payment term type affects scoring. Net-30 and Net-60 both count, but vendors offering Net-10 or immediate-pay accounts with reporting can inflate your average account age while still providing positive data. It is a legitimate strategy, not a loophole. Just be honest about repayment ability. Paying a Net-60 account on day sixty-two triggers the same negative events as a late personal card payment.
The Personal Guarantee Problem
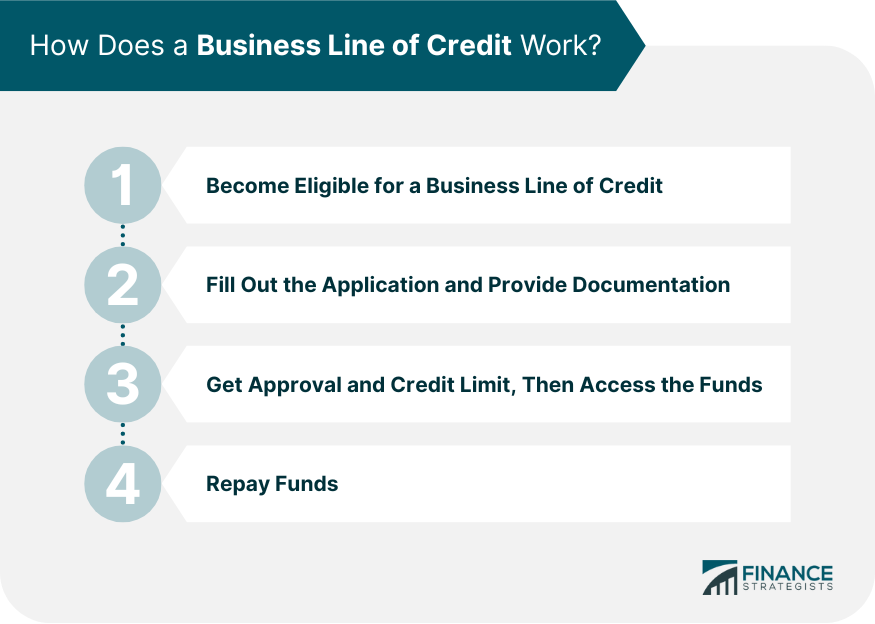
Most business credit products for small companies require a personal guarantee. Until revenue and cash flow reach a threshold, lenders want skin in the game. This means business credit events can affect personal credit if things go wrong. The separation between business and personal liability is thin at the small-business level. I worked with a landscaping company owner who thought establishing a separate credit profile would shield his personal assets from a defaulted equipment lease. It did not. The personal guarantee on that lease was explicit, and when the business could not cover the payment, the collection went after him personally. The credit file separation was real but the liability separation was not. Building toward unsecured business credit without a personal guarantee is the long-term goal. It usually requires two to three years of clean payment history, positive cash flow statements, and sometimes a minimum annual revenue threshold that varies by lender. Some lenders drop the personal guarantee at three hundred thousand in annual revenue. Others want five hundred thousand. Some never will for a first credit line. The timeline is unpredictable because each institution has its own underwriting model.
Common Pitfalls That Sink Profiles
Dormant accounts hurt more than people expect. Closing an old trade line removes positive history and reduces total available credit, which raises utilization ratios on remaining accounts. If a Net-30 account is inactive for twelve to eighteen months, some bureaus treat it as closed, which can drop the score by ten to twenty points depending on the rest of the file. Mismatched business information causes repeated issues. Changing the business address, phone number, or legal name without updating the credit file creates data fragmentation. Two files for the same company under slightly different names looks like a fresh entity to an underwriter. I once spent three hours reconciling a client's duplicate Dun & Bradstreet file caused by a street name change from "Street" to "St." in the Secretary of State records. The duplicate split the payment history between two DUNS numbers, effectively erasing half the track record for scoring purposes. Judgments and liens are profile destroyers. A single tax lien can wipe out a strong PAYDEX score and keep the risk indicator elevated for years. Bankruptcies stay on file for seven to ten years depending on the chapter. This is worse than personal credit in some ways because commercial lenders scrutinize liens more aggressively than personal bankruptcy events. The assumption is that a business with a lien has structural cash flow problems, not just a temporary hardship.
Monitoring and Maintenance
Set up monitoring with at least one bureau. Dun & Bradstreet offers free alerts for significant file changes. Experian Business and Equifax also provide monitoring tools. Check the file quarterly if possible. Dispute inaccuracies immediately because correcting a wrong address or a duplicated entry can restore points faster than adding new positive accounts. Predictable payment timing matters more than perfect timing. Paying every invoice on day one of the terms is acceptable, but inconsistent payment behavior — paying early one month, late the next — raises red flags. Lenders prefer steady patterns. The algorithm sees volatility as higher risk even if the average payment date is early.
When Business Credit Stops Working
Business credit is not a magic bullet for cash flow. It improves borrowing terms and increases available capital, but it does not generate revenue. A strong PAYDEX score of ninety-five will not help a company that cannot pay suppliers because sales collapsed. Some businesses treat credit building as a substitute for operational health. It is not. Credit is a reflection of financial behavior, not a generator of it. Overextension is the real danger. Opening too many trade lines at once triggers multiple hard inquiries and spikes utilization temporarily. Each hard inquiry can drop a score by two to five points. Stacking ten applications in a thirty-day window can compound that into a noticeable dip. Space out applications. Three to four months between new credit requests is reasonable for small businesses building from zero.
Realistic Timeline Expectations
From formation to a usable business credit line without a personal guarantee typically takes eighteen to thirty-six months for most small businesses. Companies with strong revenue, clean records, and consistent reporting can shorten that. Companies with late payments, filings errors, or cash flow volatility extend it significantly. There is no shortcut that does not involve either risk or cost. Predatory "credit repair" services that promise fast business credit are usually selling nothing but hope and upfront fees. The process is boring by design. That is the point. Commercial lenders reward predictability, not cleverness. The businesses that build durable credit profiles are the ones that treat the system like a slow-growing asset instead of a lever to pull. File correctly, pay on time, monitor the file, and let the history accumulate. Everything else is noise.